ADSK — AI Stock Forecast & Price Targets
Published 9/11/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live ADSK price forecast →
Autodesk is a high-quality SaaS compounder (29% op margin, 54% ROE, $3.16B FCF) trading at 14.9x forward P/E after a brutal -28% YTD drawdown that has taken price to $212.41, near the lower end of its multi-month range with RSI 35 and price -13% below the 200-day SMA. The setup is quality-at-a-discount with an analyst target of $315 and PEG 0.95, but the intact intermediate downtrend, recent $1B bond issuance, and the forecast model's poor recent calibration argue for measured accumulation rather than aggressive buying.
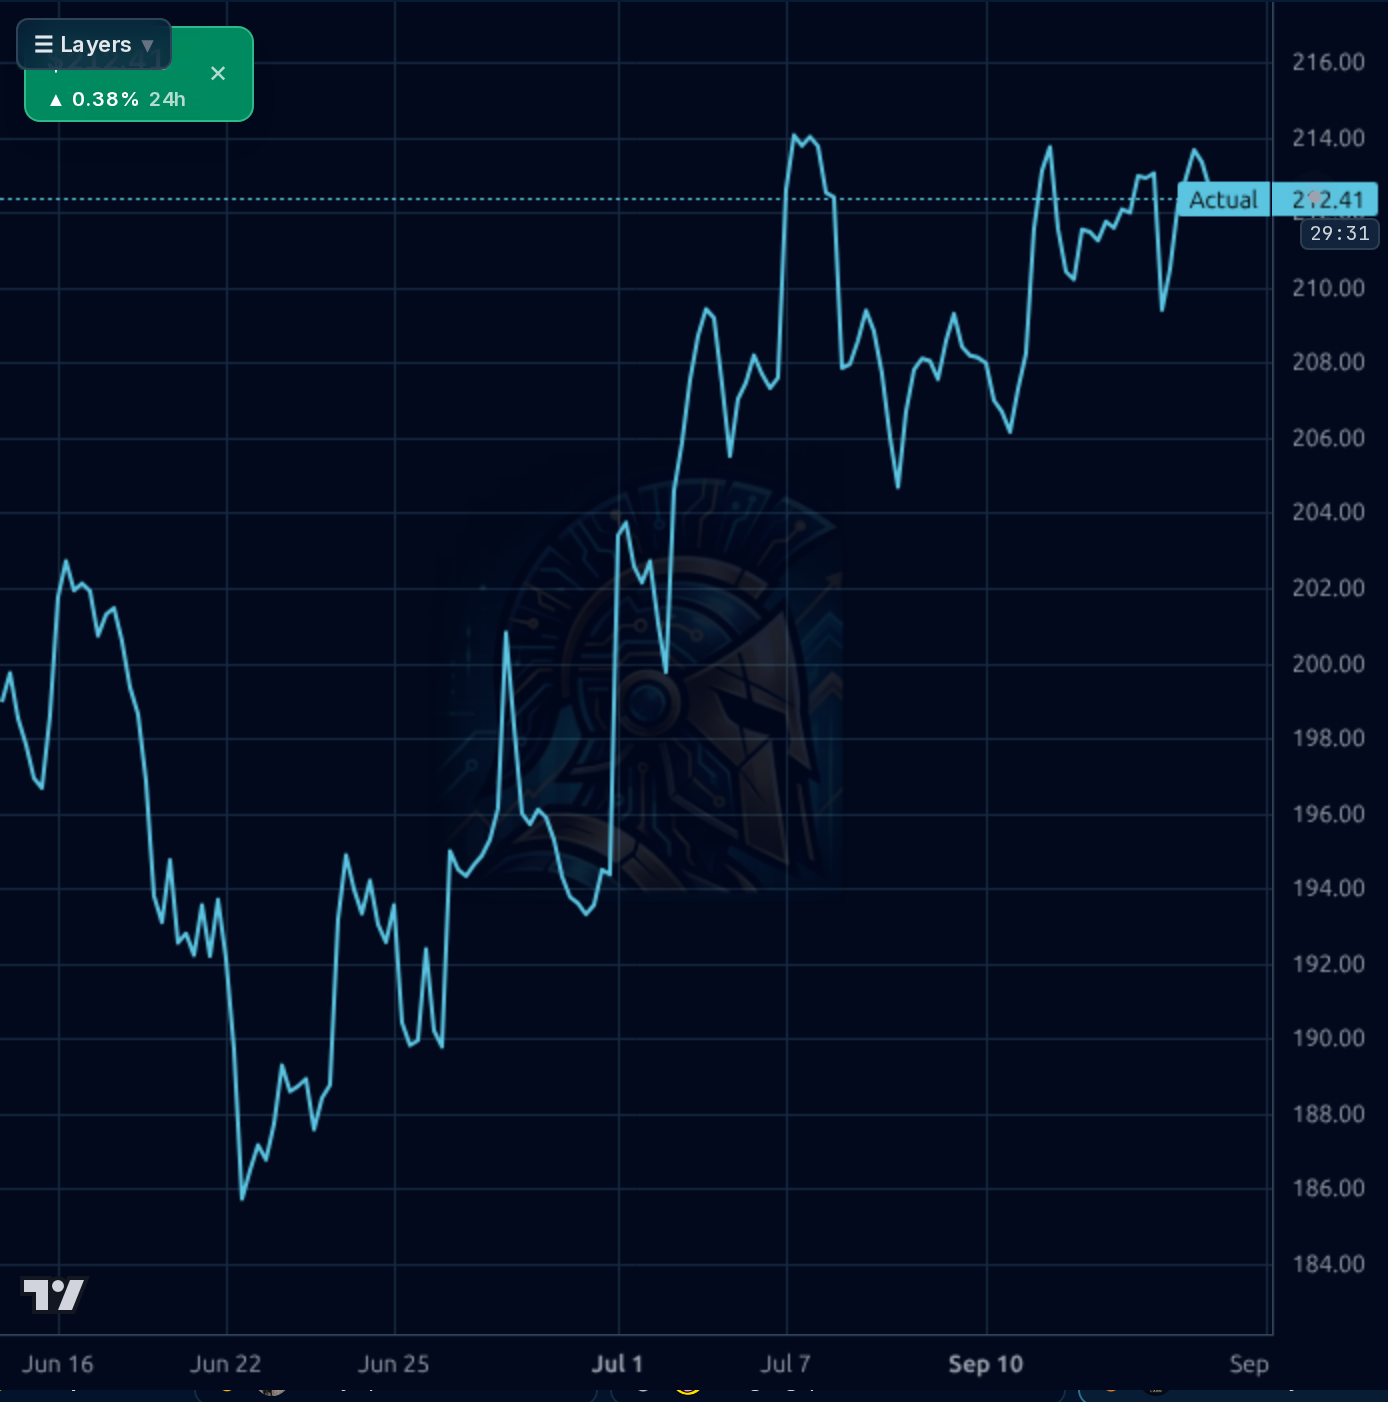
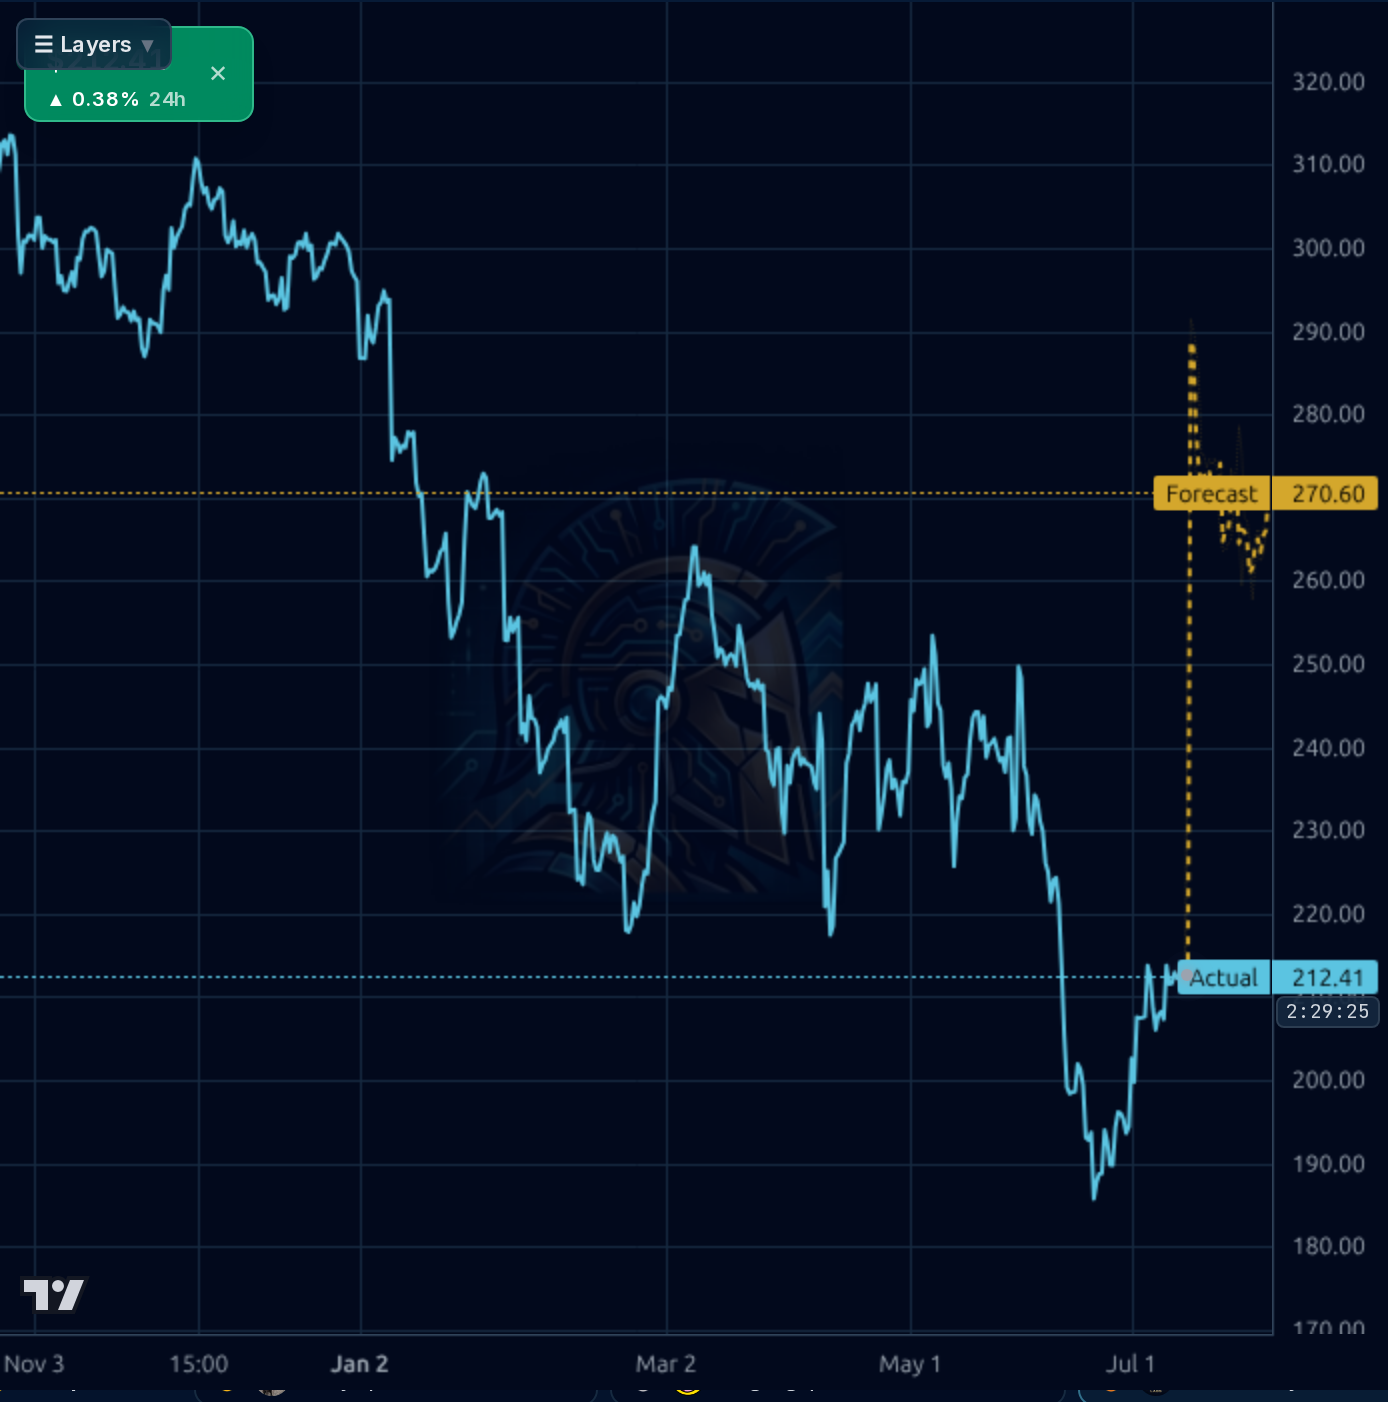
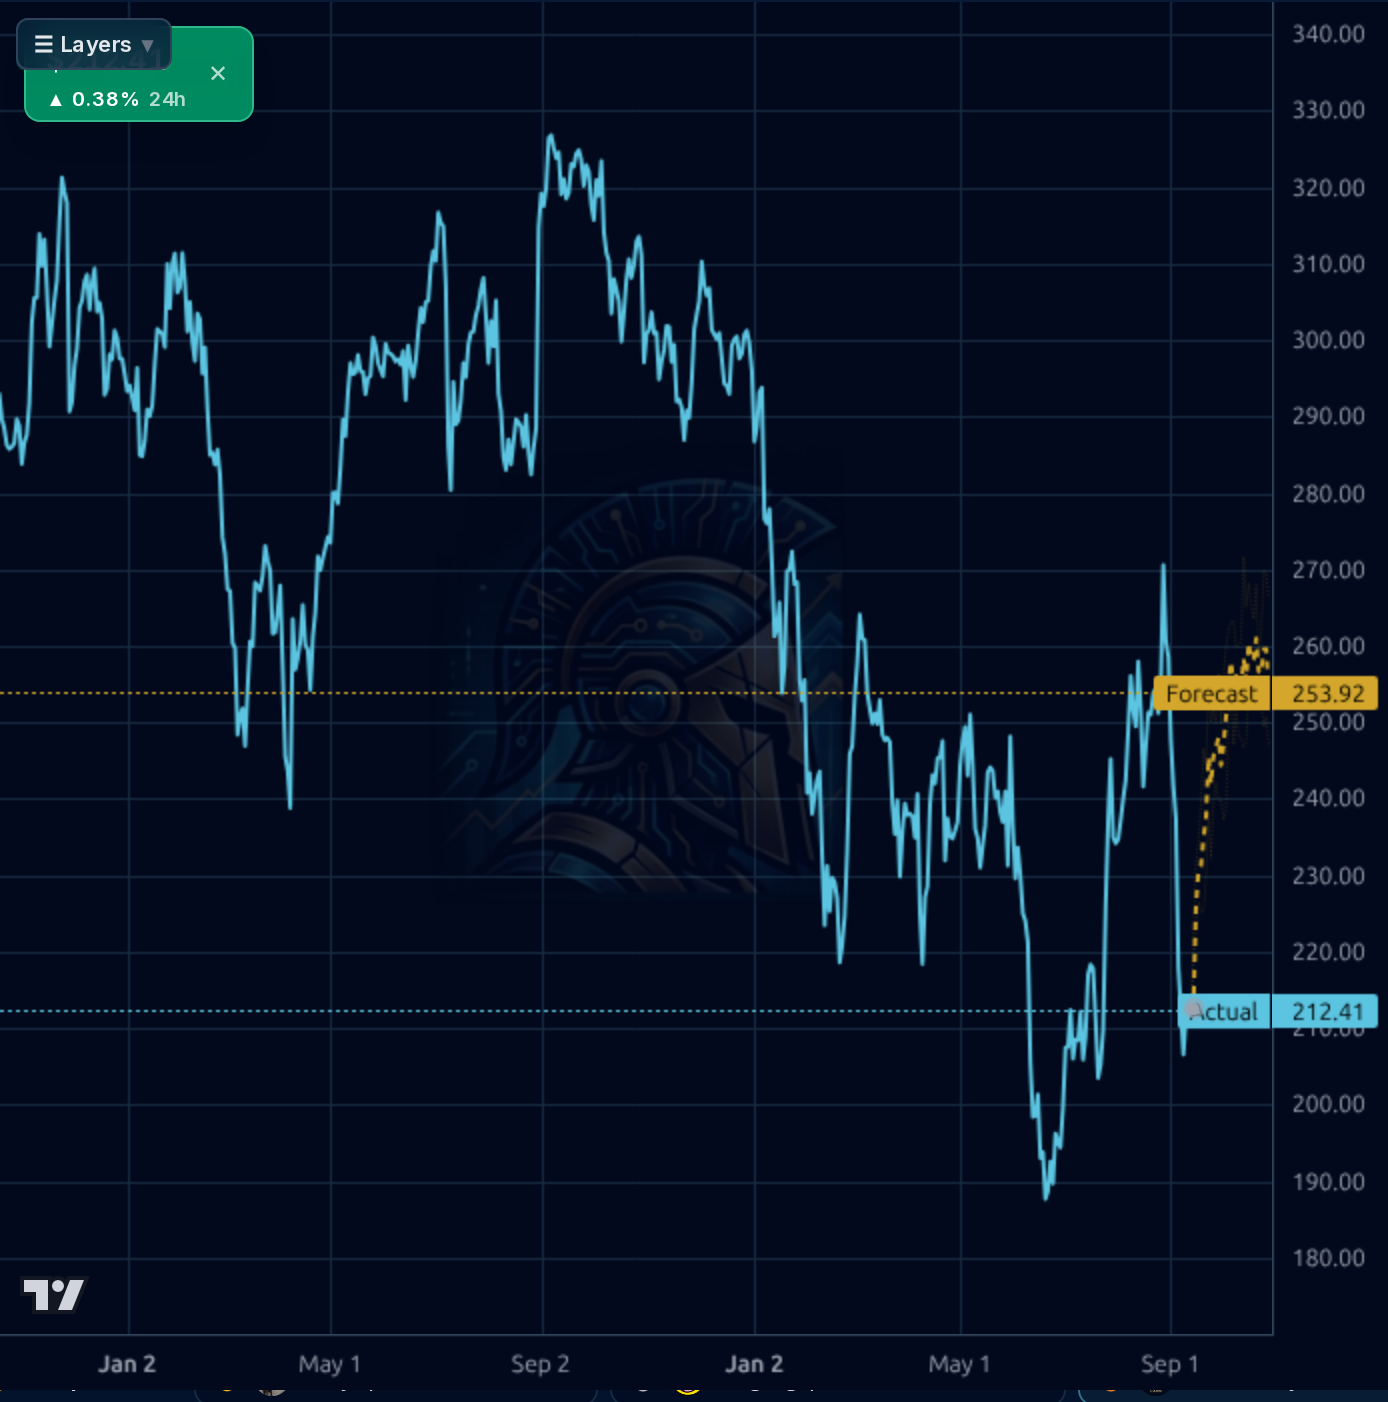
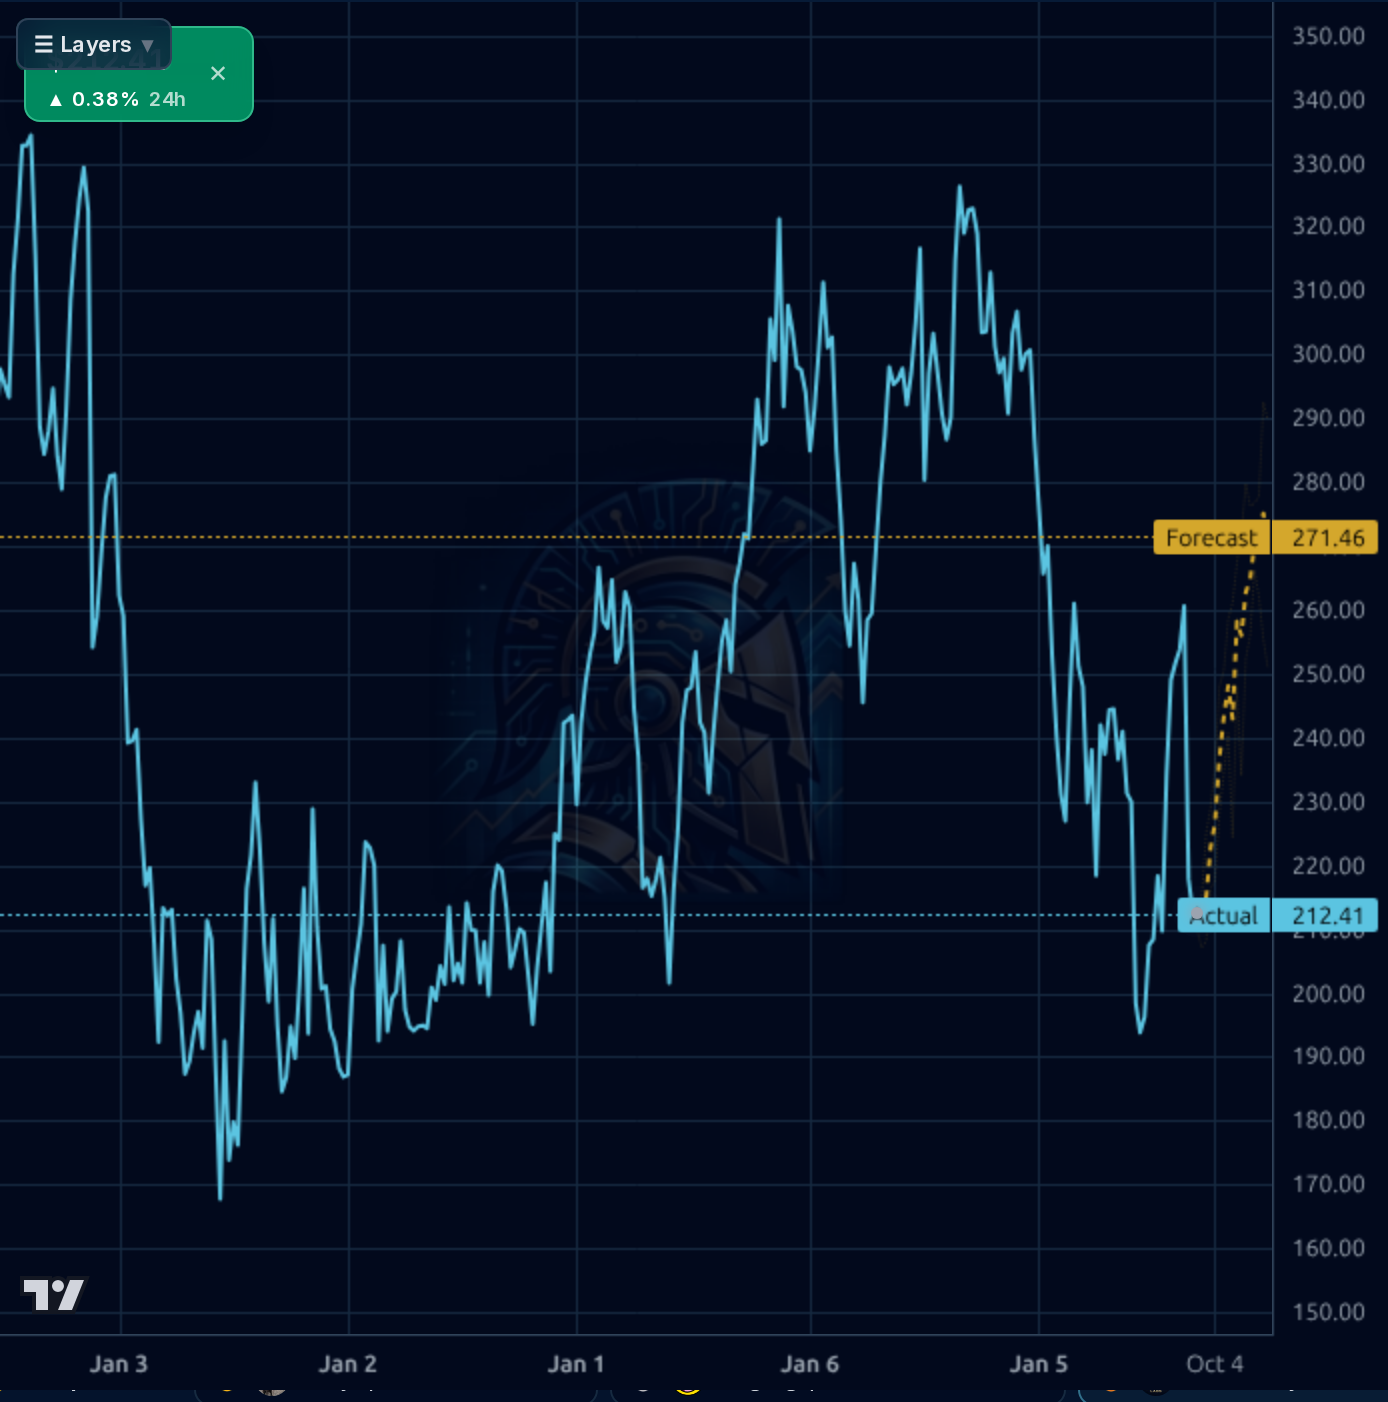
Over 1-4 weeks the setup is a mean-reversion candidate but not a chase. Price at $212.41 with RSI 35 near the lower end of the range suggests limited additional downside barring a broad-market break, but the trend is down and momentum is negative (-15% month, -10.6% week). Action: scale in with a first tranche near $210 and reserve dry powder for $200 and $190 tests; avoid buying strength above $220 without volume confirmation. Invalidation: a decisive close below $190 (would break the June low base and open $180). Position sizing: half-normal until price reclaims SMA50 (~$232). Ignore the model's 1d/1wk forecast — it is unreliable in this regime.
Over 1-6 months the thesis is a re-rating on Q3 FY27 print (Nov 27) if MaintainX integration is disclosed cleanly and billings sustain double-digit growth. At 14.9x forward P/E and PEG 0.95 for a 29% operating margin business with $3.16B FCF, the risk/reward from $210 area is favorable. Base case: mean reversion to $240–$250 (SMA200 reclaim) over 3-6 months for +13-18%. Bull case: $275-285 on earnings validation + macro stabilization (+29-34%). What changes my mind: a Q3 miss or reduced FY27 guidance, further shareholder litigation escalation with quantified liability, or a broad SPY breakdown given the neutral/deteriorating breadth backdrop (46% >200dMA).
Over 1-3 years Autodesk remains a durable subscription compounder anchored in the AEC and manufacturing verticals with high switching costs and expanding platform reach through MaintainX (maintenance/ops) and AI-embedded design tools (Design Assistant, Revit AI). The FCF engine ($3.16B TTM growing) supports continued buybacks and tuck-in M&A, and the forward EPS estimate of $14.21 suggests a plausible $300+ price at a normalized 20-22x multiple. Biggest structural risk: AI-native CAD entrants (e.g., generative design startups) could compress pricing power and erode the moat if Autodesk fails to execute on its own AI roadmap; secondary risk is prolonged cyclical weakness in construction/manufacturing capex.
Autodesk's fundamentals remain elite: TTM revenue $7.79B with Q2 FY27 revenue of $2.046B (+16.8% Y/Y), operating margin 29.2%, net margin 24%, ROE 53.9%, ROIC 29.6%, and gross margin 91%+. FCF is exceptional at $3.16B TTM with $554M generated in Q2 alone despite lumpy billings. The balance sheet carries $4.16B cash vs $3.7B debt (net cash slightly positive), though debt/equity 109% and current ratio 0.86 reflect an aggressive capital structure typical for subscription businesses with large deferred revenue. The 2026-09-10 8-K discloses a new ~$1B senior notes issuance to refinance an existing Citi term loan — neutral on leverage but confirms proactive liability management. EPS Q/Q growth of 60% and Y/Y TTM growth of 59% support the forward P/E of 14.9 and PEG 0.95, which is genuinely cheap for a business of this quality. What's working: recurring revenue, margin discipline, FCF conversion, capital returns ($1.2–1.3B buyback target). What's less clean: MaintainX integration overhang on near-term margins and the intermittent shareholder litigation noise.
The tape is decisively broken across all timeframes I reviewed. On the 1h chart, price recovered from $186 in late June to $214 in early July, then chopped in a $208–214 range before pulling back to $210 and recovering to $212.41 — a modest short-term base but no trend. The 4h and daily views show price is well off the $326.71 52-week high (-35%) and only $27 above the $185.50 52-week low, with SMA20 -12.1%, SMA50 -8.4%, and SMA200 -13.5% all overhead. RSI 35.5 is oversold-ish but not capitulation, and Perf Month is -14.9% while Perf Week is -10.6% — active distribution, not accumulation. The weekly chart confirms a lower-high, lower-low structure since the Sep 2025 peak near $327. The model's forecast bands are strongly bullish across timeframes (4h forecast $270, 1d $253, 1wk $271), but the reliability data is damning: 1d directional accuracy 42% vs 68% naive baseline, 1wk 67% vs 83% naive — the model is BEATEN by naive persistence in this regime, so those upside targets should be heavily discounted. Key support: $210 (recent pivot), $200 (psychological), $185.50 (52w low). Key resistance: $225 (SMA50), $245 (SMA200 area), $270 (prior swing high).
Signal: (1) the 2026-09-10 SEC 8-K confirming a ~$1B senior notes offering underwritten by Morgan Stanley/BNP to refinance the Citi term loan — a housekeeping move, not a growth catalyst, but it locks in liability structure ahead of any rate move; (2) prior custom-research documents confirm Q2 FY27 was a beat-and-raise (revenue $2.046B, EPS beat, guidance raised, buyback lifted by $100M), yet the stock is DOWN meaningfully since — a textbook example of the pattern in the prior thesis that this name sells off despite good numbers; (3) management is on the road at Goldman Communacopia and Citi TMT (Sep 9) — no announced surprises. Noise: an Adobe-focused headline mislabeled in the feed, several general market items, and low-signal social sentiment (88% bullish crowd, but only 8 tagged messages — small sample). The most important omission is any material update on MaintainX integration ARR contribution or shareholder litigation progress, both of which remain overhangs. Next earnings 2026-11-27 is ~77 days out and is the binary event that will either validate or invalidate the re-rating case.
- MaintainX integration extending platform into maintenance/operations — initial ARR disclosures expected at Q3 FY27 earnings (Nov 27)
- Billings +36% in Q2 FY26 driven by new transaction model — sustainability into H2 is the key data point
- $1.2-1.3B FY27 buyback target (raised $100M) providing ~3% share-count reduction tailwind
- AI-embedded product cycle (Agentic AI, Design Assistant, Revit/Takeoff AI) supporting price realization and upsell
- $1B senior notes refinancing (Sep 2026) extends debt maturity and preserves capital flexibility for continued M&A
- Intact intermediate downtrend: price -13.5% below SMA200, -34.6% off 52-week high, with distribution pattern despite Q2 beat-and-raise
- Forecast model is beaten by naive baseline on both 1d and 1wk horizons — momentum signals unreliable in this regime
- Shareholder litigation overhang with no quantified liability disclosure, weighing on multiple
- MaintainX integration near-term margin/cash-flow impact may not be fully baked into guidance
- AEC and manufacturing cyclicality — SPY breadth deteriorating (46% >200dMA) suggests macro tape risk
- Valuation still 27.5x trailing P/E — a multiple compression risk if forward EPS estimates get cut
- Competitive threat from AI-native CAD entrants (generative design) over 2-3 year horizon
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord