AJG — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live AJG price forecast →
AJG is a high-quality insurance broker with strong revenue growth (24% YoY in Q2) and healthy FCF, but the stock has rolled over from $313 highs to $248, sitting -4% YTD and below both SMA20/SMA50. Valuation is stretched on trailing metrics (P/E 41, P/B 2.68) but reasonable on forward (P/E 16.6, PEG 1.02) with a $295 street target, warranting an accumulate stance on weakness ahead of the Oct 29 earnings catalyst.
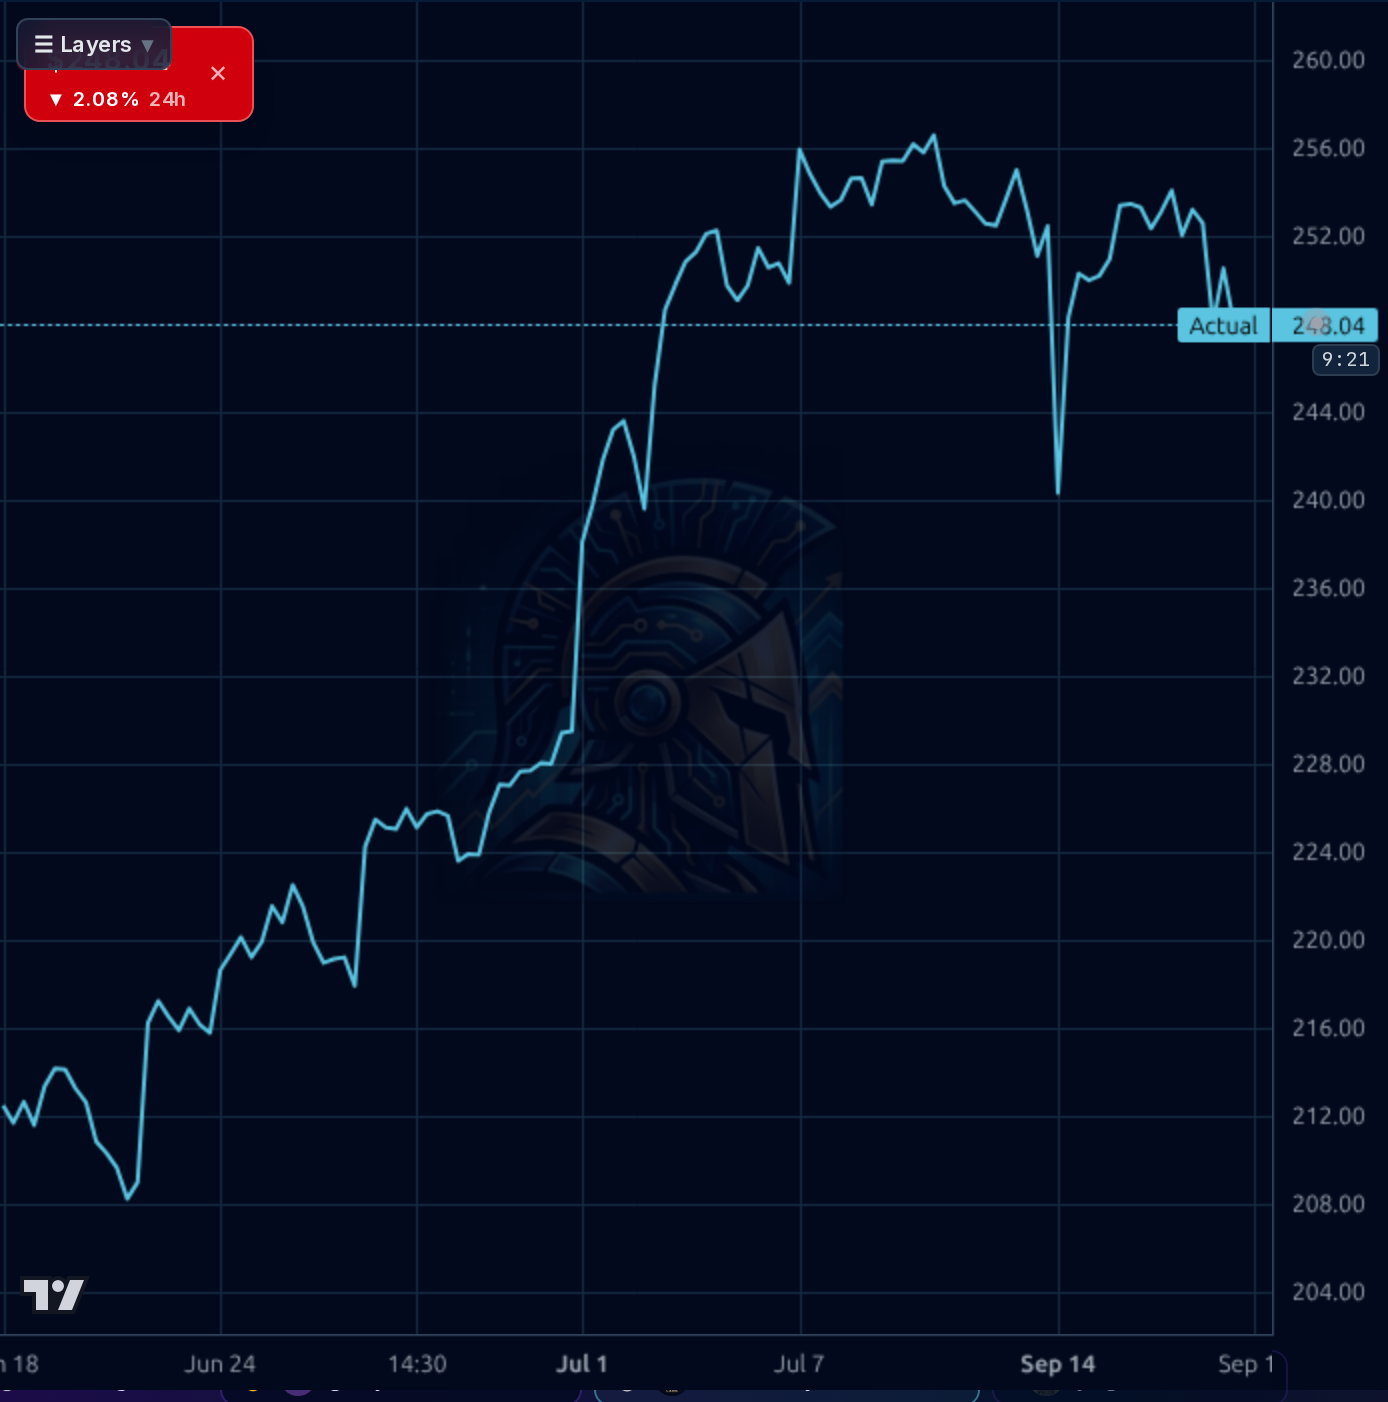
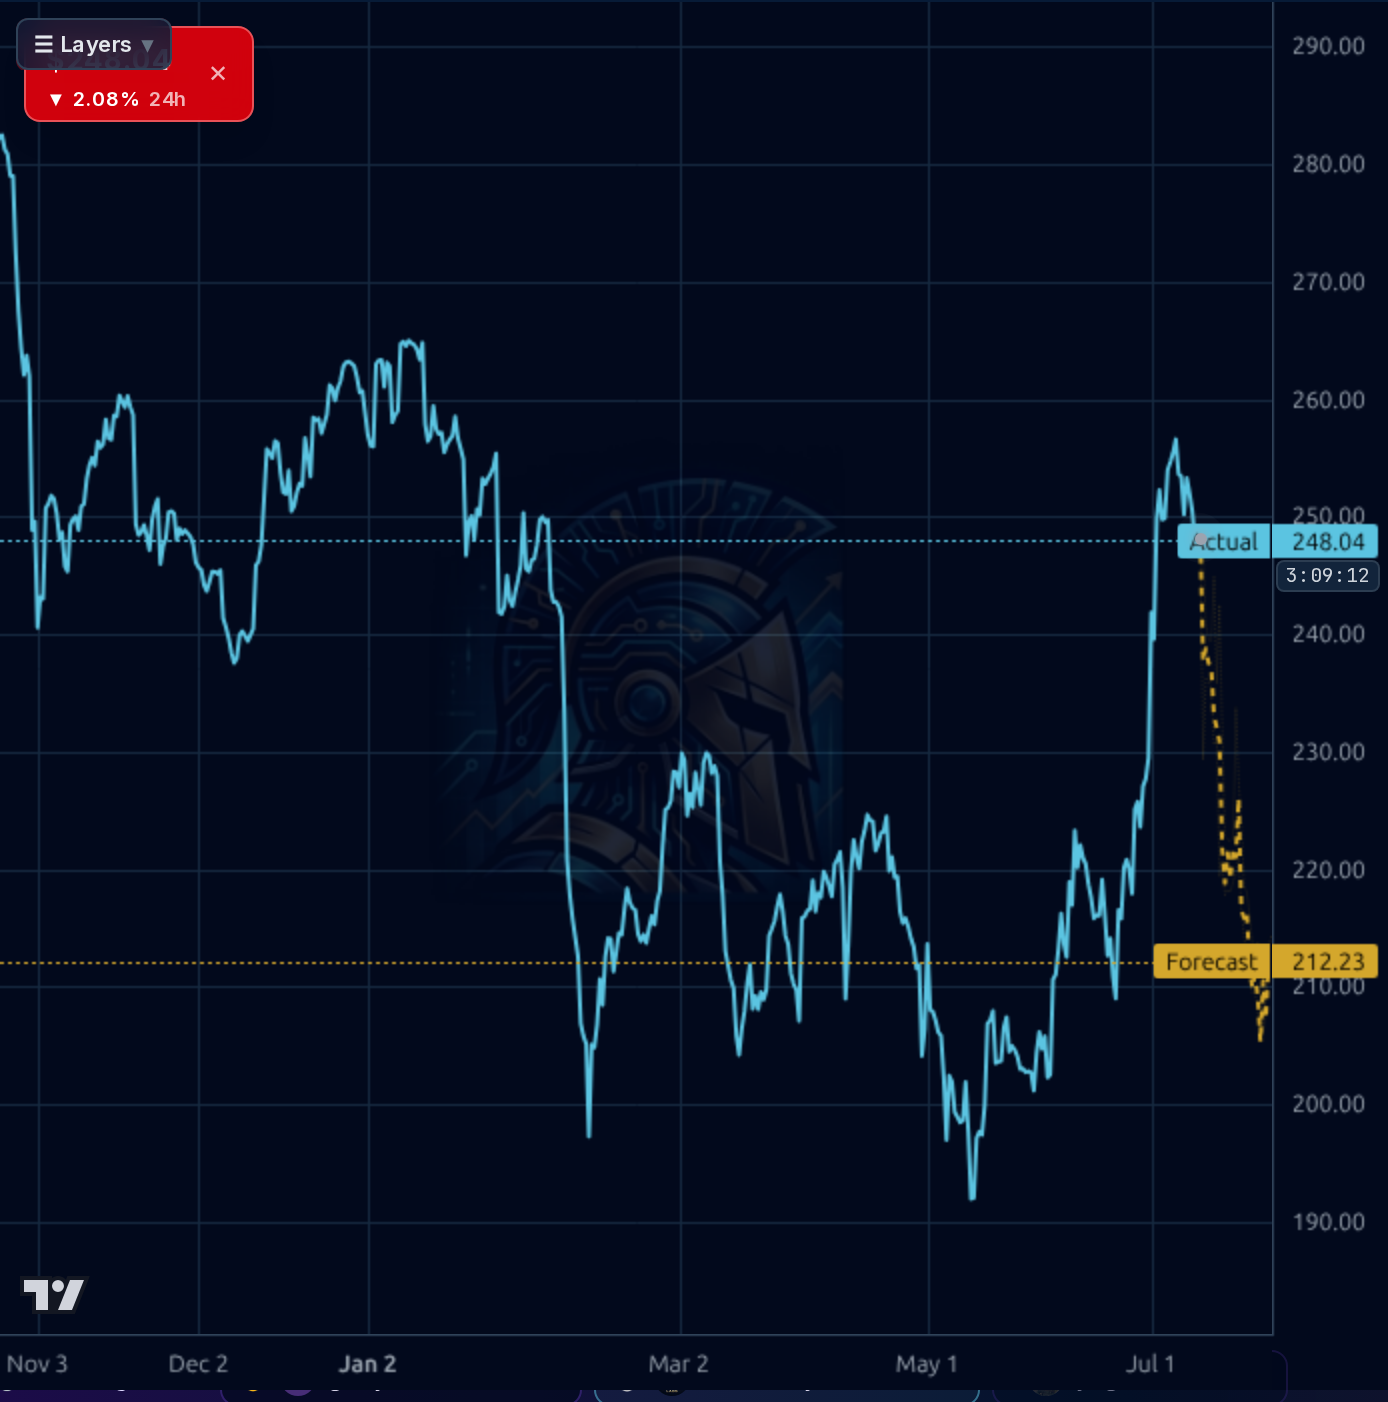
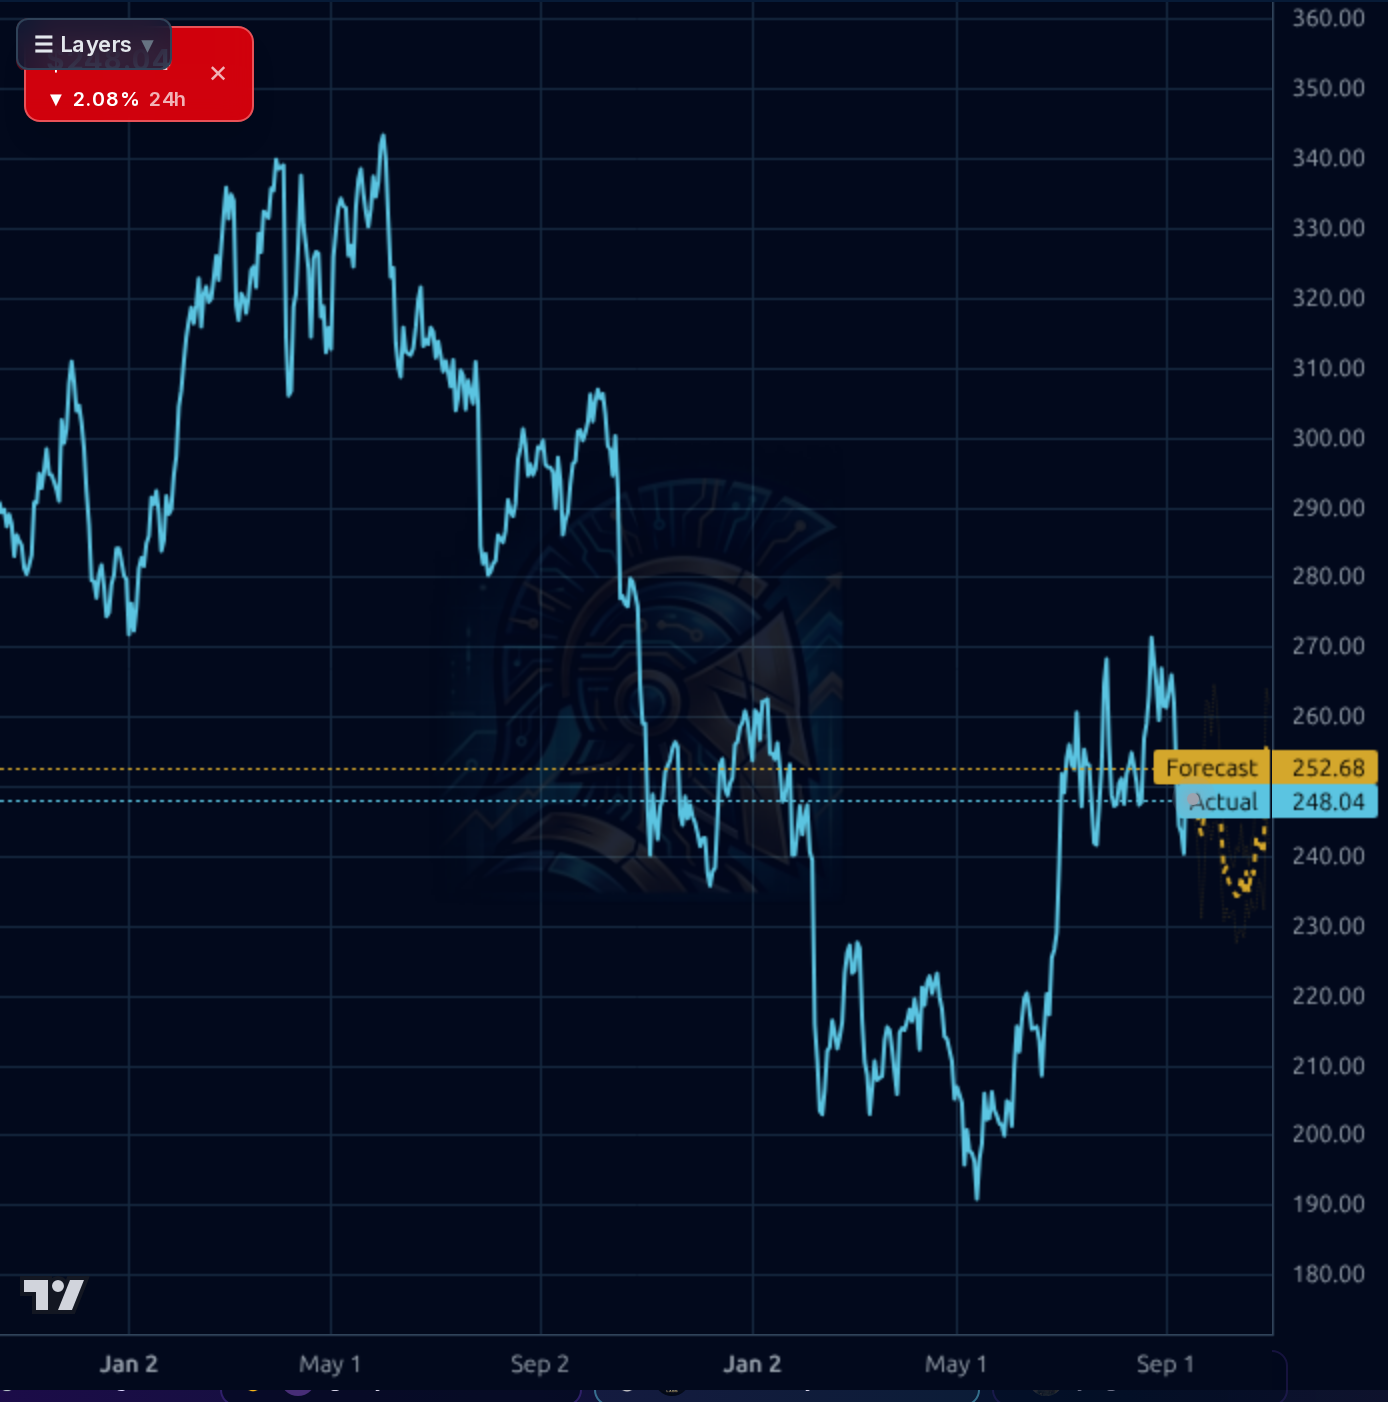
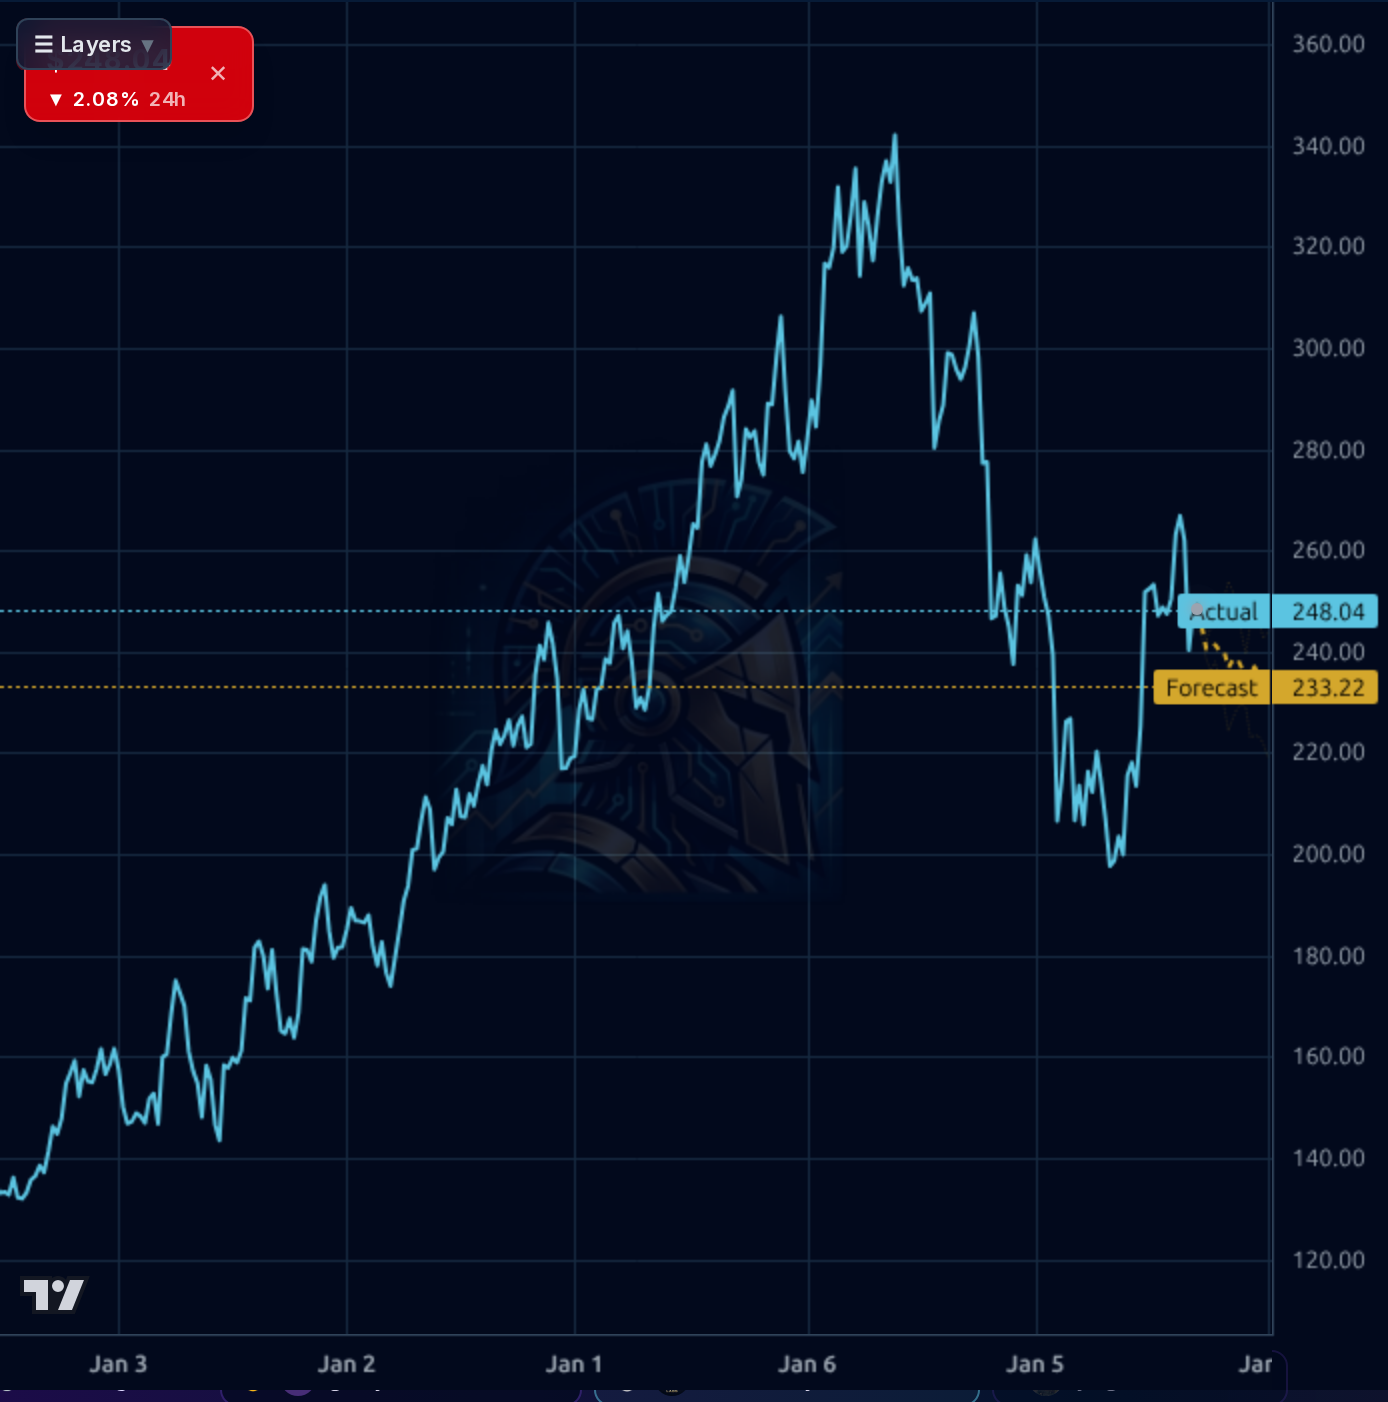
1-4 week view: Neutral-to-cautious into the Oct 29 earnings print (~44 days out). The technical structure is broken with price below SMA20/50 and the model's near-term probability at 0.20. I would NOT initiate a full position here. Wait for either (a) a hold and reclaim of $252-256 with volume, or (b) a flush toward $240 (recent spike low) or $233 (model base) for a starter tranche. Invalidation: sustained close below $240 opens $220. Do not size a swing trade INTO the print — this is a pre-earnings play only, with the print as key binary catalyst.
1-6 month view: Constructive. The forward P/E of 16.6 and PEG of 1.02 are reasonable for a compounder growing sales 26% and EPS estimates at 16% forward 5Y. The Innovise deal continues the accretive M&A engine. Analyst target of $295 implies +19% upside. Expected return range: $260-290 (+5% to +17%) over 3-6 months assuming earnings confirm the forward EPS trajectory ($14.89) and margin resilience. Change my mind: (1) organic growth decelerates below mid-single-digits on the Q3 print, (2) property pricing collapse compresses commissions materially, or (3) a break below $220 confirming a larger topping pattern.
1-3 year view: AJG remains a best-in-class serial acquirer in a fragmented, structurally growing insurance brokerage market. Multi-year drivers: continued bolt-on M&A (67K+ employees, global platform), rising insurance complexity (cyber, climate, ESG) driving broker demand, and operating leverage from scale. The 10Y perf of +396% reflects the compounding model. Biggest structural risks: (1) an insurance soft market cycle compressing commission rates for a multi-year period, (2) leverage building from serial M&A eventually pressuring returns, and (3) the market re-rating brokers lower as growth normalizes toward mid-teens. Terminal thesis intact; the entry price matters more than the timing here.
Revenue is accelerating sharply — Q2 2026 revenue of $4.0B and Q1 of $4.76B mark a meaningful step-up from $3.37B in Q3 2025, with TTM sales +26.7% YoY. Operating margins are healthy at ~19% consolidated (Q1 hit 25.6% though Q2 dipped to 14.7%, suggesting seasonality/integration costs), and gross margins remain in the 40-46% range. However, trailing EPS of $6.03 vs forward EPS of $14.89 shows a large expected step-up that must materialize to justify the P/E of 41. Balance sheet has expanded meaningfully post-M&A (total assets $81.8B, up from $70.7B in Dec 2025), with $14.1B debt against $23.7B equity (D/E 0.59) — manageable but elevated. FCF generation is strong on annual basis ($2.08B TTM, $921M in Q1) but Q2 FCF was negative ($-41M), likely M&A-related working capital. ROE at 6.7% and ROIC at 4.3% are underwhelming for the multiple. Capital allocation continues to favor bolt-on M&A (Innovise announced Sep 15) with a 1.11% dividend yield and 45% payout ratio.
The picture is deteriorating across timeframes. The weekly chart shows AJG peaked near $340 in early 2025 and has traced a lower-high pattern, with the recent bounce from $190 lows stalling at ~$270. Daily chart shows price at $248, sitting -3.88% below SMA20 and -2.66% below SMA50, though still +6.08% above SMA200 — a classic breakdown-in-progress. RSI at 45 is neutral-weak. The 1h and 4h charts show a sharp rejection from the $256 area after a strong June-July rally, with a violent spike-down to $240 that was bought but has since resumed selling. The AI forecast band is decisively bearish across 4h (targeting $212) and 1d (targeting $233-253), which aligns with the model's 0% bullish probability reading. The stock is -20.9% off 52-week highs and -14.3% YoY, confirming the momentum breakdown. Critical support sits at $240 (recent spike low), then $220, with $190 as the ultimate 52-week floor.
Signal: The Sep 15 Innovise Business Consultants acquisition continues the accretive M&A playbook — a specialty commercial/surety broker in construction, energy and real estate verticals. The Sep 9 workforce trends report and Silver Beech Capital's Q2 letter initiating a position provide modest positive framing from institutional investors. A SeekingAlpha piece explicitly frames AJG as recession/inflation-resilient at a low FCF multiple. The Aug 27 8-K disclosed a CFO/accounting leadership transition — worth monitoring but not thesis-changing given the succession appears planned. Noise/mild negatives: Insider selling clustered in late Aug/early Sep ($7.3M across three VPs) is a soft negative but consistent with 10b5-1 plans, not a red flag on its own. The L1 institutional ownership drop from 92.7% to 88.8% is a mild bearish rotation signal. Overall news flow is constructive on fundamentals but doesn't yet counter the technical breakdown.
- Sep 15 Innovise Business Consultants acquisition adds specialty commercial insurance and surety bonding in construction/energy/real estate/manufacturing verticals
- Q2 2026 revenue of $4.0B (+~24% YoY implied) demonstrates continued M&A + organic growth acceleration
- Forward EPS estimate of $14.89 vs trailing $6.03 implies a step-change in profitability from acquired revenue base
- Robust $2.08B TTM FCF fuels further accretive bolt-on M&A pipeline and 8.4% 3Y dividend growth
- Global platform (67K employees, 72K per profile) enables continued international brokerage market share gains
- Technical breakdown: price below SMA20/SMA50, -20.9% off highs, model gives 0% bullish probability on 1d/1wk
- Q2 FCF turned negative (-$41M) and Q2 EPS Q/Q -10.85% — margin/cash flow lumpiness could signal M&A digestion issues
- Trailing P/E of 41 and P/B of 2.68 are demanding; ROE of 6.7% and ROIC of 4.3% look modest for the multiple
- Insider selling cluster: $7.3M across three VPs in the last 3 weeks provides a soft negative signal
- Institutional ownership dropped 3.9pp (92.7% → 88.8%) suggesting some large-holder rotation out
- Oct 29 earnings is a binary event 44 days out — expect gap risk and IV crush
- Property insurance pricing moderation could compress the commission tailwind that drove recent revenue acceleration
- D/E of 0.59 and $14.1B debt load leaves less cushion if the M&A machine hits an integration issue
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord