AVAV — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live AVAV price forecast →
AeroVironment offers a genuine structural defense-UAS growth story anchored by a record backlog, $500M Army C-UAS IDIQ, allied NATO wins and a fortress balance sheet, but Q1 FY27's return to a -$10.9M operating loss re-broke the Q4 FY26 profitability narrative and leaves a fwd P/E of ~34 without earnings support. With price $146.71 (-63% from highs, -37% YTD), 11.3% short interest, ARK accumulation and fresh partnerships (Nominal, BlueHalo awards), the setup is a low-conviction accumulate into weakness with tight risk defined at the $135.20 52-week low.
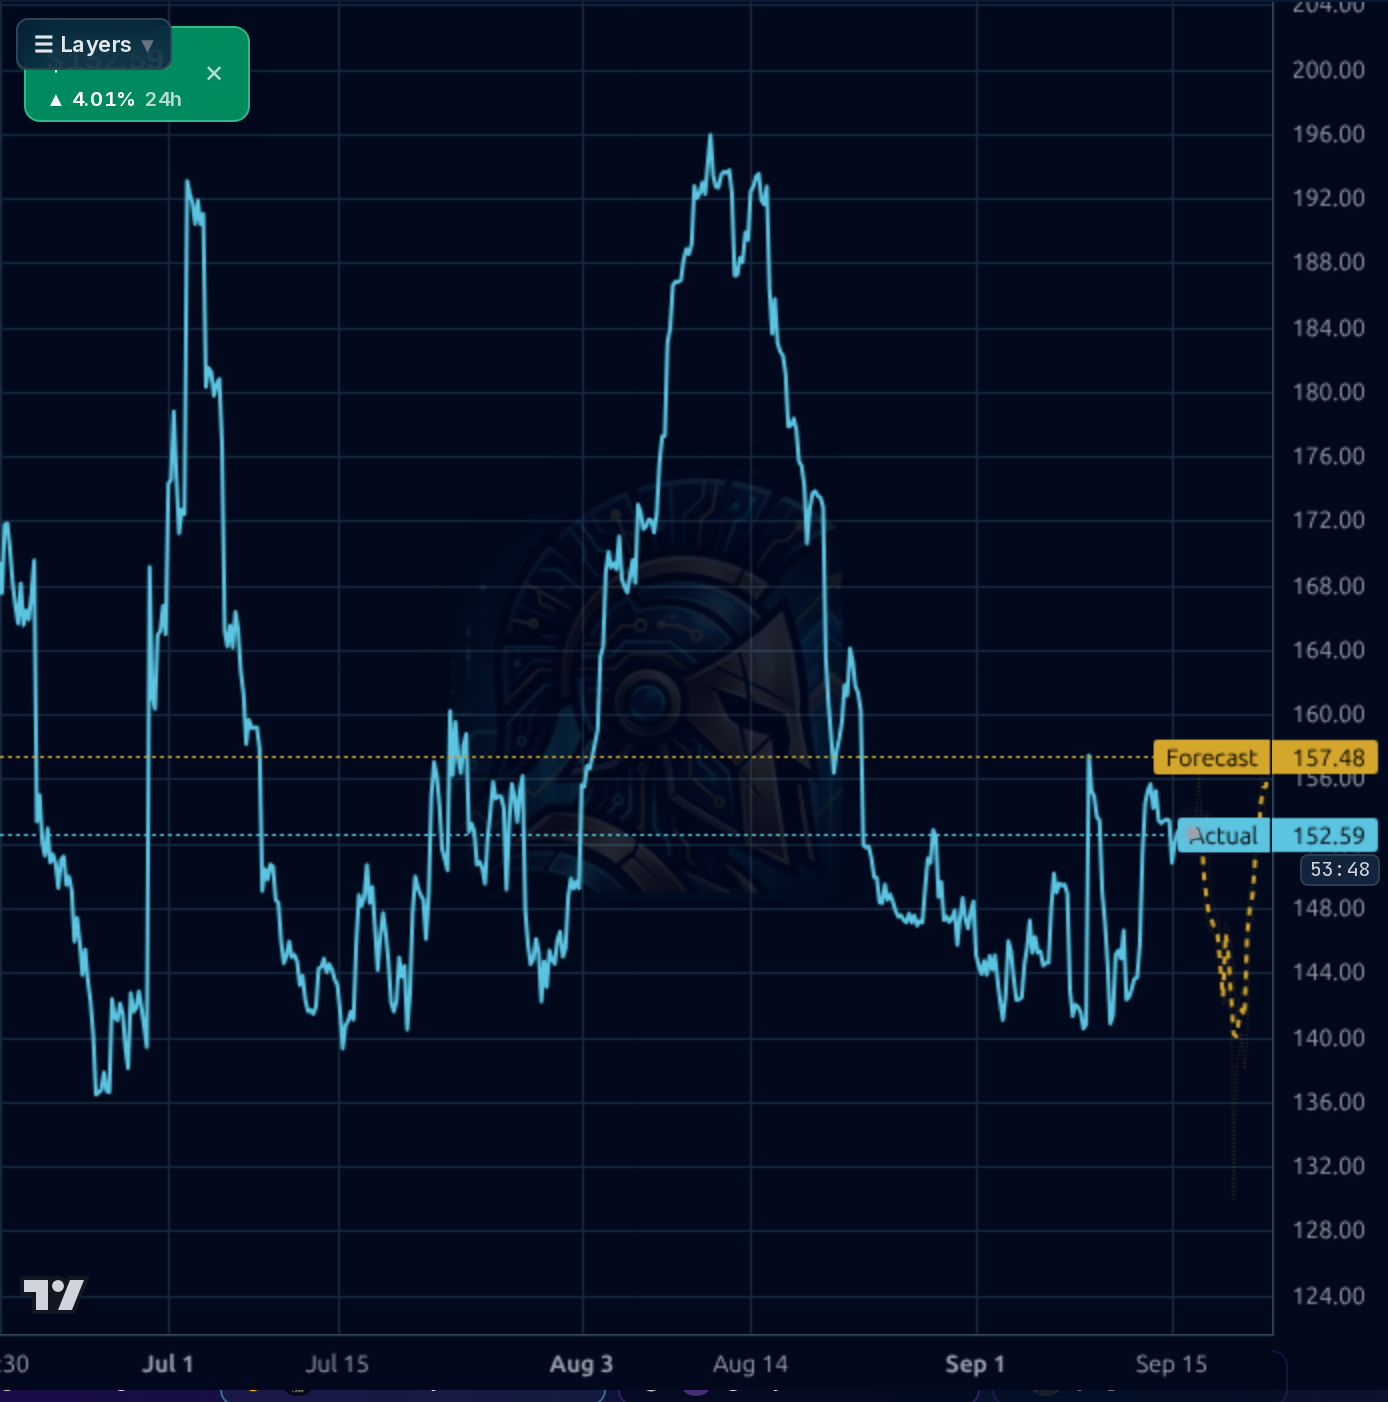
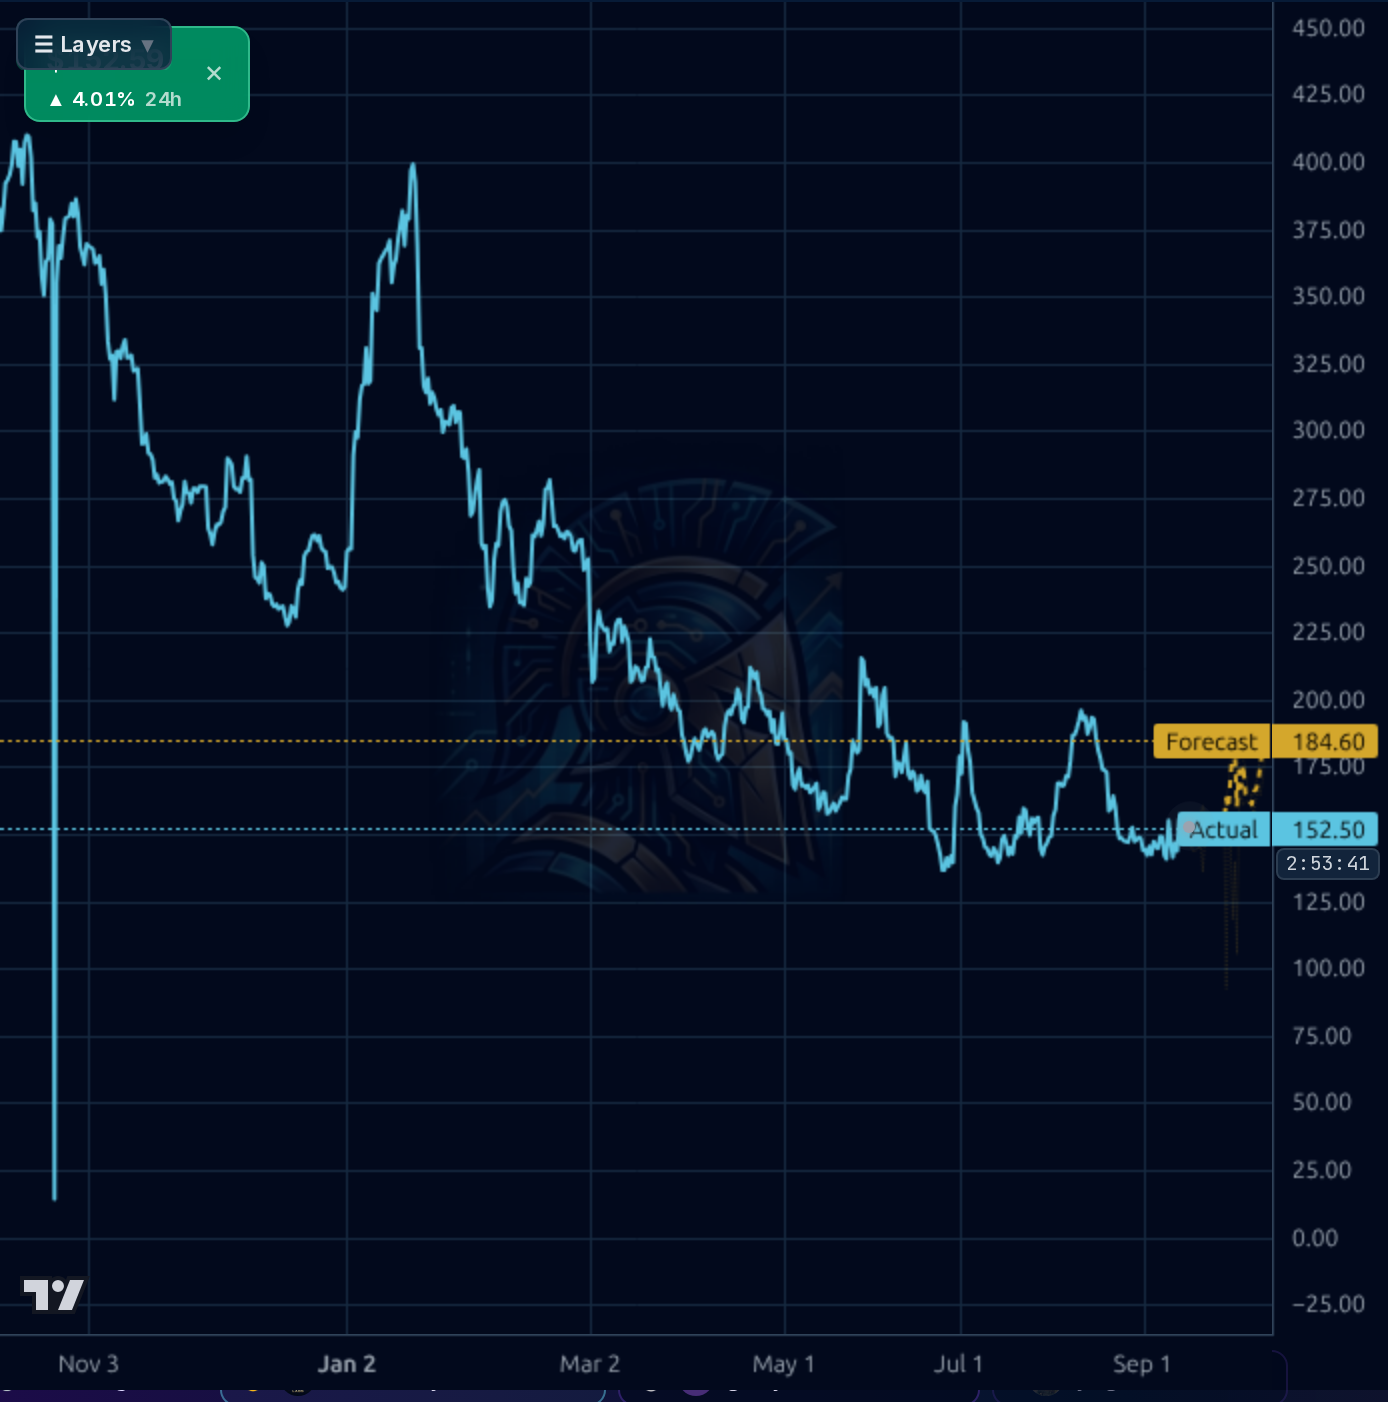
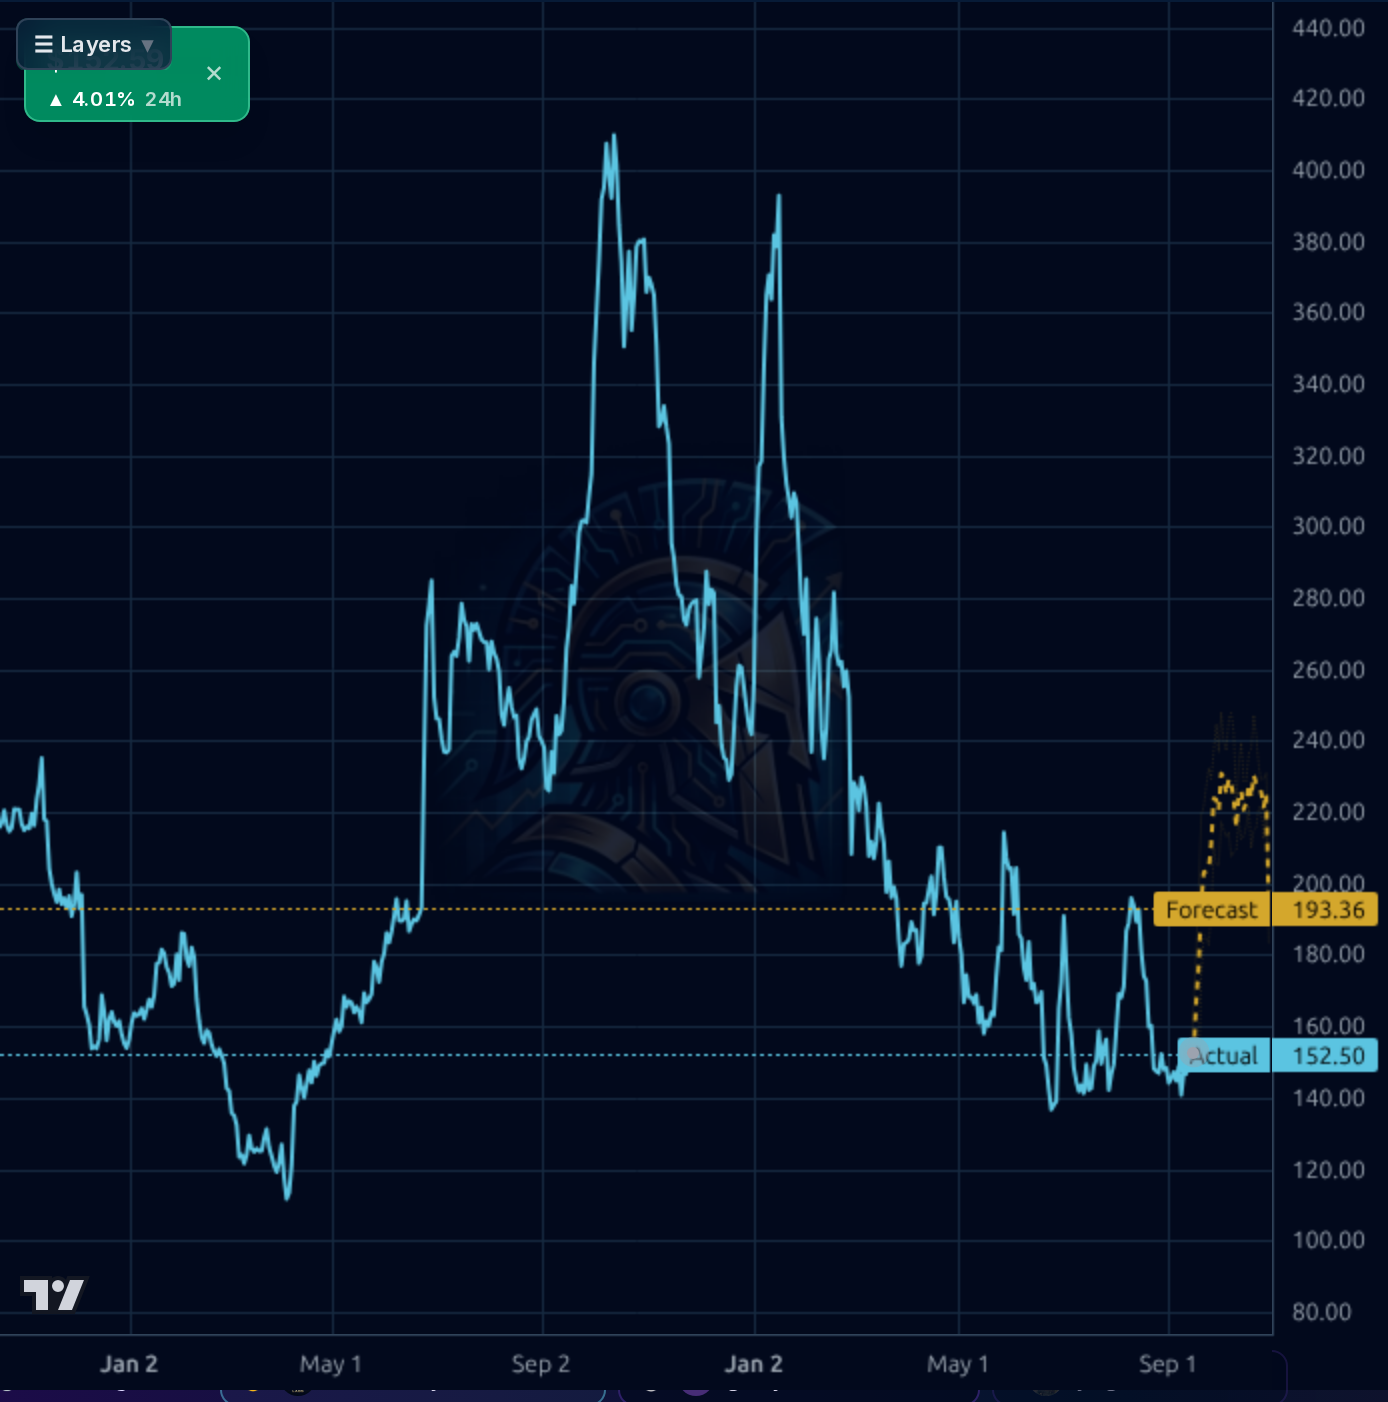
1-4 week view: The pullback from $153 → $147 offers a starter entry with $135.20 as hard invalidation (~8% risk). Scale in 1/3 near $145, 1/3 on any tag of $138-140, save 1/3 for a weekly close above $160. Do not chase above $158 without volume expansion. Trim/take partial into $168-172 if reached. Position sizing: half of a normal position given negative TTM earnings and unproven Q2 inflection.
1-6 month view: Thesis is that the FY27 back half re-establishes positive operating income as capex normalizes and Switchblade/C-UAS deliveries scale from the $500M IDIQ, driving a re-rating back toward $170-180. Expected return range: -8% to +25% from $146.71. Key catalyst: Q2 FY27 print (~Dec 2) — need gross margin recovery toward 30%+ AND positive operating income to sustain the multiple. What would change my mind: another operating loss with declining gross margin, or a break of $135.20 on a weekly close, either of which likely opens $115-120.
1-3 year view: Terminal thesis is that AVAV becomes the dominant US-domiciled loitering-munitions/C-UAS/directed-energy platform beneficiary of the Aug 2026 tariff proclamation and sustained allied defense budgets, delivering $3-4B revenue at 10%+ operating margins by FY29 and justifying $250-300+ per share. Multi-year drivers: NATO/German/Italian designations, BlueHalo directed-energy and space adjacencies, Switchblade production scaling, and domestic manufacturing preference. Biggest structural risk is competitive displacement by lower-cost domestic entrants (Anduril, Shield AI ecosystem) compressing gross margins before the operating leverage arrives, permanently capping the multiple at defense-prime levels rather than growth-tech.
Revenue trajectory is impressive at the top line — TTM $2.00B with sales Y/Y TTM +84.4% and Q1 FY27 up 5.7% sequentially to $480.5M — but the earnings story remains broken: TTM EPS -$4.10, net margin -10.1%, ROE -4.6%, ROA -3.6%. The Q4 FY26 apparent inflection (op margin 8.9%, gross margin 31.6%) did not persist; Q1 FY27 reverted to a -$10.9M operating loss on a 25.9% gross margin, and the sales growth estimate was cut sharply from 140.9% to 84.4% (an L3 bearish revision). Balance sheet is a real strength — $278M cash, D/E 0.19, current ratio 4.26, book value $86.50/share, $4.4B stockholders' equity — which funds the Moorpark/Ohio/Alabama capacity ramp without dilution. However, FCF was -$36M in Q1 FY27 after a positive Q4, and has been negative in 3 of the last 4 quarters as capex accelerates. Fwd P/E 33.8 and PEG 1.64 leave no cushion; the multiple is entirely priced on FY27 back-half re-inflection that is not yet demonstrated.
Structure is broken across all three timeframes visible: on the daily chart price is -63% from the $417.86 high, -27% below the 200-SMA, and in a persistent multi-quarter downtrend that only recently found footing near $135.20 (the exact 52W low). The 1h chart shows a modest lower-high/lower-low congestion under ~$155-160, with today's -4.4% pullback from $153.40 to $146.71 confirming that zone as active supply. The 4h/daily bounce off $135.20 has recovered to a 49 RSI (neutral) with the 20-SMA reclaimed (+0.35%) but the 50-SMA still overhead (-2.7%). The AI forecast band is directionally constructive (1wk near-term prob 0.60, bullish_prob 1.00 on 1d) but the 1d model has been beaten by the naive baseline (23% vs 81%) and 30-day MAPE is 39% — trust direction only, discount magnitude heavily. Key levels: $135.20 hard invalidation, $155-160 reclaim line, $172-180 next resistance if $160 clears on a weekly close.
Signal: ARK Invest added 29,016 shares (~$4.2M) this week, reinforcing an institutional accumulation narrative into weakness. A new Nominal strategic collaboration to supply test/operations data infrastructure should compress production ramp timelines for Switchblade and BlueHalo programs. Boeing's KC-46 award headline also noted BlueHalo (AVAV subsidiary) participating in adjacent defense awards, and the sector-relative rally on 9/14 (AVAV +5.7% vs peers flat) suggests a stock-specific post-earnings recovery bid rather than a group move. The Sept 9 8-K (Q1 FY27 print with Reg FD guidance) is the key primary-source catalyst driving the current reset. Noise: Retail sentiment is 100% bullish (contrarian caution near resistance), and insider activity has been small mechanical selling by a director and CAO ($35-48K clips) — not conviction signals in either direction. Congressional trade is a tiny $1-15K sell filed 43 days late — immaterial.
- Switchblade 600 production ramp funded by $51M delivery order and $100M Moorpark facility, with Ohio/Alabama capacity coming online
- $500M US Army C-UAS IDIQ providing multi-year loitering-munitions revenue visibility
- NATO / German / Italian Puma / P550 allied program designations opening European recurring revenue
- Aug 2026 US drone tariff proclamation redirecting DoD/allied procurement to domestic manufacturers
- BlueHalo directed-energy, digital beamforming and laser communications as higher-margin adjacencies beyond core UAS
- Sept 2026 Nominal test/operations data partnership to compress hardware production cycle times
- Q1 FY27 return to -$10.9M operating loss broke the Q4 FY26 inflection; two consecutive positive-op-income prints needed before re-rating is credible
- Fwd P/E 33.8 / PEG 1.64 vs TTM EPS -$4.10 leaves zero valuation cushion for another miss
- Institutional ownership bled -3.1pp in 45 days to 61.3%; 11.3% short float amplifies downside on disappointment
- FCF -$36M in Q1 FY27 with capex accelerating (Moorpark/Ohio/Alabama) — earnings-quality overhang persists
- Sales growth estimate cut 140.9% → 84.4% signals ongoing sell-side re-rating post FY27 guide
- Competitive pressure from Anduril and other US drone entrants could compress gross margins before operating leverage arrives
- Broken technical structure: -63% from highs, -27% below 200-SMA; break of $135.20 opens $115-120
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord