CLBT — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live CLBT price forecast →
Cellebrite is a high-gross-margin (~83%) digital forensics franchise with a fortress balance sheet ($442M cash, $125M TTM FCF, net cash ~15% of market cap), but the investment case is fractured by a Q2'26 operating margin collapse from 16.2% to 5.3%, a cut FY26 guide, CEO transition, and $4.7M of insider selling. With the stock at $11.23 down ~35% YTD and Nov 11 earnings ~57 days away, the setup is a asymmetric wait — cheap on FCF/cash, but momentum broken and prior bullish targets have systematically failed to print.
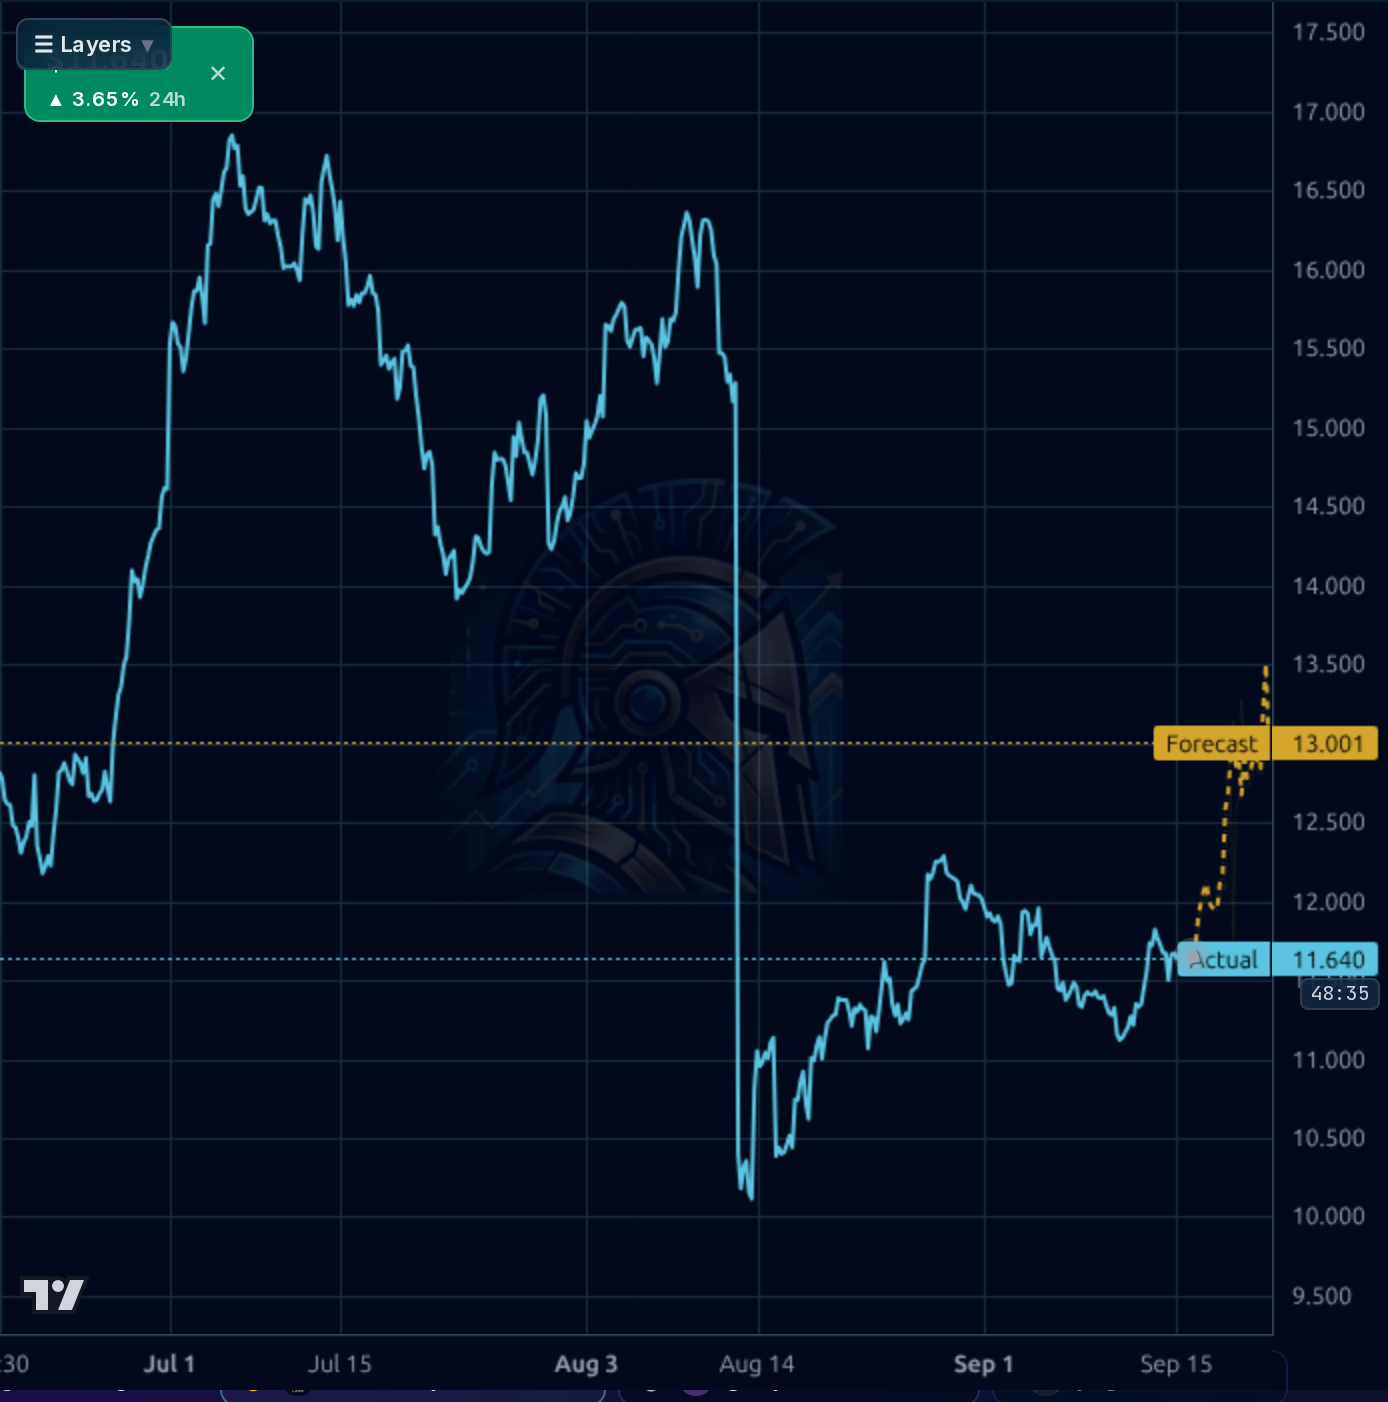
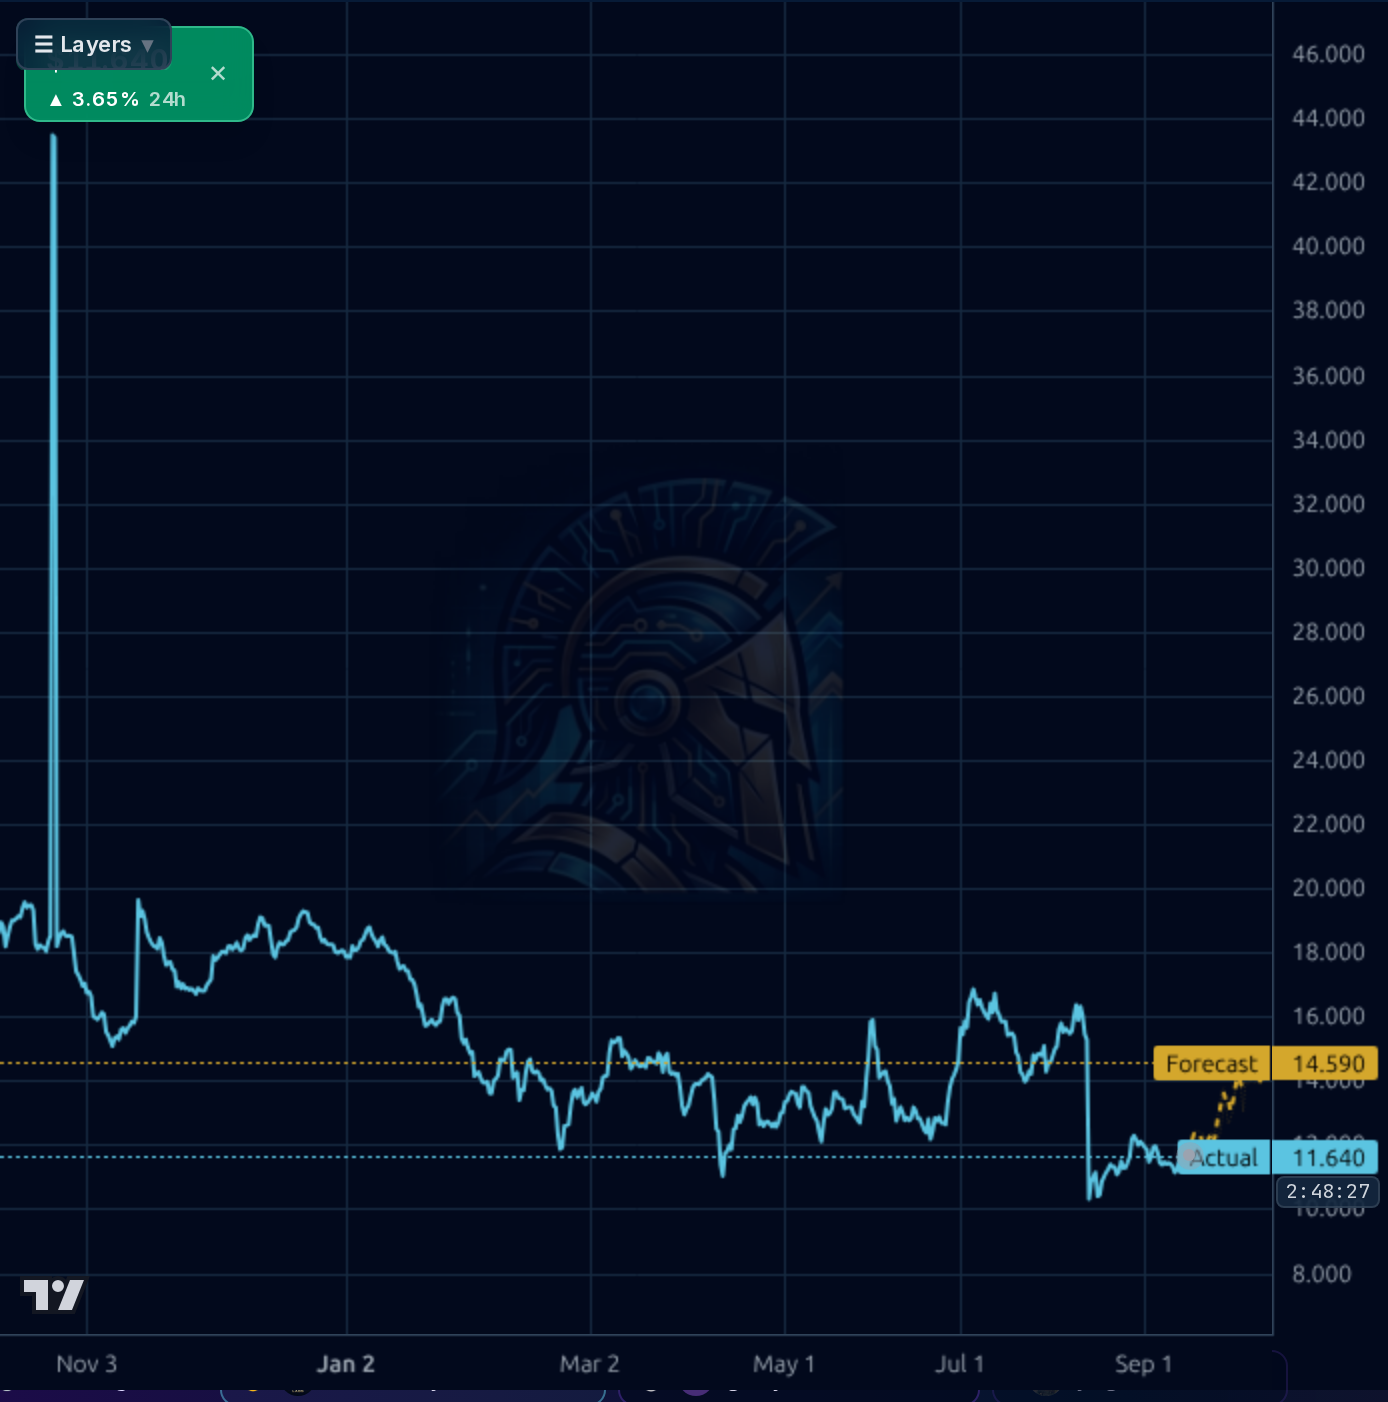
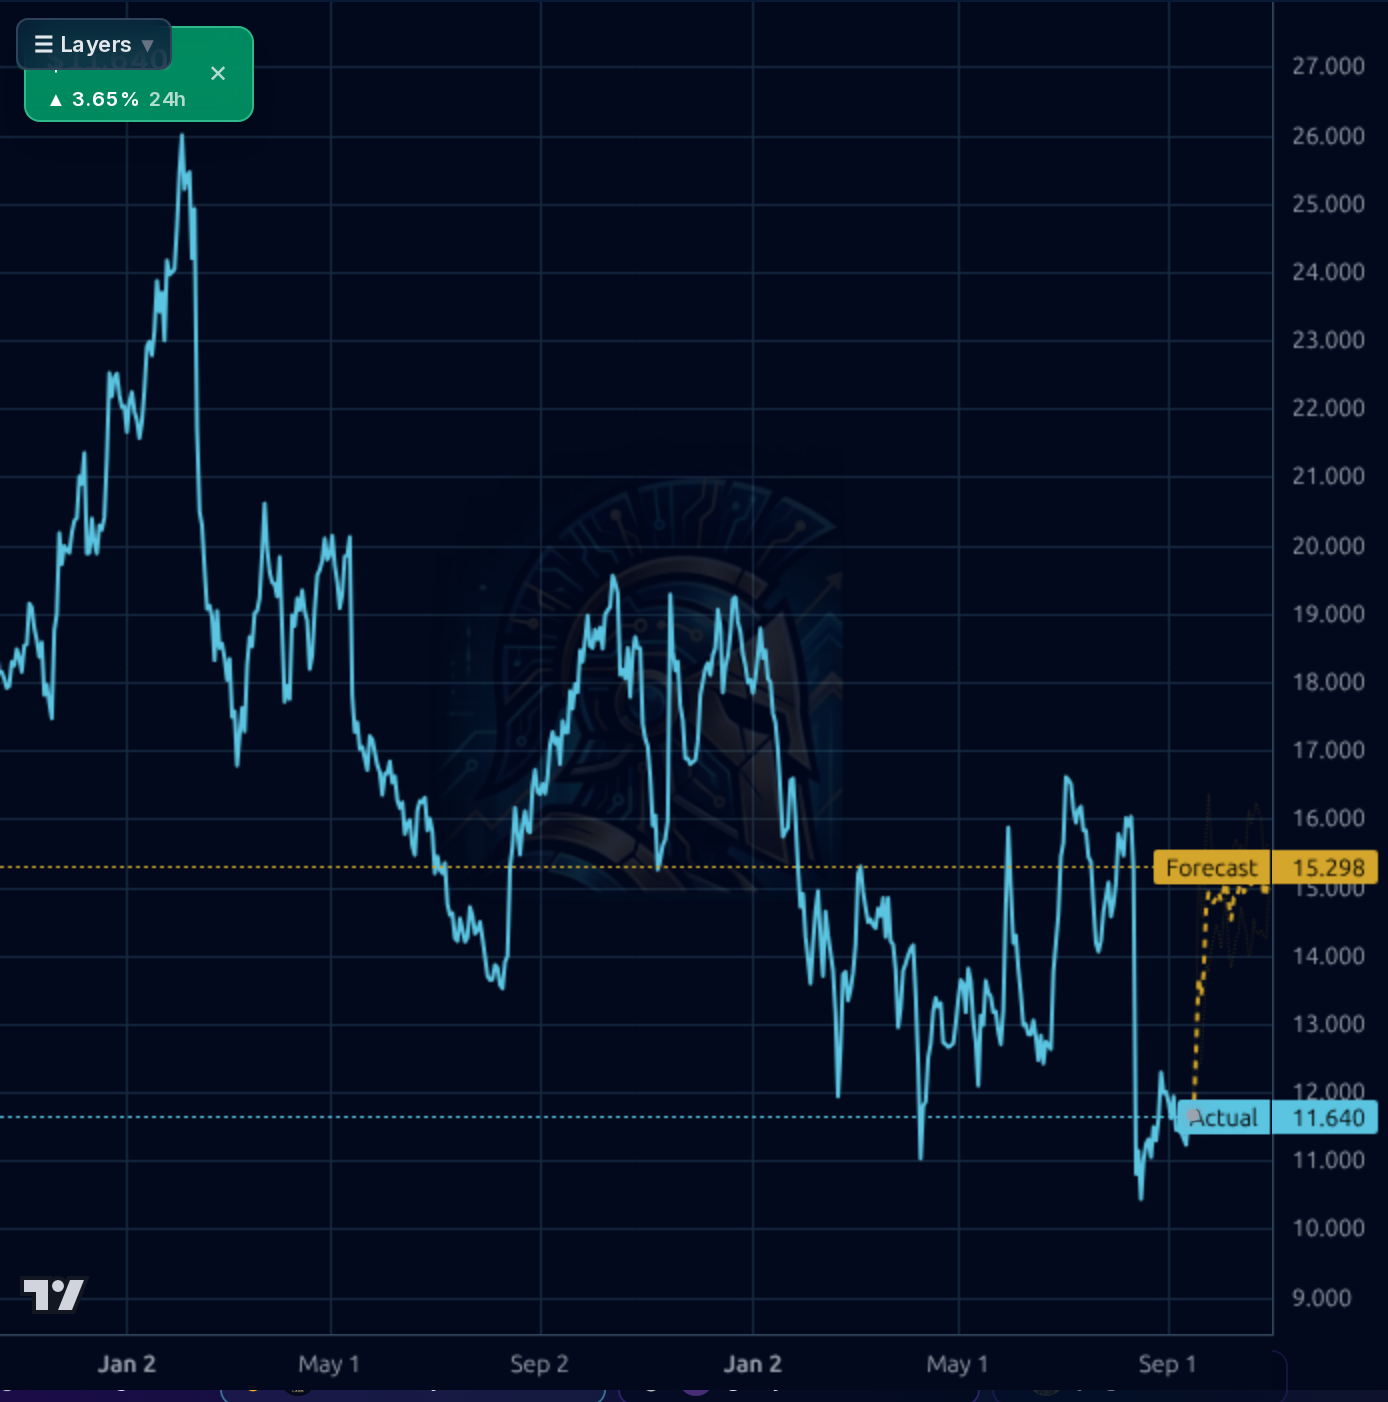
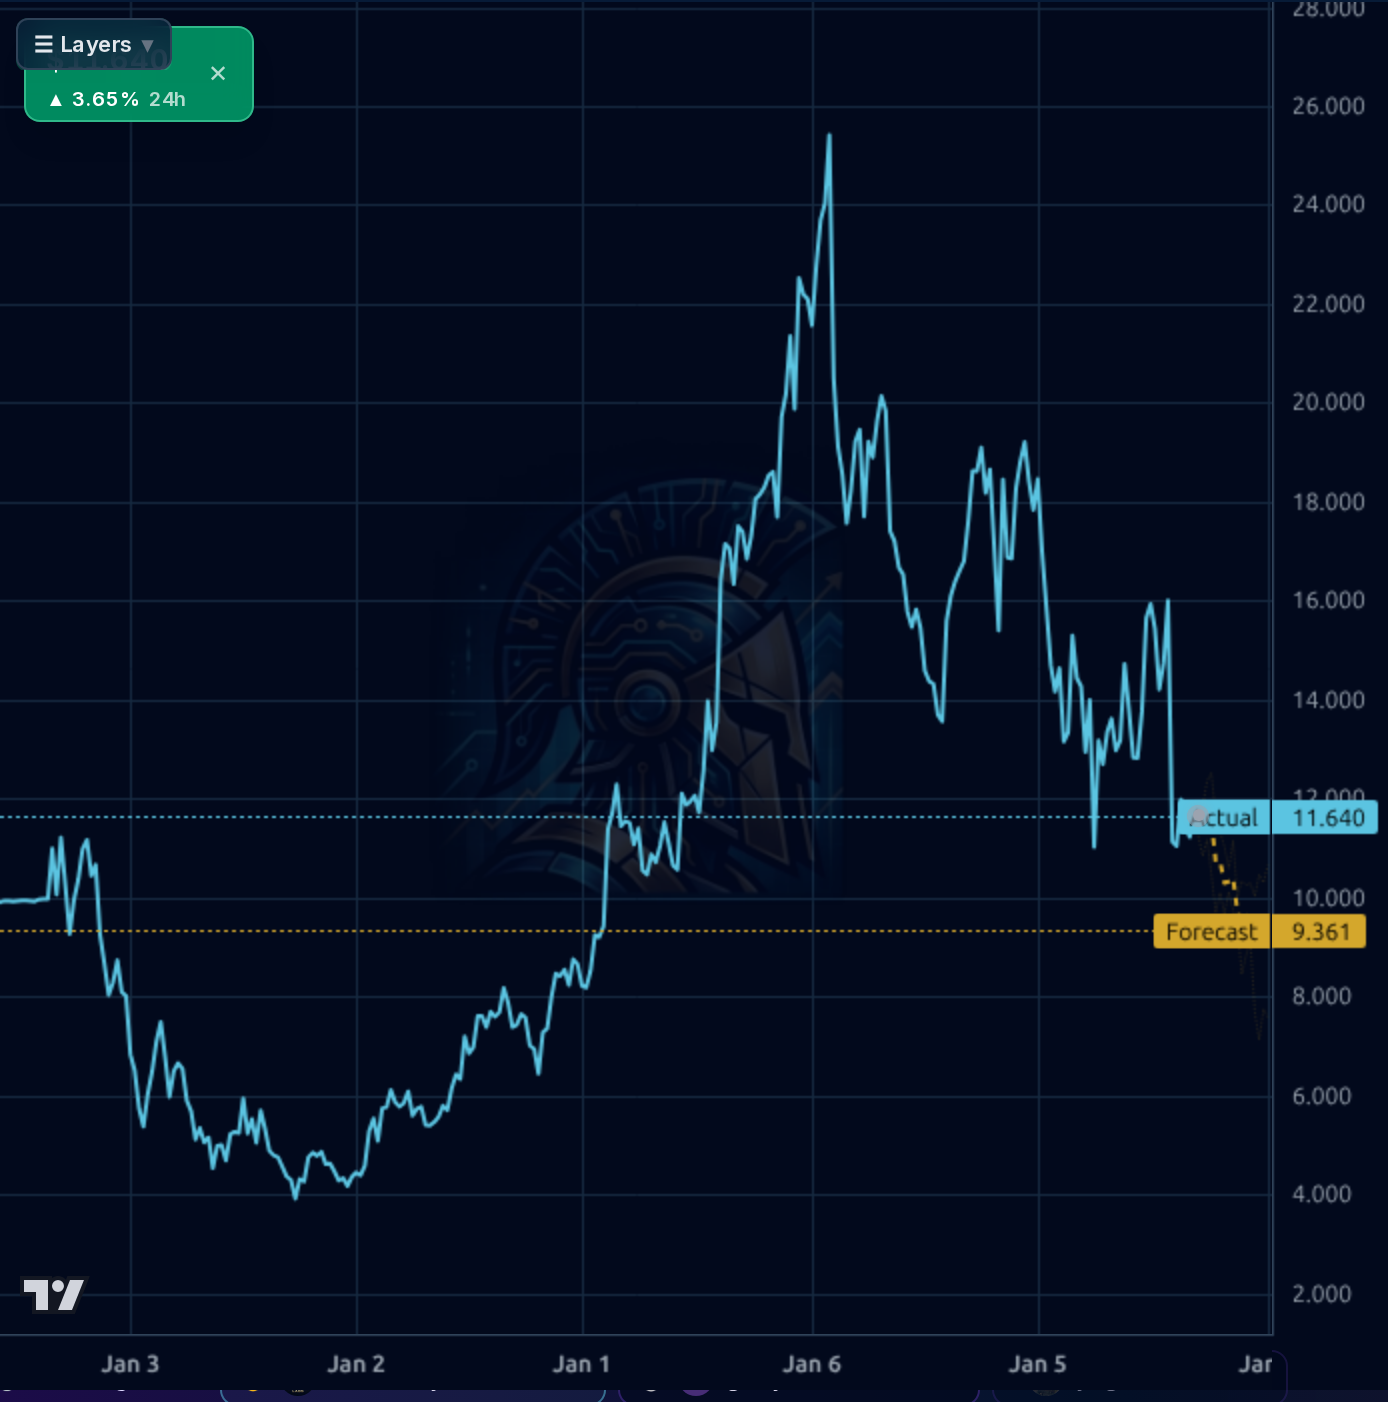
1-4 weeks: HOLD/light accumulate only on defined-risk basis. Do not chase the current bounce toward $12.50 gap fill — model's near-term bullish forecast has failed to print on weekly horizon historically. Preferred entry zone $10.30-11.00 (retest of August low) with stop below $9.58. If already long, trim into $12.50-13.00 into Nov 11 — earnings risk is asymmetric to the downside given the recent guide cut and margin trajectory. Position size small (<1% portfolio) given broken chart and 57-day runway to a binary event.
1-6 months: ACCUMULATE with patience. The setup is a classic 'balance sheet floor vs. broken momentum' — $442M cash and $125M FCF cushion downside meaningfully at ~$10, but multiple re-rating requires Nov 11 to show operating margin stabilization (need to see 8-10%+ recovery, not the 5.3% print) and no second guide cut. Base case: range-bound $10-14 with sentiment following each Ramji strategic update; expected return -15% to +25%. What changes the thesis: (bull) margin recovery + buyback announcement + Ramji product-led roadmap → $15-16 reachable; (bear) second guide cut + government sales cycles further elongate → retest $9.58 and potentially $8.
1-3 years: Terminal thesis is that Cellebrite is a durable digital forensics category leader (60,000+ agencies, 150 countries) with structural tailwinds from mobile-device proliferation, encrypted evidence workflows, and AI-driven investigative platforms (Genesis, Corellium). U.S. redomicile, if executed, removes an institutional-eligibility discount and expands the buyer base. Multi-year drivers: ARR compounding at mid-teens+, Guardian/Genesis moving beyond core UFED extraction into evidence management SaaS, and government IT modernization. Biggest structural risk is reputational/regulatory — lawful access is a politically contested space (Bangladesh RAB history), and any material customer restriction or human-rights-driven divestment pressure could permanently compress the multiple. Secondary risk: encryption arms race erodes technical moat if Corellium/Labs innovation stalls.
Top-line remains healthy: TTM revenue $514M (+17.8% Y/Y), Q2'26 revenue $131.1M (+15.8% Q/Q pace), subscription-led with 117% NRR and ARR $493M (+21% in Q1'26). Gross margin held at 80.8% in Q2'26, confirming SaaS-quality unit economics at the top of the P&L. But the operating line has cratered — operating margin fell from 16.2% (Q4'25) → 7.1% (Q1'26) → 5.3% (Q2'26), and net margin from 16.5% → 4.9% over the same span. Free cash flow followed: from $83M in Q4'25 to just $6M in Q2'26. Balance sheet is unambiguously strong: $442M cash vs. $23M debt, current ratio 1.6, debt/equity 0.04, and $125M TTM FCF supports optionality (buybacks, tuck-ins). Capital allocation is passive — no dividend, no meaningful buyback response yet to a 35% drawdown. What's working: gross margin, ARR growth, NRR, cash generation over TTM. What's broken: operating leverage, cost discipline, and management credibility after a guide cut and CEO/CFO insider selling ($4.7M in 90d).
Trend is decisively broken across all timeframes. Weekly chart shows a topping structure from Jan'25 highs near $26 down to $10.30 August low — a lower-high, lower-low sequence. Daily chart confirms the loss of the $14-16 shelf that held for months, with the Aug'26 breakdown printing to $10.30 before a weak reflex bounce to current $11.23. Hourly shows a modest recovery attempt from the August capitulation low, but price is still below the descending 50DMA (-14.7% distance) and 200DMA (-19.8%). RSI 43.6 is neutral-weak. The model forecast bands are bullish across intraday (bullish_prob 1.0) but the weekly forecast has 0% realized directional accuracy vs 50% naive baseline — heavily discount the bounce narrative. Key levels: resistance $12.50 (gap fill), then $13.50-14.00 shelf, then $15.00-16.00 broken support. Downside pivots: $11.00, $10.30 (Aug low), $9.58 (52w low). Short float 6.7% is elevated but not extreme.
The dominant signal is the Q2'26 miss and guidance cut (revenue trimmed, EPS $0.02 vs $0.06 est., a 66% miss) that drove the ~30% breakdown, followed by two sell-side PT cuts in mid-August ($21.29 → $19.43 → $16.86). Layered on top: CEO transition to Shiven Ramji (product-led growth mandate), CTO Chris Wade elevated to lead Cellebrite Labs, and a Sep 14 authorization to pursue U.S. redomicile. Product/procurement wins are real but incremental — Guardian achieved IRAP PROTECTED (Australian federal), CFSI achieved CMMC Level 2 (U.S. DoD). Sell-side is engaged (Craig-Hallum, DA Davidson calls, September investor events). Signal: margin trajectory and guide credibility dominate everything else — Nov 11 is the true catalyst. Noise: redomicile is a slow-burn optionality item (shareholder/regulatory approval required, could easily be a 'sell the news' event), and IRAP/CMMC are marginal revenue impact near-term. Insider selling by outgoing CEO ($2.1M + $286k) is contextually explainable but pattern-wise unhelpful — clusters of executive selling on this name have preceded further downside, not marked bottoms.
- U.S. redomicile authorized Sep 14, 2026 — potential removal of Israel-domicile discount and expansion of eligible institutional buyer base (pending shareholder/regulatory approval)
- Cellebrite Guardian achieved IRAP PROTECTED certification — opens Australian federal agency procurement
- CFSI achieved CMMC Level 2 accreditation — expands U.S. DoD/federal procurement eligibility
- New CEO Shiven Ramji mandated to drive product-led growth and diversify beyond lumpy government deals
- Cellebrite Genesis (agentic AI investigations) and Corellium (mobile vulnerability research/pen-testing) as differentiated enterprise wedges beyond core UFED extraction
- ARR growing 21% Y/Y to $493M in Q1'26 with 117% net revenue retention — subscription mix continues to expand
- Operating margin collapse from 16.2% (Q4'25) to 5.3% (Q2'26) — if not stabilized on Nov 11, SaaS-quality premium fully unwinds
- Second guidance cut on Nov 11 would likely retest $9.58 52-week low and break to new lows
- $4.7M insider selling in 90d by outgoing CEO/CFO — historical pattern has preceded further downside on this name
- Sell-side PT cuts in August (two cuts totaling ~21% reduction) reflect capitulation dynamic still unfolding
- ~75% government revenue concentration exposes company to procurement lumpiness and lawful-access regulatory shifts
- Redomicile subject to shareholder/regulatory approval — timing uncertain and potential 'sell the news' event
- Reputational/regulatory tail risk from human-rights-linked deployments (Bangladesh RAB history)
- Free cash flow collapsed from $83M in Q4'25 to $6M in Q2'26 — TTM FCF durability at $125M is not guaranteed
- Prior bullish calls on this name have systematically overshot — base targets averaged +33% above realized price
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord