COUR — AI Stock Forecast & Price Targets
Published 9/11/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live COUR price forecast →
Coursera is a broken-momentum name trading at $5.30, near 52-week lows after a sharp post-Q2 selloff despite reported +59.6% YoY revenue growth and raised FY26 guidance. The setup pairs a real AI catalyst (Project Helix, 1H27 enterprise launch) and heavy institutional accumulation (Inst. Own 60.6%→82.7%) against widening losses, deteriorating price action, and a forecast model that is unreliable at weekly horizons — warranting a measured accumulation rather than an aggressive buy.
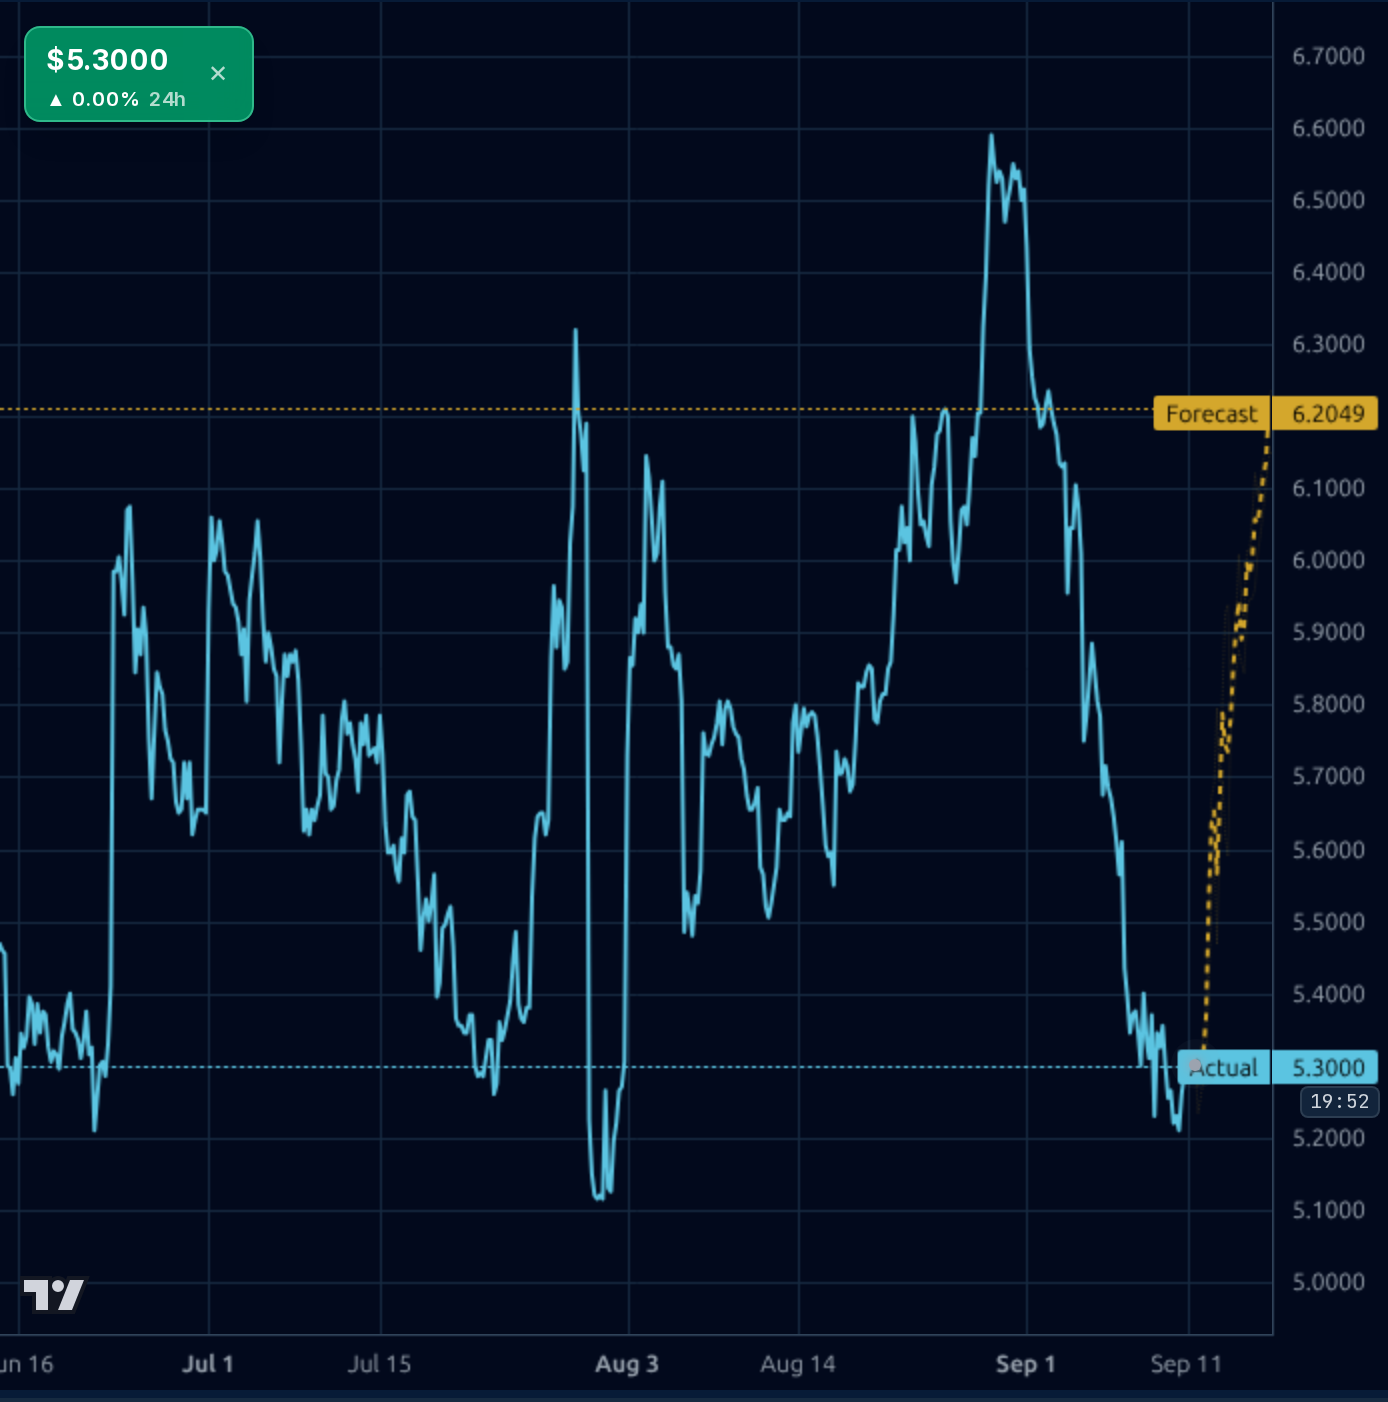
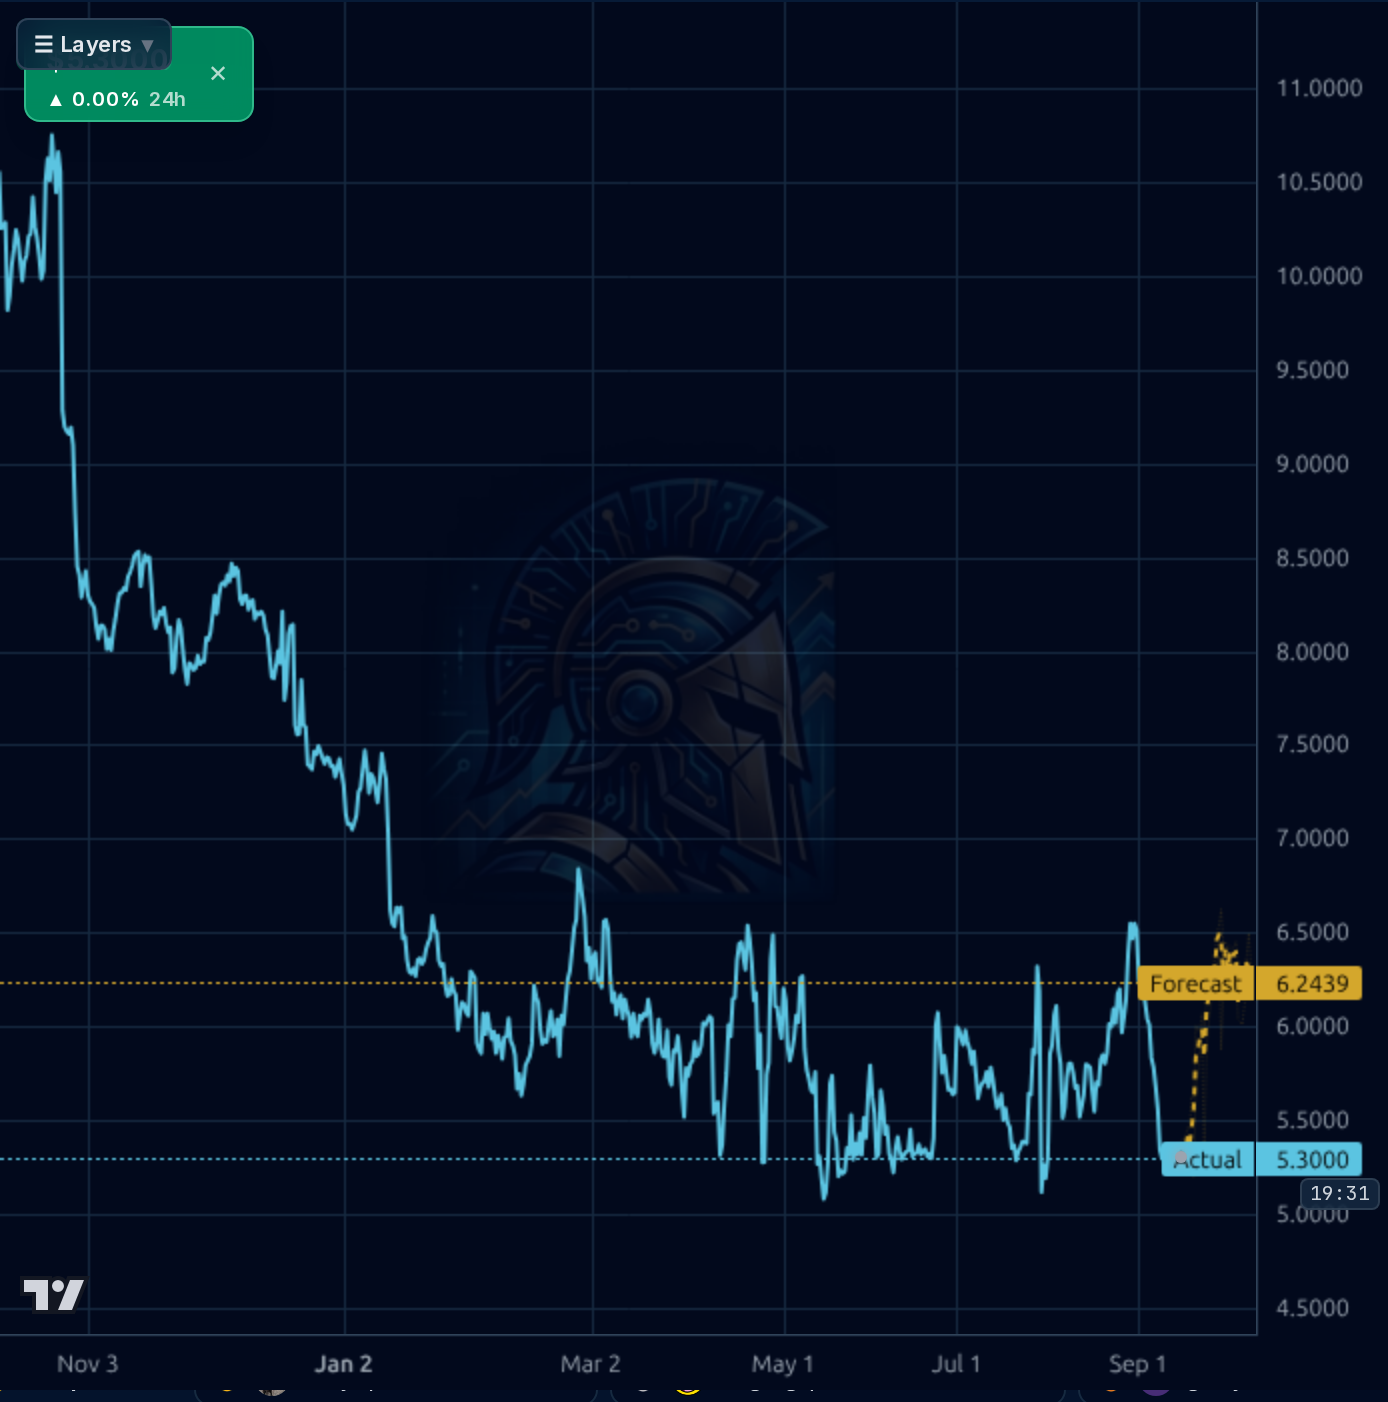
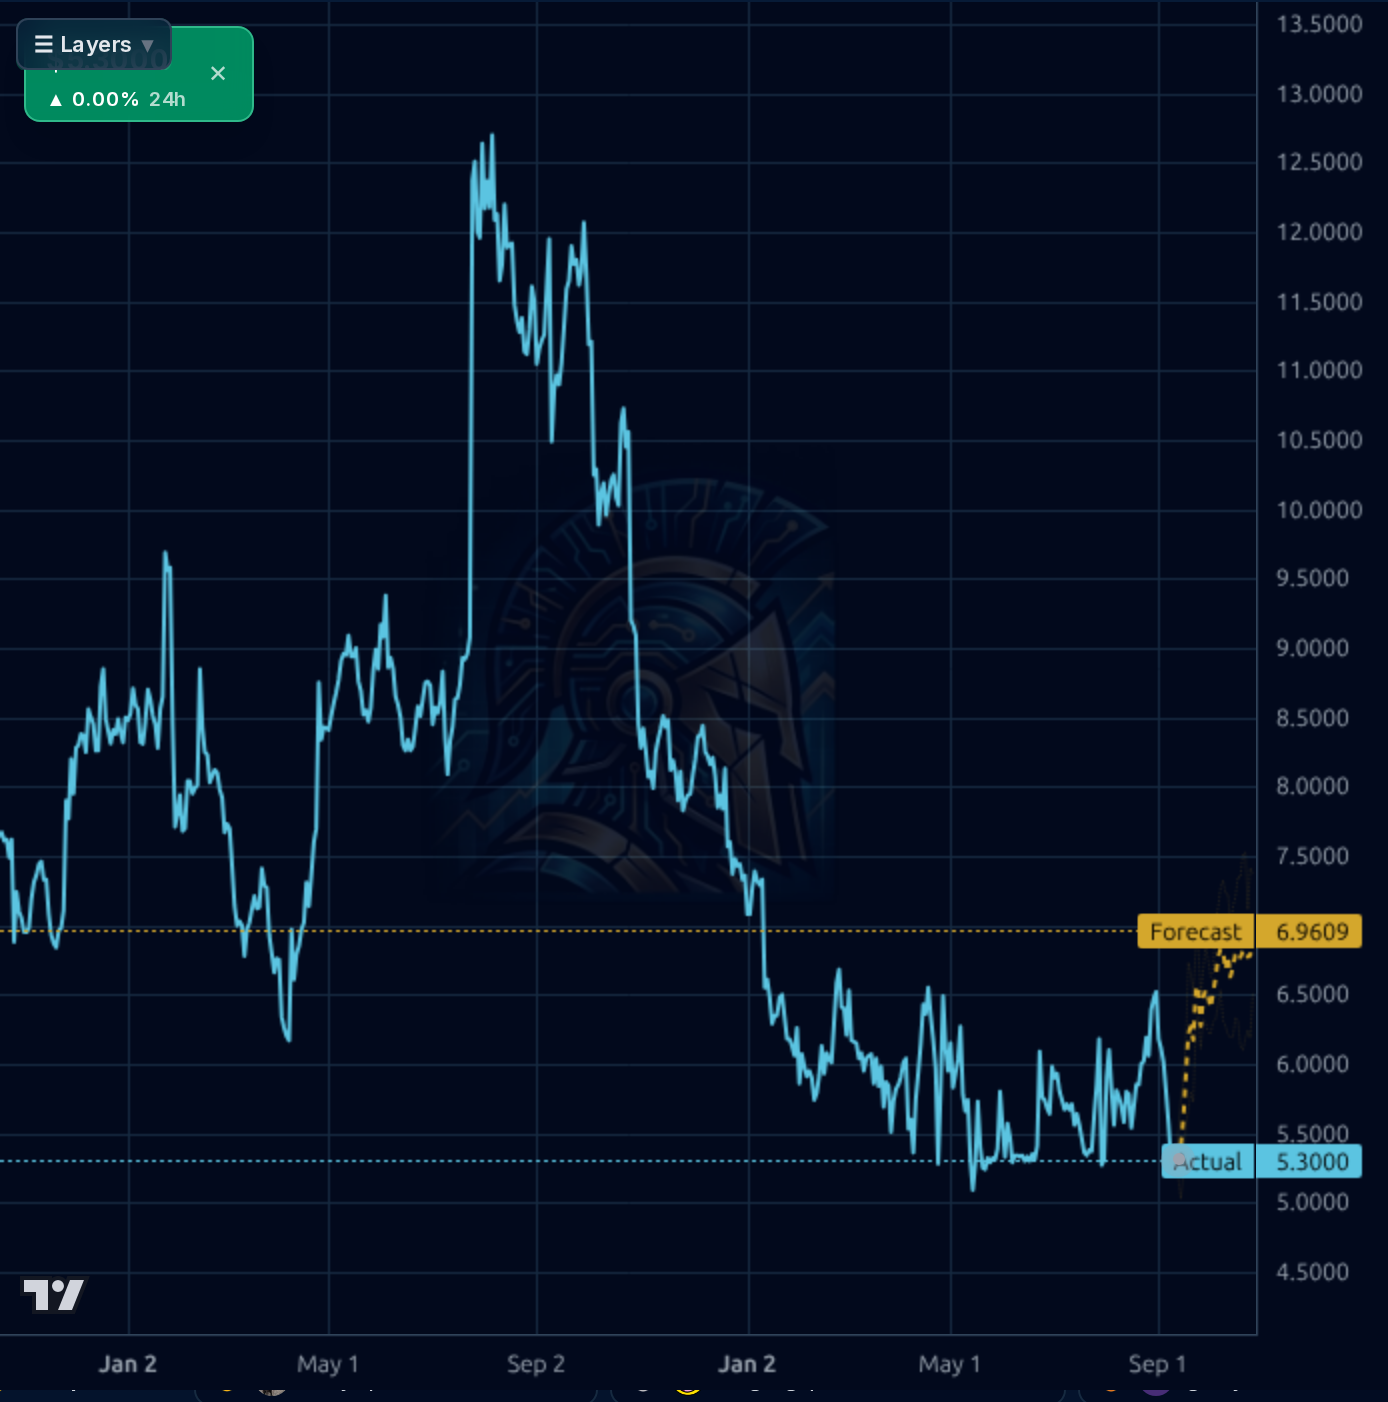
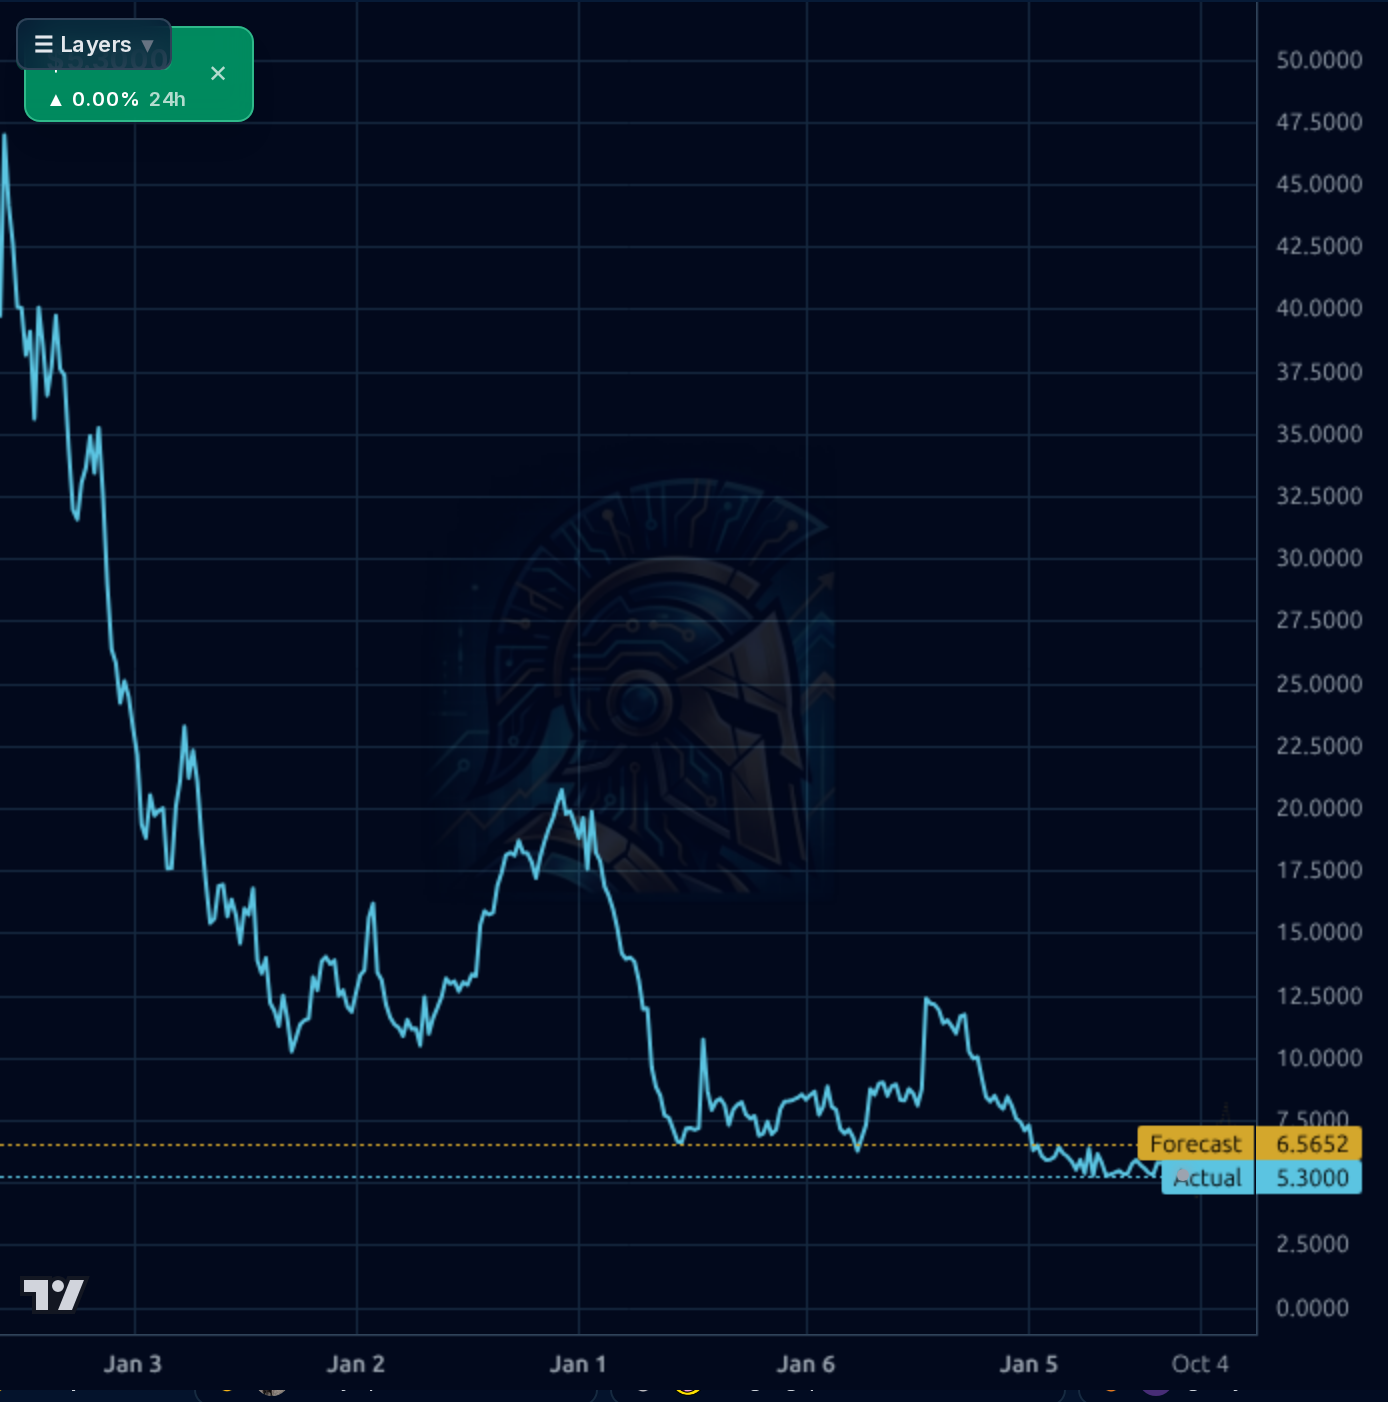
1–4 weeks: The tape is in a confirmed downtrend making fresh 52-week lows; do not chase the model's +25% snap-back forecast given weekly directional accuracy trails the naive baseline. Prefer a scaled accumulation approach: initial 1/3 position at/near $5.20–$5.30, add 1/3 on a reclaim of $5.60 (gap-fill and back above short-term structure), reserve 1/3 for either a flush to $4.70–$4.90 (below 52-wk low) or a confirmed close above $5.80. Hard invalidation: sustained close below $4.80 with volume. Upside trim zone: $6.20–$6.50 (forecast band top / prior resistance).
1–6 months: Thesis is a re-rating of a cheap (EV/Sales 0.45, fwd P/E 6.4) growth-plus-turnaround name as Q3 earnings (Oct 29) either confirms the raised FY26 guide or exposes the reason for the August selloff. Expected return range $5.50–$7.50 (base) representing +5% to +40%. Positive catalysts: Q3 print in line with raised guide, Project Helix pre-launch customer wins, continued institutional accumulation. Changes my mind: Q3 miss or lowered guide, evidence that the 59.6% YoY growth is entirely inorganic while organic churn accelerates, or CEO transition risk materializing.
1–3 years: If management delivers the ~14% EBITDA-margin target and Udemy synergies plus Project Helix drive organic re-acceleration, this is a $9–$12 stock reflecting a normalized ~1.5–2x EV/Sales on $1.4–1.6B revenue with genuine profitability. The structural bull case is that AI-native skills validation becomes the enterprise standard for workforce upskilling, and Coursera's dual consumer/enterprise moat plus credential partnerships compound. Biggest structural risk: AI itself compresses the value of packaged online courses (LLMs can teach adaptively for near-zero marginal cost), and hyperscalers or LinkedIn Learning capture the enterprise credentialing layer, leaving Coursera stranded as a mid-tier content aggregator.
Top-line is the bright spot: Q2 CY26 revenue of $298.6M represents +59.6% YoY (likely inclusive of the Udemy transaction referenced in news), and management raised FY26 revenue guidance to $1.22–1.245B with a ~14% EBITDA-margin target. However, GAAP profitability is deteriorating — Q2 net loss widened to -$80.4M (net margin -26.9%) versus -$20.5M in Q1, and operating margin remains negative at -1.6% on a TTM basis with ROE -15.2%. Gross margin held at 58.1% (healthy for the model). The balance sheet is a genuine cushion: $871.7M cash, negligible debt ($9.7M), book value $4.25/sh, and enterprise value of only ~$401M against $885M in TTM sales (EV/Sales 0.45). Free cash flow is choppy — TTM FCF prints as $366M in one field but quarterly cash flow was -$27.5M in Q2 after +$8.8M/+$0.6M/+$28.7M prior — suggesting the trailing number is inflated by working-capital or M&A-related items and true operating FCF is closer to breakeven. Forward P/E of 6.35 and PEG 0.22 are optically cheap if the guidance holds; the fundamental question is whether the Udemy-integrated business can convert its scale to positive GAAP earnings before the cash pile is spent on integration costs.
The tape is decisively broken. On the 1h chart, price collapsed from ~$6.60 in early September to $5.30 — a ~20% drawdown in roughly a week, printing a fresh 52-week low ($5.00). Daily chart shows a two-year downtrend from ~$12 with the recent September rally to $6.50 rejected and fully retraced. Weekly chart shows -86% over 5 years and -50% over the past year. Price sits -11.6% below SMA20, -9.4% below SMA50, and -15.3% below SMA200 — all moving averages sloping negative and stacked bearishly. RSI(14) at 35.9 is weak but not yet washed-out; ATR $0.28 (~5% of price) confirms elevated volatility. The AI forecast band projects $6.20–$6.96 (1d–1wk), a +17–31% snap-back, but the 1wk model has been beaten by naive baseline (50% vs 83%) and should be heavily discounted; the 1d model is only marginally better than random. Support is the $5.00 52-week low, then air below; resistance is the $5.60–$5.80 gap-down zone, then $6.50 prior high. This is a knife-catch setup, not a confirmed breakout.
Signal: Coursera unveiled Project Helix on Sep 9 — an AI-native skills platform tying learning to verified business outcomes — but enterprise launch is not until 1H27, making it a narrative catalyst rather than a near-term earnings driver. The Q2 print (Jul 29) beat on revenue (+59.6% YoY to $298.6M) and raised full-year guidance to $1.22–1.245B with ~14% EBITDA margins, yet the stock has fallen ~20% since, indicating the market is discounting either integration risk from the Udemy deal, guidance quality, or organic-growth deceleration (a StockStory piece explicitly cited 'weak organic growth and integration costs' as key risks). Noise/mixed: Retail sentiment is 78% bullish but includes credible bearish commentary questioning CEO Greg Hart's track record (prior role at Compass during its bottom). A lone insider sale ($52k by the General Counsel) is small and non-diagnostic. The materially bullish tell buried in the fundamental-change signals is institutional ownership jumping from 50.6% to 82.7% over ~45 days — that scale of accumulation into a selloff is unusual and worth respecting even as price falls.
- Project Helix AI-native skills platform — enterprise launch scheduled 1H27, first material catalyst to monetize the AI narrative
- Udemy integration synergies driving the Q2 revenue jump to +59.6% YoY — synergy realization and cross-sell into enterprise base
- FY26 revenue guidance raised to $1.22–1.245B with ~14% EBITDA-margin target — first credible path to structural profitability
- Institutional ownership expansion from 50.6% to 82.7% over ~45 days signals sponsorship building into the selloff
- Coursera Plus consumer subscription and degree/credential mix shift toward higher-ARPU enterprise contracts
- Widening GAAP losses — Q2 net loss of -$80.4M (net margin -26.9%) up sharply from Q1, driven by integration/deal costs
- Broken technical structure — fresh 52-week low at $5.00, all SMAs sloping down, -50% YoY performance
- Unresolved 'August 5' selloff catalyst — market clearly saw something negative in guidance quality or organic-growth commentary that headlines don't fully explain
- Project Helix catalyst is 1H27 — too distant to support near-term earnings visibility; risk of vaporware execution slippage
- CEO Greg Hart's prior track record questioned by informed retail commentary — governance/leadership overhang
- Secular AI disruption to packaged online-course business model could compress terminal margins
- Model 1-week forecast underperforms naive baseline (50% vs 83%) — the +25% mid-forecast should be heavily discounted
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord