DVN — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live DVN price forecast →
DVN is trading near its 52-week high ($51.29 vs $52.71) after a powerful ~40% YTD rally, supported by the just-closed Coterra merger, a CEO open-market buy on 9/14, and analyst PT hikes (Raymond James to $67). Valuation remains reasonable (fwd P/E ~10, PEG 0.76) but momentum is extended (RSI 69, +12% MoM) into a risk-off macro tape, so the setup favors accumulating on pullbacks rather than chasing.
Do not chase at $51+ into a risk-off tape with RSI 69 and price kissing the 52-wk high. Preferred plan: wait for a pullback to the $49.50-48.00 breakout retest to add; a deeper flush into $46-47 (roughly the SMA20 zone) would be the higher-conviction add. Invalidation for near-term long bias is a decisive daily close below $45.50 on volume, which would reopen the model's downside scenario. If already long, trim 15-25% into $52.50-53.50 to bank the parabolic move.
Base case: DVN grinds to $56-60 over the next 3-6 months as post-merger synergies show up in Q3 and Q4 reports and the market re-rates the combined entity's FCF; this aligns with the $60.90 Street target and Raymond James' $67. The 11/4 earnings print is the key catalyst — need to see margin stabilization and confirmation that Q2's negative FCF was deal-related, not structural. Bull case activates if WTI holds >$65 and synergies beat guidance. Change-my-mind: sustained crude below $60, or Q3 showing continued FCF erosion excluding one-time items.
Multi-year thesis rests on DVN becoming a scaled Permian-plus operator via the Coterra combination, generating durable FCF at mid-cycle oil prices with disciplined capex and a variable/fixed dividend framework. Drivers: Delaware Basin inventory depth, cost synergies, and continued shareholder returns. Biggest structural risk is the commodity cycle itself — a genuine oil bear (secular EV demand hit, OPEC market-share war) would compress margins hard given the now-larger debt load ($11.9B). Debt/equity of 0.28 is manageable but not fortress-level after the deal.
Q2'26 was a step-function quarter reflecting the Coterra consolidation: revenue jumped to $7.42B from $3.81B in Q1, net income surged to $1.911B (net margin 25.8%) and EBITDA nearly doubled QoQ to $3.94B. The balance sheet, however, materially changed — total assets expanded to $70.9B from $32.5B, equity to $41.7B, and total debt rose to $11.74B; working capital is -$1.99B and current ratio only 0.72, so near-term liquidity is tight. TTM operating margin (41%) and ROE (11.5%) are healthy for the industry, and operating cash flow of $8.55B is robust, but Q2 capex of $4.05B swamped OCF and produced -$373M FCF for the quarter — a one-off tied to the deal, but it means the 'free cash flow story' needs to reassert itself in H2. Capital allocation remains shareholder-friendly (2.57% dividend yield, 23% payout, dividend just declared for 9/15 ex-date). Fwd P/E 9.6-10.3, PEG 0.76, EV/EBITDA 7.55, P/B 1.41 all screen cheap versus the growth now baked in.
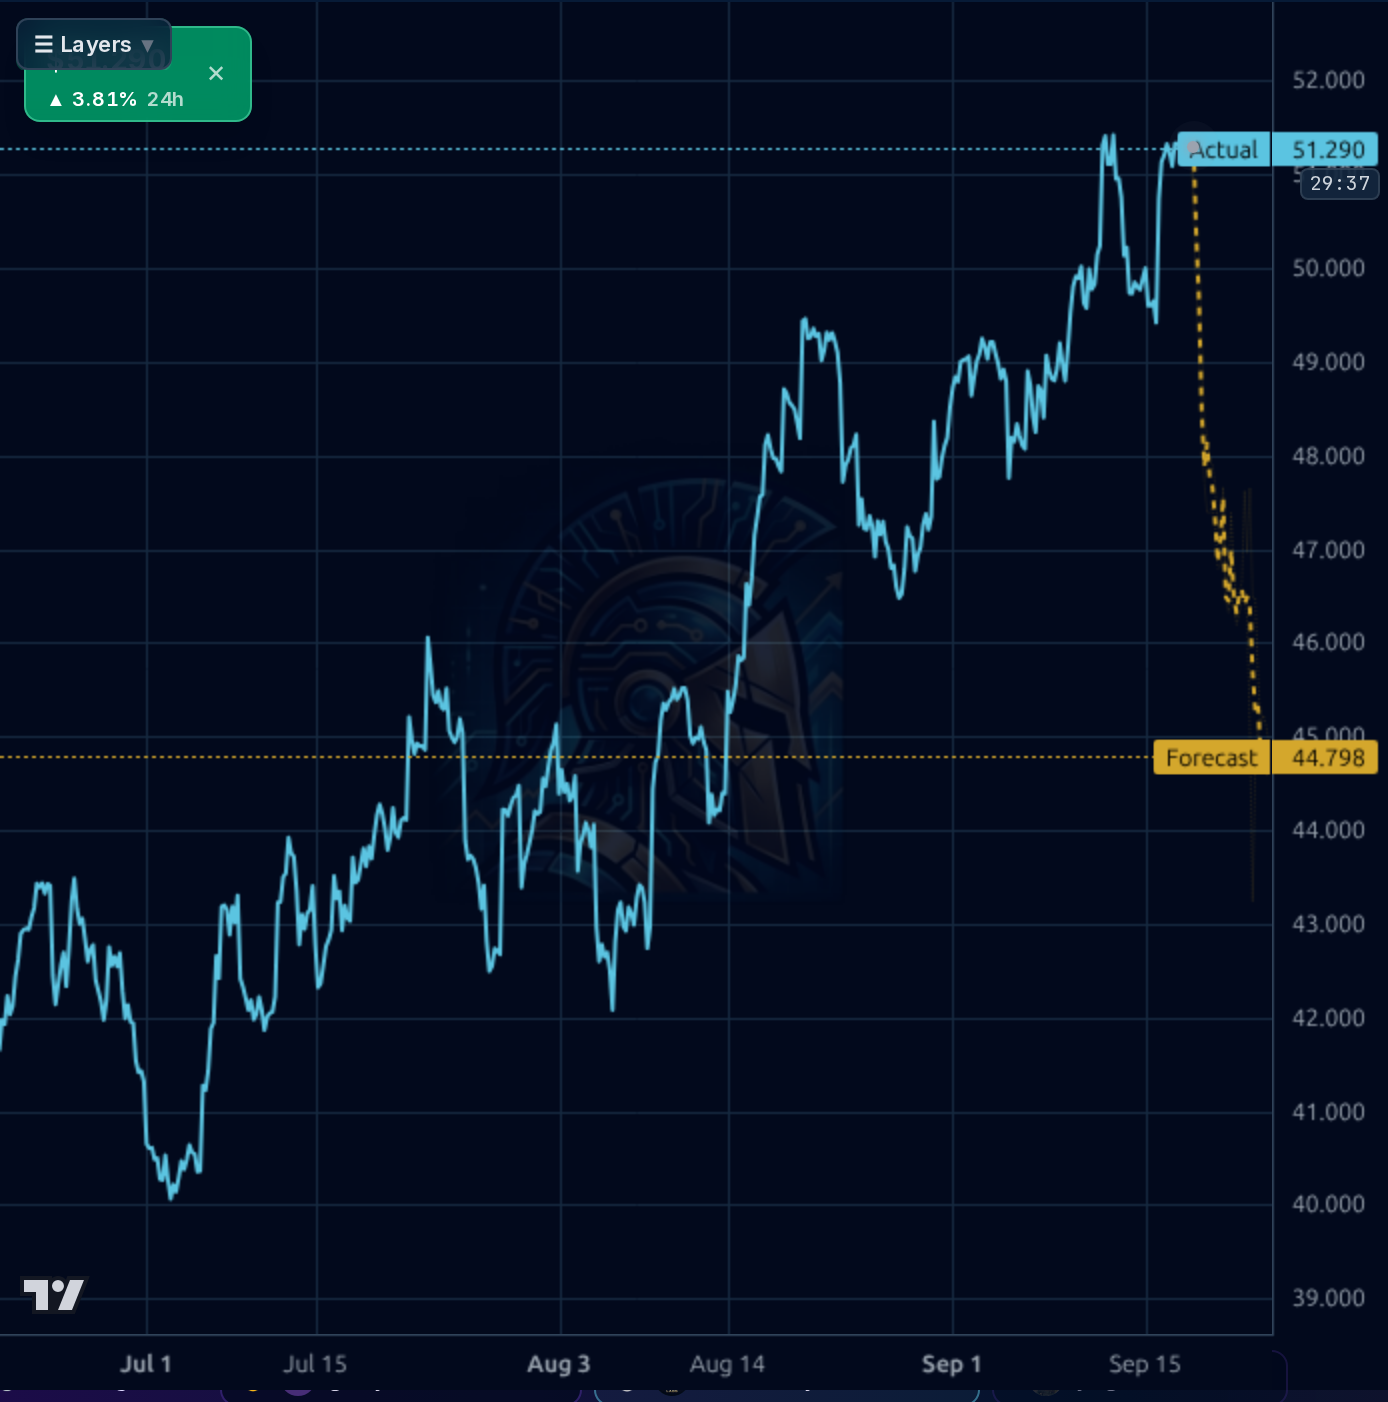
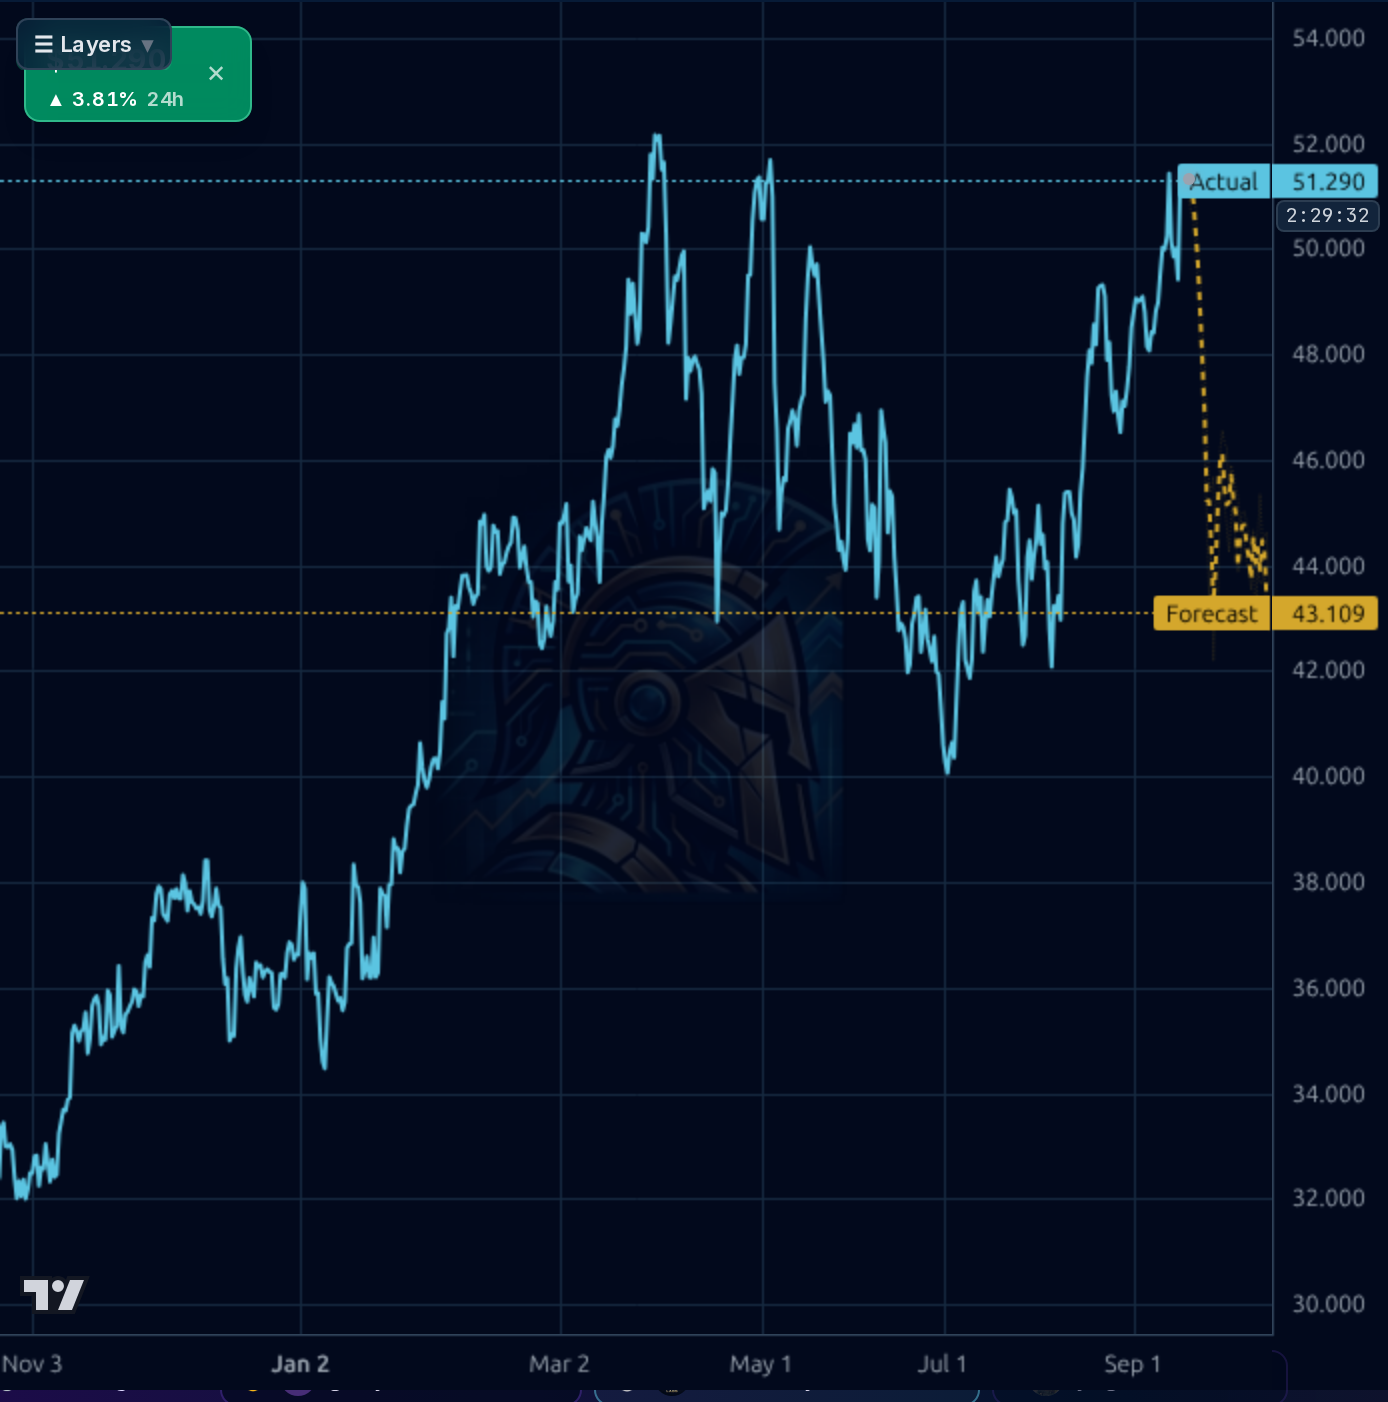
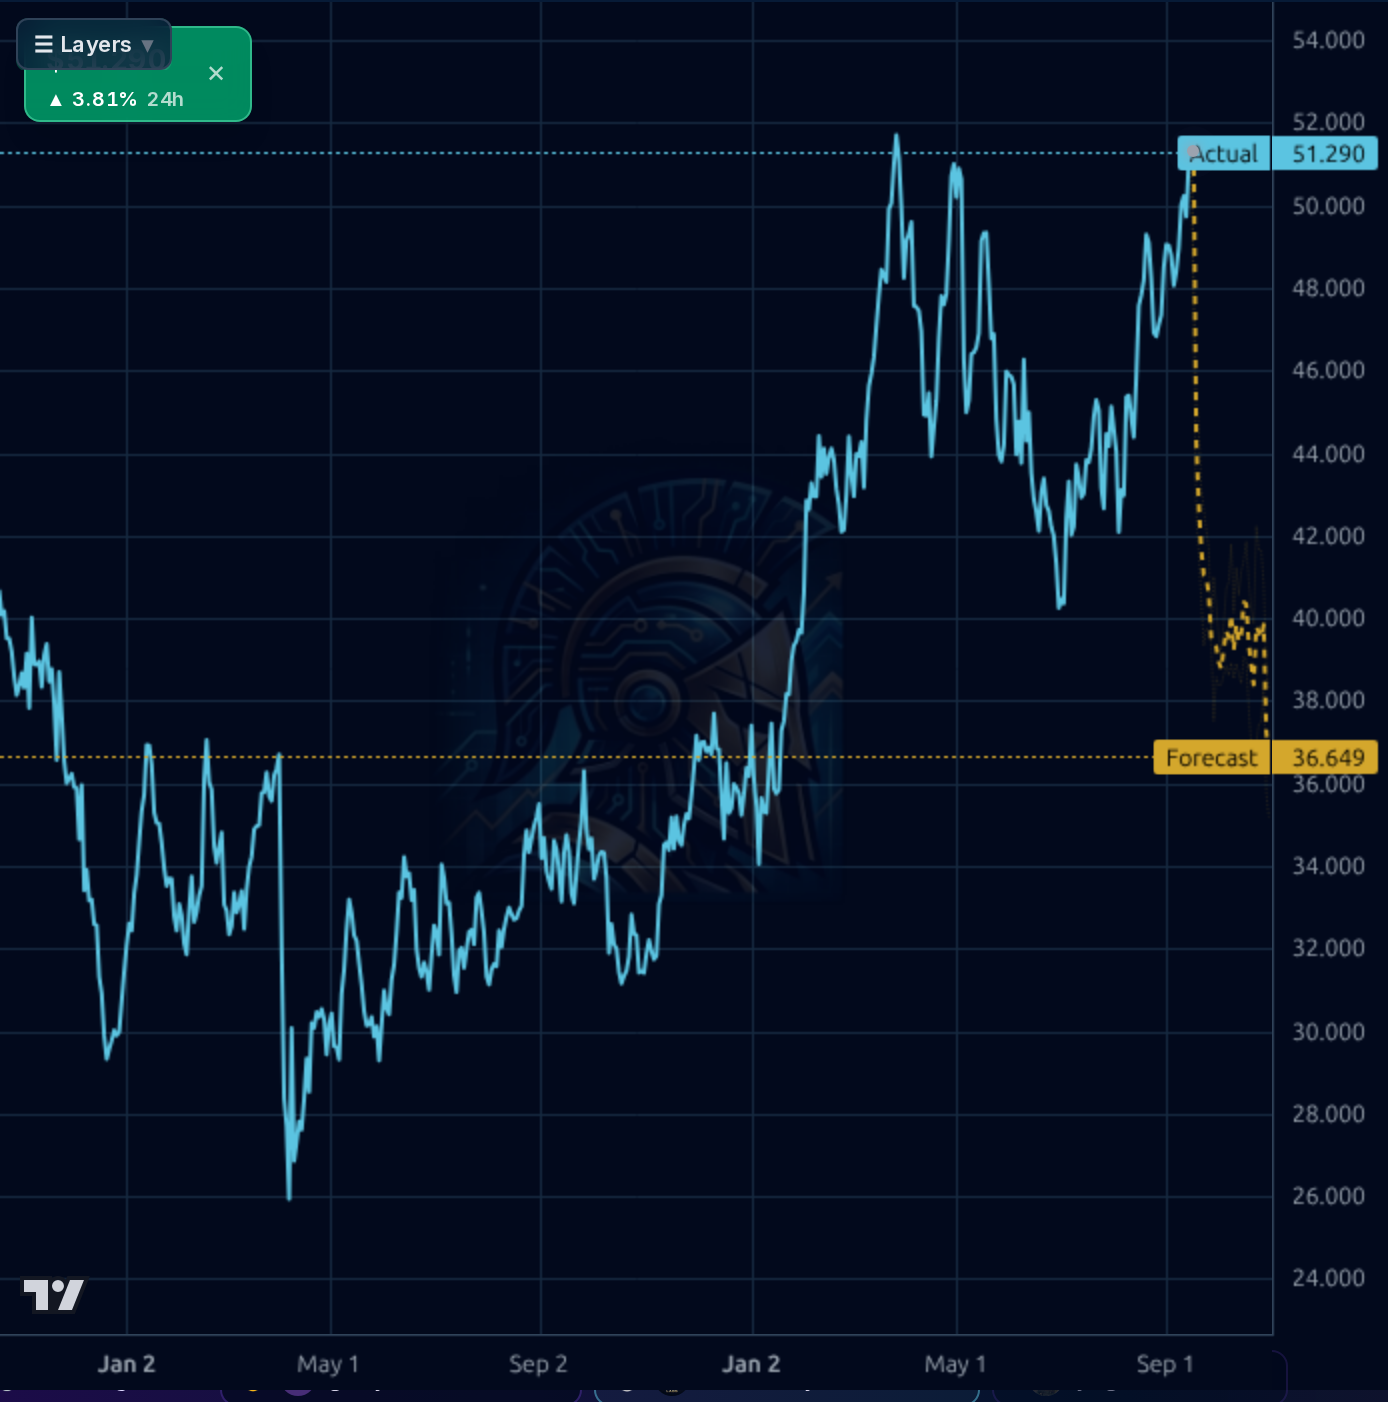
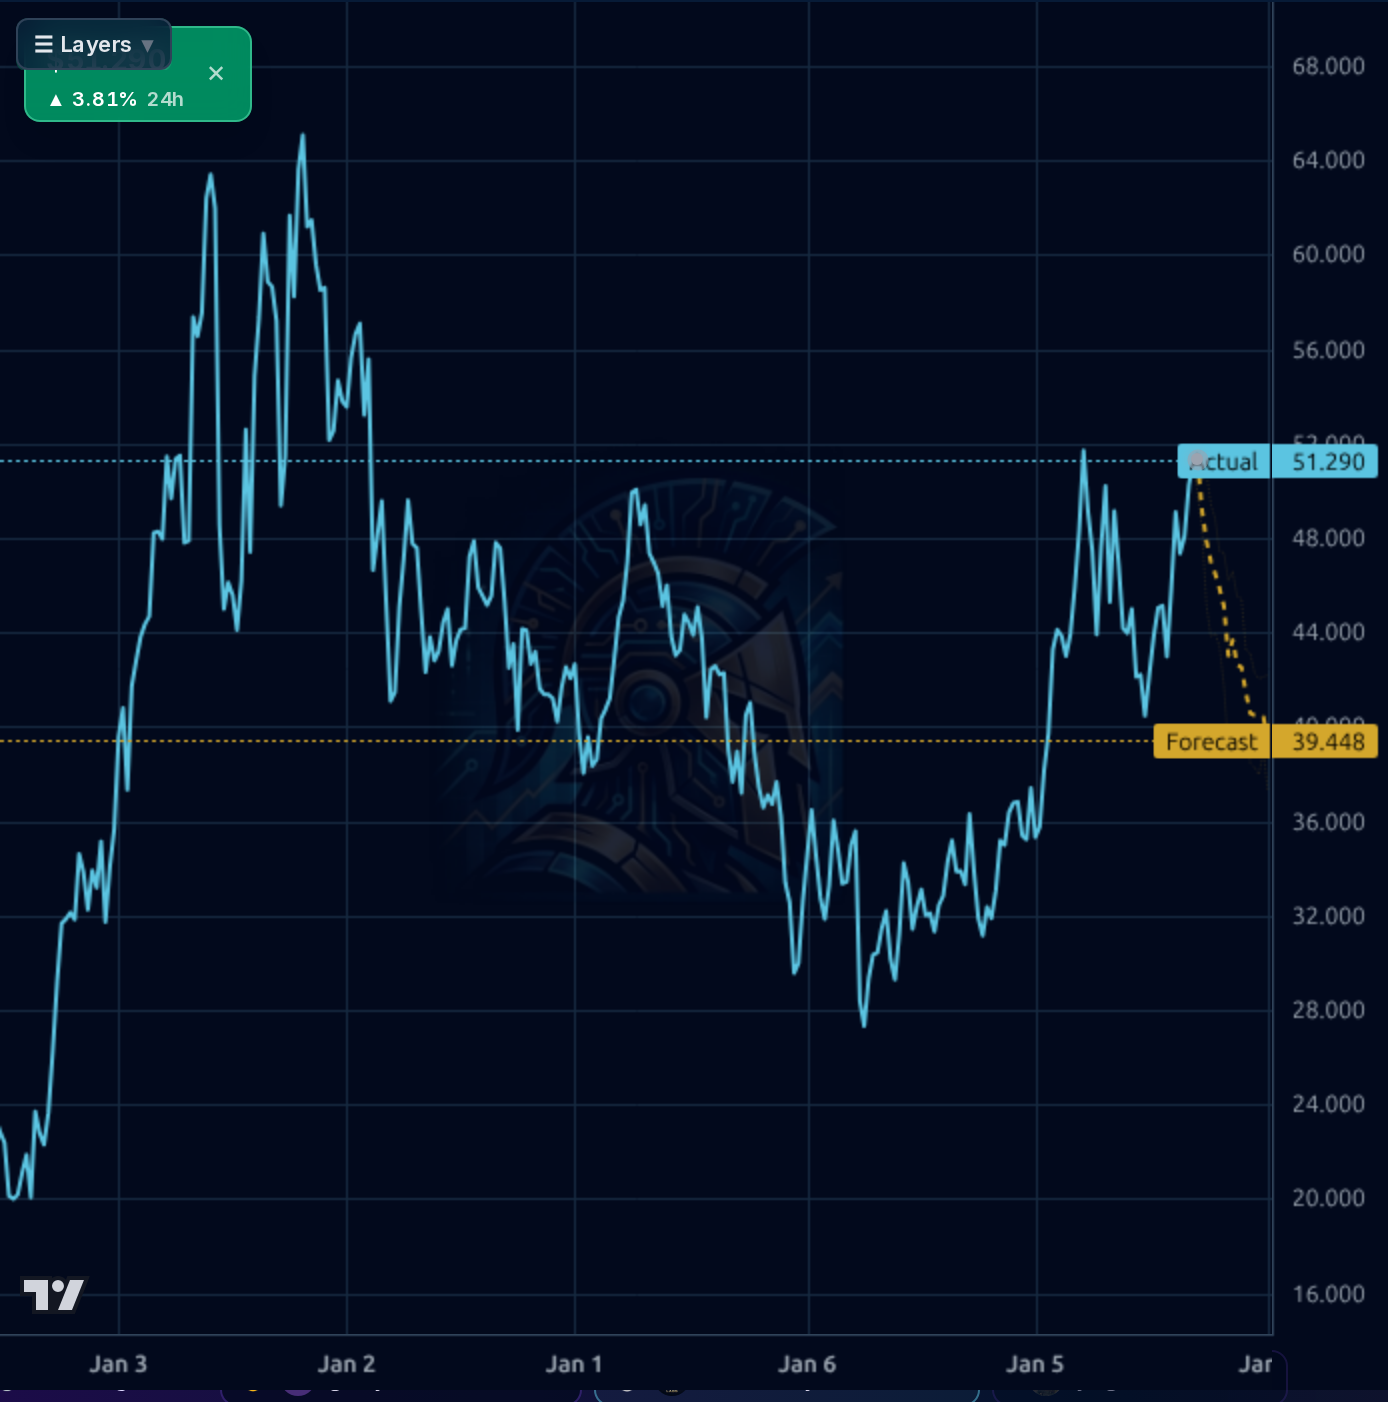
Across all four timeframes price is pressed against the top of the range: 1h chart shows a near-vertical rally from ~$42 in mid-August to $51.29, closing at the highs; the 4h and 1D charts confirm a clean breakout above the March-May prior high near $50-52; the weekly shows price reclaiming resistance that has capped DVN for over a year at ~$51-52. Momentum indicators are stretched — RSI 69, price +5.5% above SMA20, +11.9% above SMA50, +16.8% above SMA200 — classic late-stage impulse. The internal forecast model is uniformly bearish (1h target 44.80, 4h 43.11, 1D 36.65, 1W 39.45) but its own realized directional accuracy has been well below the naive baseline recently (29% vs 71% on 1D, 0% vs 100% on 1W), so those specific downside targets should be heavily discounted. Still, the message that mean-reversion risk is elevated at these levels is consistent with the extended readings. Key support: $49.70 (prior breakout), then $47.50 and $45-46; resistance: $52.71 52-wk high, then open air into the mid-$50s.
The signal-heavy items are the completed Corterra/Coterra merger (mentioned in Stocktwits recap of 3 straight green sessions), Raymond James reiterating Strong Buy and raising PT from $64 to $67, and an SEC 8-K on 8/20 detailing senior executive team changes tied to reorganizing production oversight post-deal. Zacks flagging elevated user interest and the dividend-analysis pieces are largely descriptive/noise. The insider action is the most actionable near-term data point: CEO Clay Gaspar bought ~$200k in the open market on 9/14 while an EVP sold ~$344k the same day — the CEO buy at these highs is a meaningfully bullish tell that outweighs a diversification-style sell by a divisional EVP.
- Realization of Corterra/Coterra merger synergies — Q2'26 already shows 73% QoQ sales growth and 43.8% EPS Q/Q as a first look
- Sales growth estimate revised up materially (2.0% → 18.3%) reflecting the combined entity's run-rate
- Post-deal executive reorganization (8/20 8-K) aligning leadership by basin — should improve operational focus in Delaware, Eagle Ford, Anadarko, Williston, Powder River
- Continued capital returns: $0.32 dividend declared with 9/15 ex-date, 23% payout ratio leaves ample room for buybacks/variable dividends if FCF normalizes
- Institutional ownership rising (multiple L1/L2 upticks: 51%→76% range across signals), suggesting the deal is drawing quality holders
- Q2'26 free cash flow was -$373M as capex hit $4.05B — needs to normalize quickly or the FCF-story bull case weakens
- Current ratio 0.72 and working capital -$1.99B post-merger indicate tight near-term liquidity
- Total debt jumped to $11.74B; debt/equity 0.28 is fine but leaves less cushion in a sharp crude downdraft
- RSI 69, price +16.8% above SMA200, at 52-wk high in a risk-off SPY tape — technical mean-reversion risk is high
- Internal forecast models are uniformly bearish across all timeframes (though their recent accuracy is poor); the directional signal shouldn't be entirely dismissed
- EPS next Y estimate revised down to -0.3% growth — implies flat-to-down earnings even with the deal accretion
- Commodity price sensitivity remains the dominant swing factor; sustained WTI <$60 would compress margins materially
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord