ENOV — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live ENOV price forecast →
Enovis has capitulated to a fresh 52-week low of $18.22 (-5.5% today, RSI 31.7, -26% below 200dSMA), extending a brutal repricing catalyzed by the debt-financed €155M eCential Robotics deal against a stretched balance sheet ($1.37B debt vs $12.6M cash). The operational inflection is genuine (GM 61.6%, positive operating income, ~$186M TTM FCF, 4.9x fwd P/E) and CEO/CAO cluster buying at $18-19 signals conviction near washout, but with no near-term catalyst until Nov 4 earnings and prior 'base' targets running ~19% optimistic vs realized price, this remains a scaled, tactical accumulation — not a rerating.
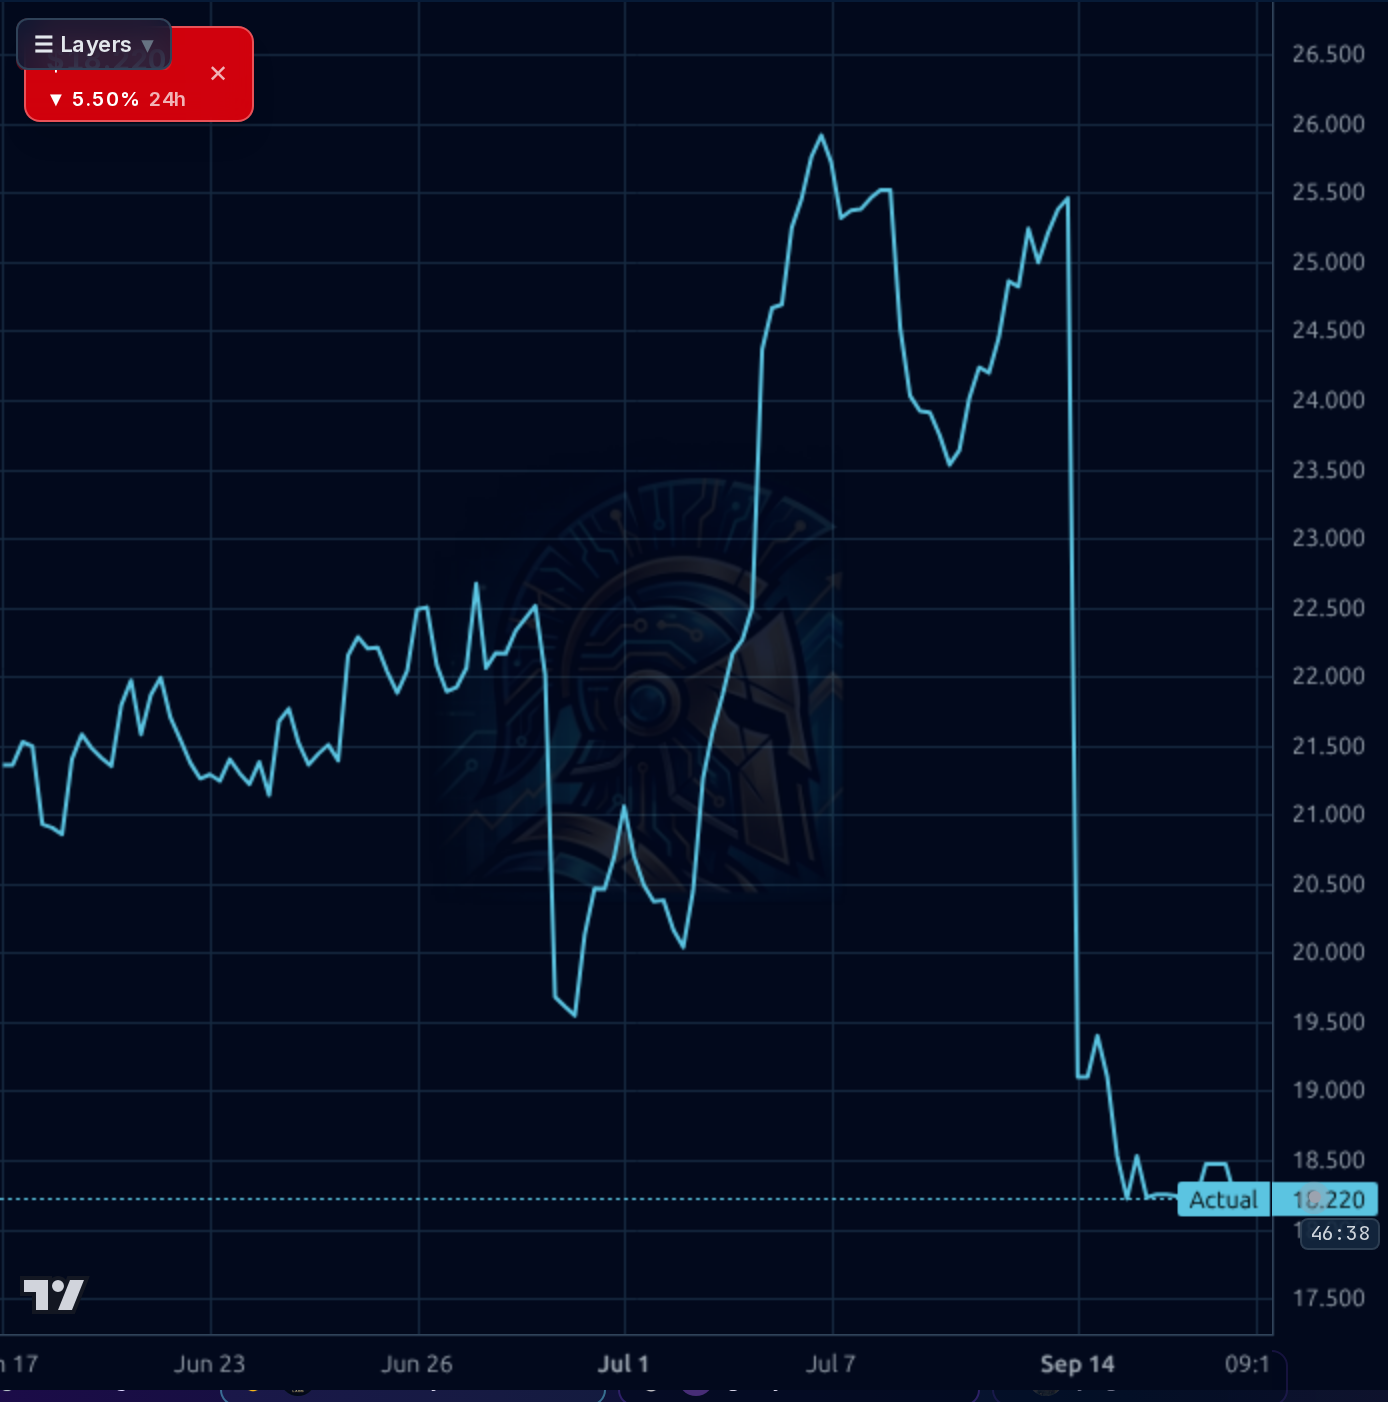
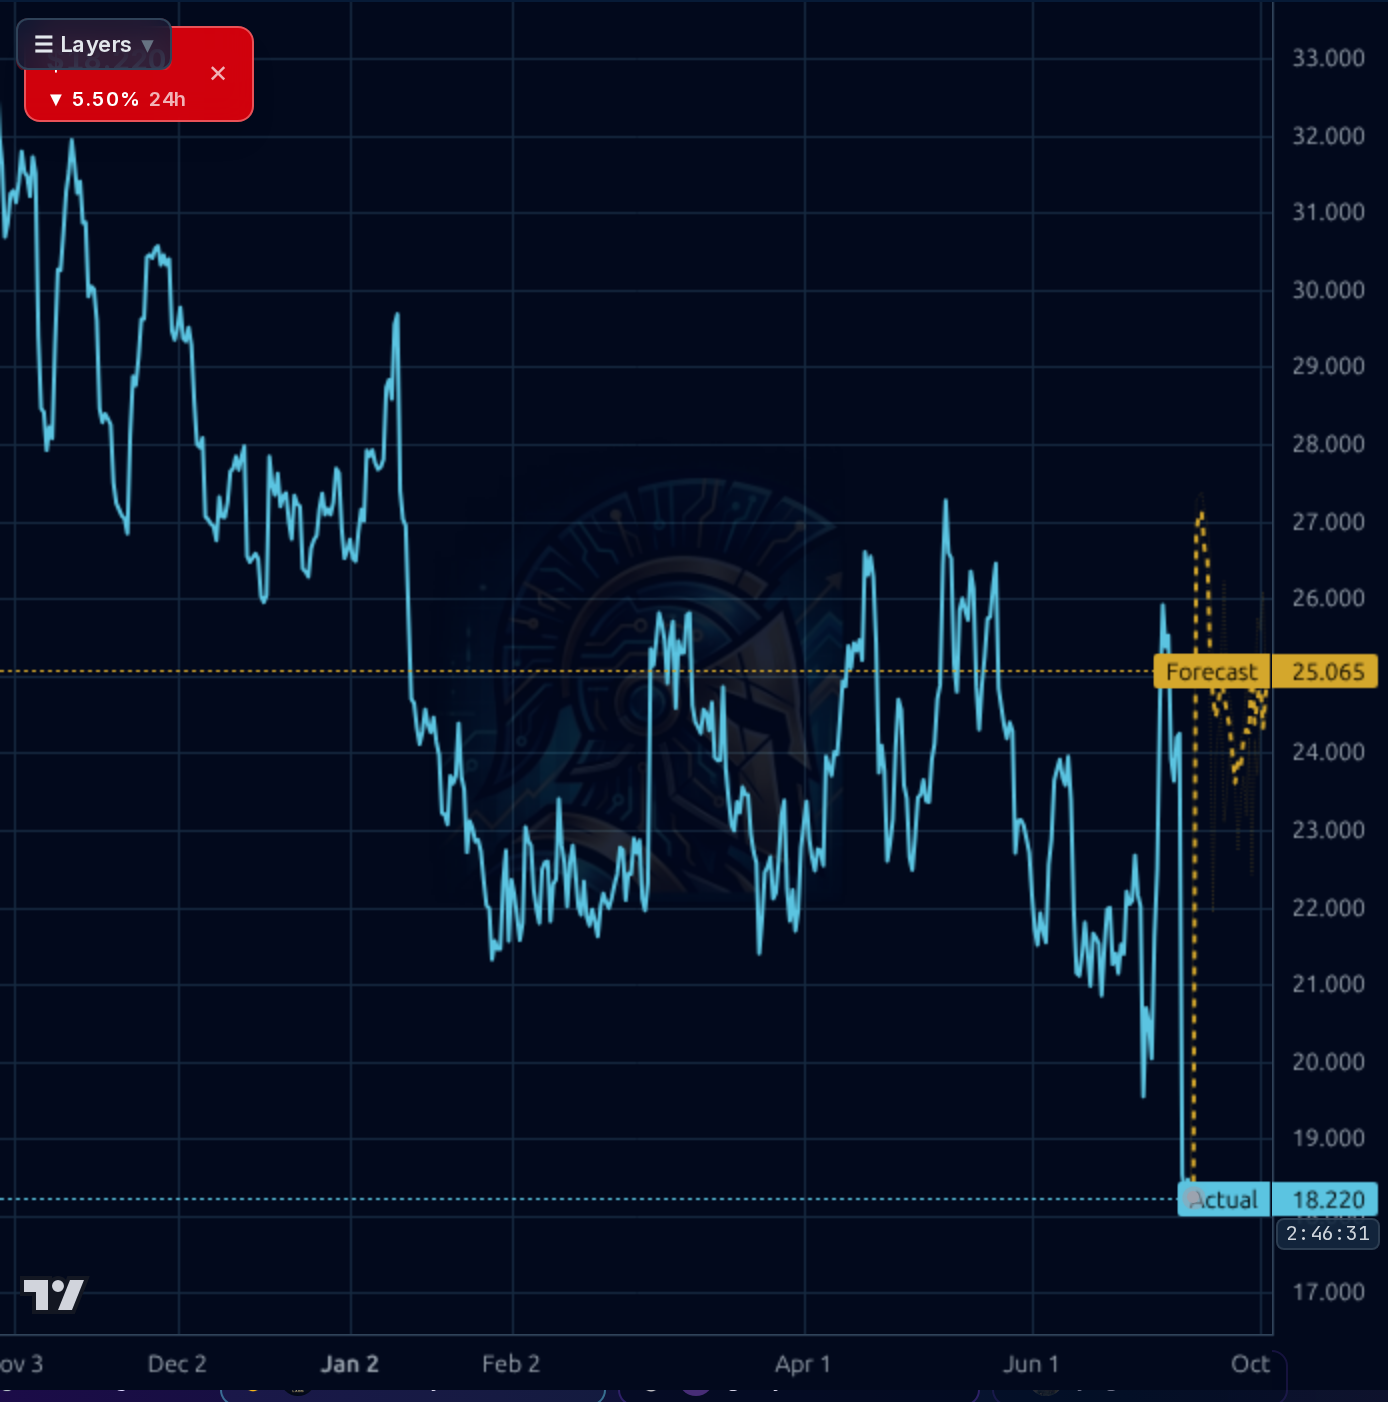
1-4 week view: The tape is in active price discovery at fresh 52W lows with no immediate catalyst until Nov 4 earnings (~50d out). Do not front-run the knife. Scale-in only: 25% starter at current $18.22 given RSI 31.7 + insider cluster + oversold; add 25% on either a $16.50-17.00 flush with volume climax OR a reclaim of $20.50 on volume. Keep dry powder for either scenario. Hard invalidation: sustained close below $17.00 (opens $15-16 air pocket and implies covenant/dilution repricing is starting). Position size small (0.5-1% of book) given 7.25% weekly volatility and headline risk.
1-6 month view: Thesis is that operational inflection (GM 61.6%, positive op income, ~$186M FCF) plus insider conviction sets up a mean-reversion trade toward the $21-22 broken-support zone, with the Nov 4 print as the key catalyst — must show sustained GM ≥61%, positive op income, and explicit debt/covenant commentary. Expected return range: -10% to +20%. Base case $21.50 (+18%) is a retest of broken support; bull case $26 (+43%) requires debt refinancing news or a strategic bid. What changes my mind: covenant amendment announcement, equity raise, further sell-side target cuts below $28, or a break of $17 with volume expansion.
1-3 year view: The terminal question is whether Enovis is a sub-scale medtech that gets acquired by Stryker/Zimmer/J&J at a premium, or a leveraged consolidator that successfully scales its Recon business + robotics platform (eCential knee 2028, shoulder 2029) to compete with Mako/Velys/Rosa. At 4.9x fwd P/E and 0.46x P/S with genuine FCF generation, the risk/reward is asymmetric IF the balance sheet holds through 2027 refi. Biggest structural risk is dilutive equity raise or covenant amendment that resets the equity story permanently — this is a 'balance sheet must not break' investment, not a growth-at-a-reasonable-price story. A successful robotics launch in 2028-29 could re-rate to 8-10x EBITDA ($35-45 range) but that path is not this analyst's base case given competitive positioning.
Underlying operations are quietly inflecting: Q2'26 revenue of $582.8M (+3.2% Y/Y at the top line), gross margin stepped up to 61.6% from 59.9% in Q3'25, operating income turned positive at $22.3M vs -$8.1M three quarters ago, and TTM FCF is ~$186M — enough to organically service maintenance capex and modestly delever. Adjusted EPS beat by 6.3% ($0.90 vs $0.79 YoY). However, the balance sheet is the whole story: $1.37B of debt against only $12.6M of cash (down from $36.4M two quarters ago), debt/equity 0.93, and ~$1.1B of goodwill/asset writedowns in H2'25 producing GAAP TTM EPS of -$19.27. The debt-financed €155M eCential acquisition adds leverage exactly when the market wants de-leveraging, and consensus next-year EPS growth was cut from 7.1% to 1.4%. Capital allocation is coherent (build robotics optionality for 2028-29 knee/shoulder launches) but poorly timed vs the funding environment. Valuation is objectively cheap — 4.9x fwd P/E, 0.46x P/S, 0.71x P/B, EV/EBITDA 6.4x — but 'cheap' is doing a lot of work here without covenant/refinancing visibility.
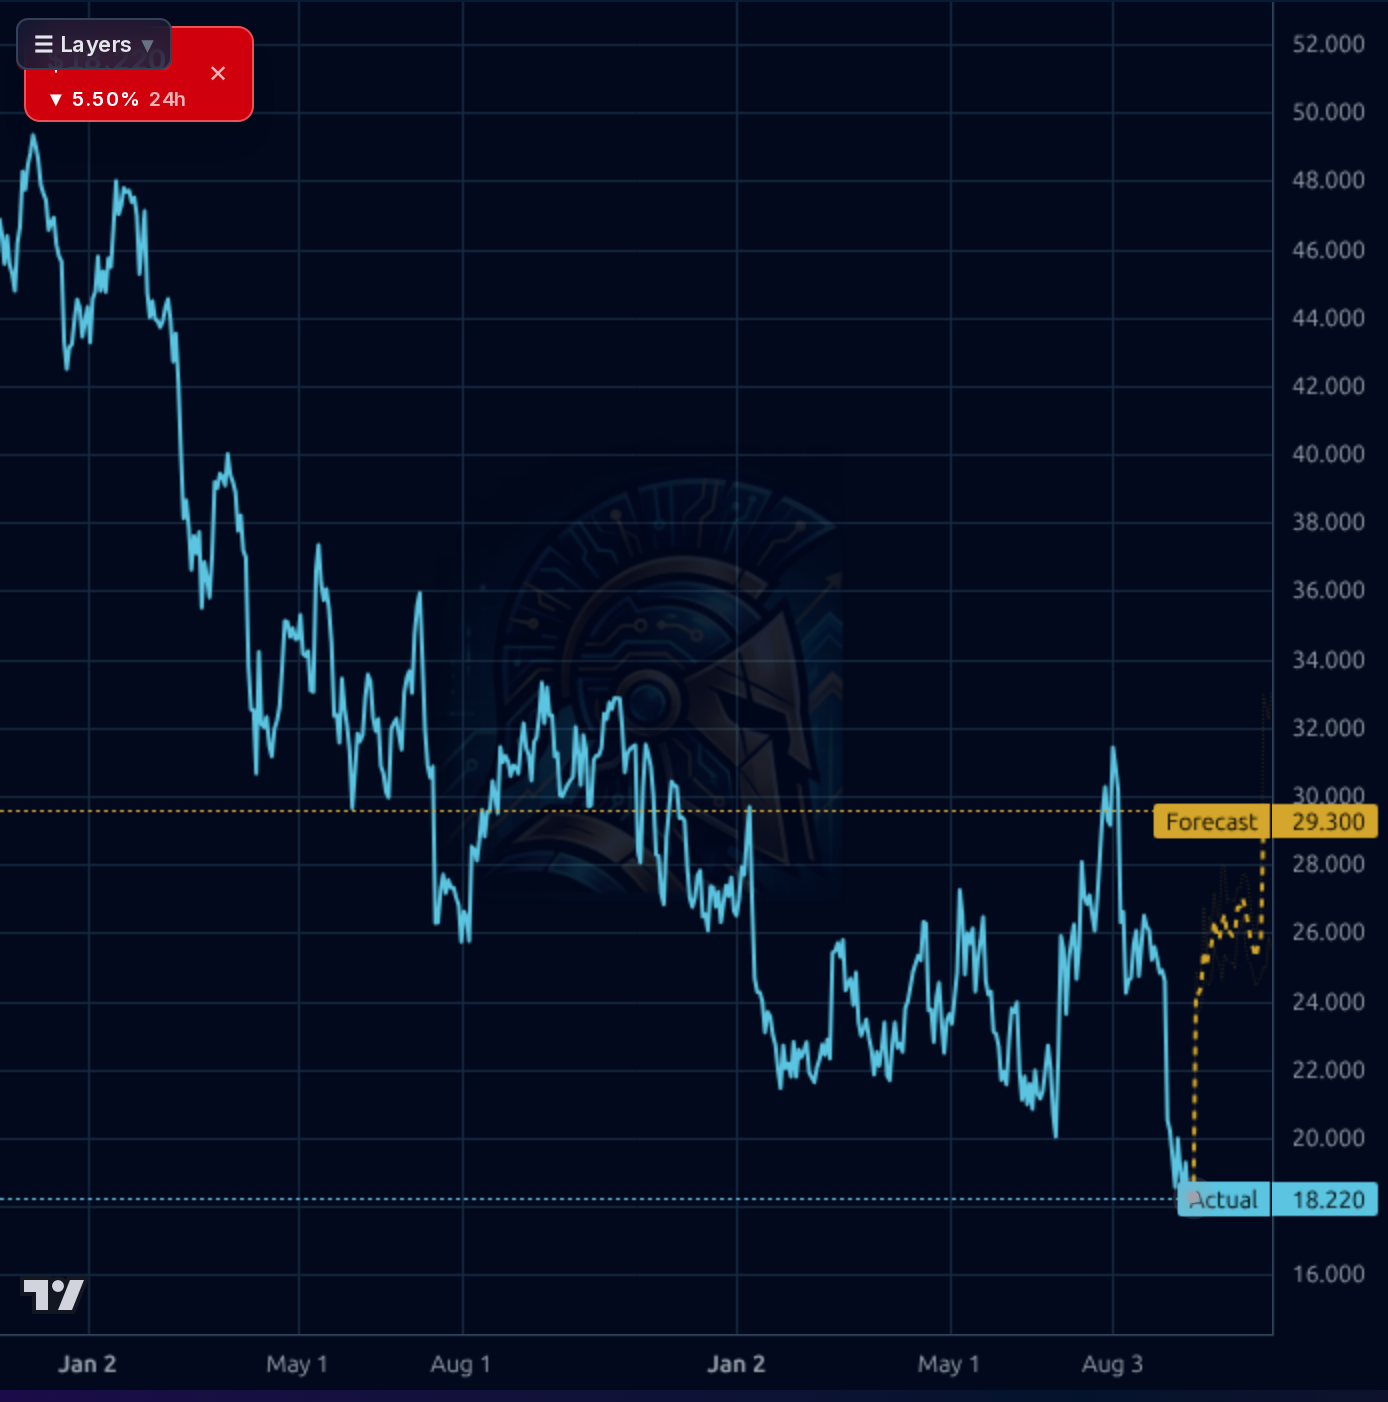
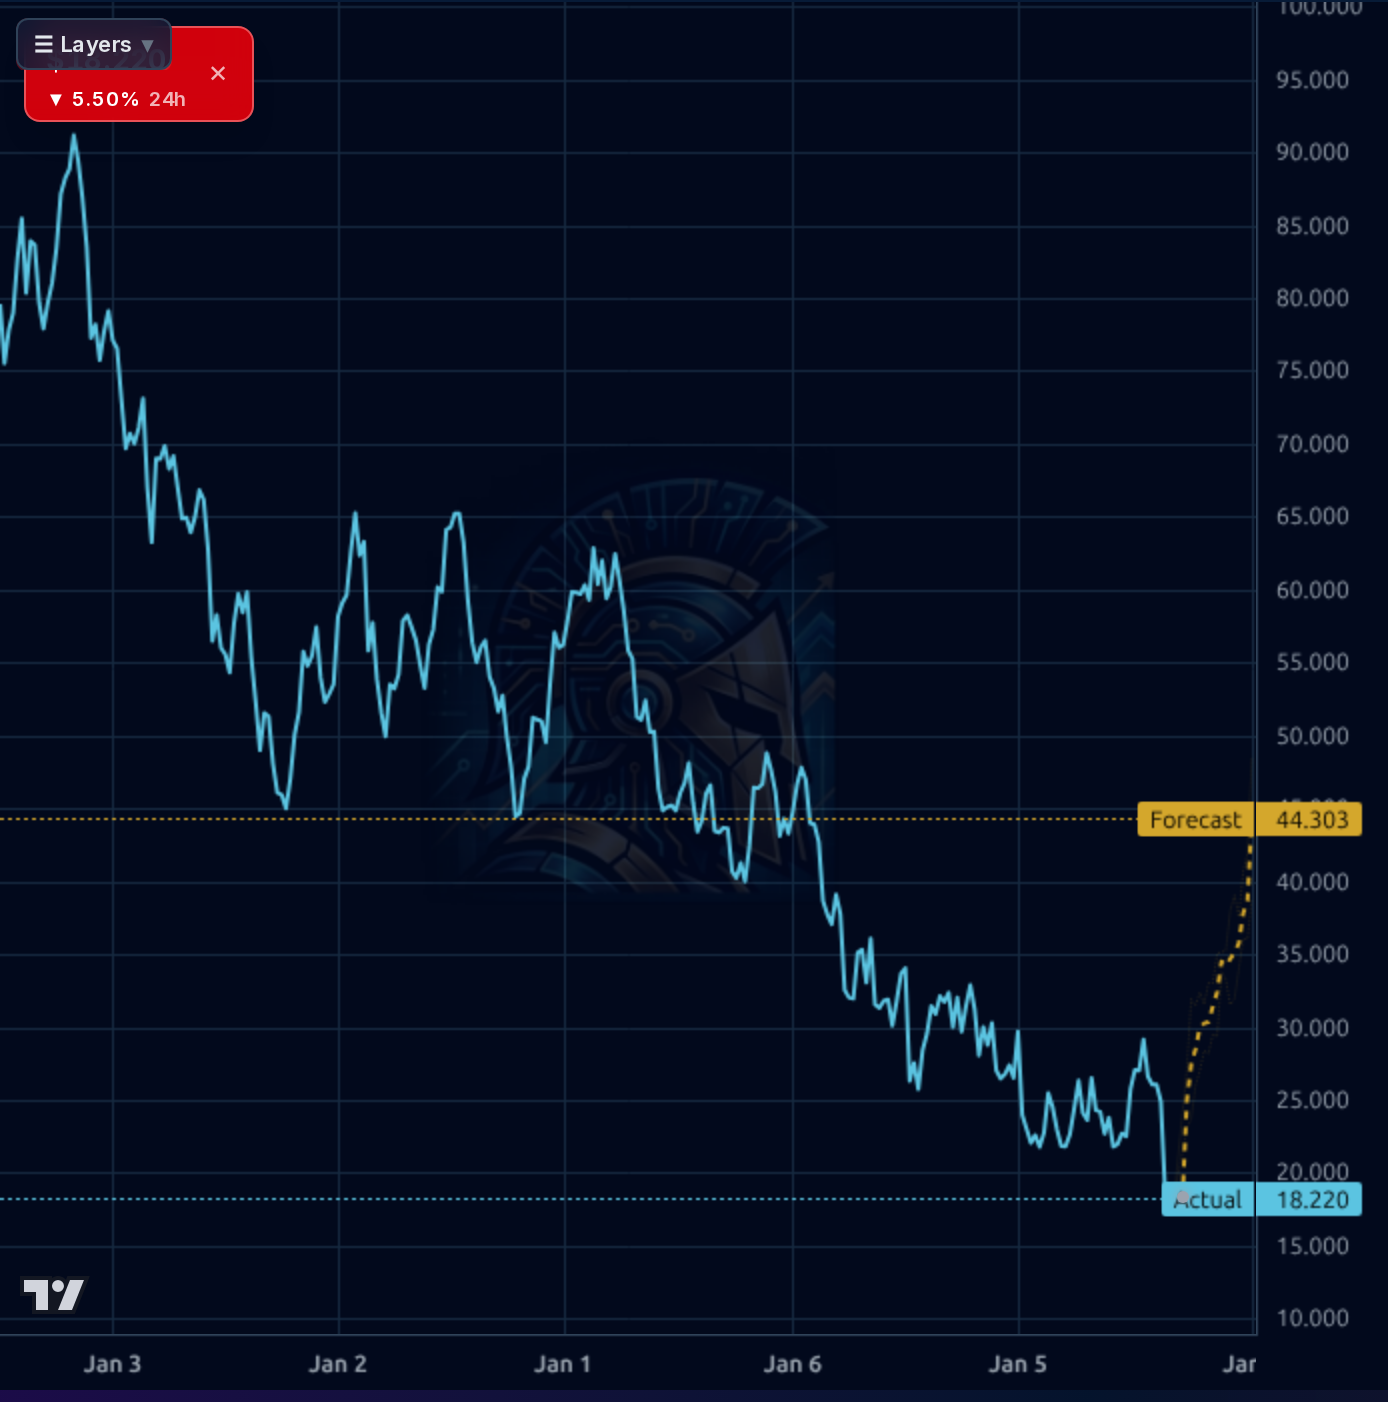
The tape is broken across every timeframe. On the 1h chart, ENOV gapped from ~$25 to sub-$19 in a near-vertical drop and has spent recent sessions grinding at fresh 52-week lows around $18.22, printing -5.5% today. Daily shows a clean break of the $22 support that held since May, with SMA20 -19.6%, SMA50 -27.8%, SMA200 -25.6% all cascading — a classic downtrend structure. Weekly context is worse: the stock has traced a multi-year distribution from ~$90 (Jan-23) to sub-$20 today, -66% over 3 years and -77% over 5. RSI at 31.7 is oversold but not extreme, ATR $1.42 implies wide daily swings, and 16.2% short float with 6.9 days to cover creates both squeeze and continuation risk. Immediate resistance is $20.50 (gap fill first attempt), then $22-22.50 (broken support turned overhead supply), with $18.00 as the critical invalidation — a break there opens $16-17 air pocket. The model's own forecast band (yellow on the 1d/1wk charts) is projecting reversion to $25-29 and $44 respectively, but the model's realized directional accuracy is 44%/67% vs 88%/83% naive baselines — heavily discount those projections.
The signal is threefold. First, the 9/1 8-K confirmed the binding offer for eCential Robotics — this is the fundamental repricing catalyst that broke the chart, pushing the robotics payoff to 2028 (knee) and 2029 (shoulder) while adding leverage now. Second, the analyst response has been uniformly negative: Wells Fargo $39→$33, BTIG $40→$36, Citizens $55→$47, and one fair-value model $33→$29 (though another separate model cut only $43→$42.30). Consensus target dispersion is now $29-47, and forward EPS growth was cut from 7.1% to 1.4% on 9/2. Third — and this is the offsetting signal — insider cluster buying is meaningful: CEO McDonald bought $250k on 9/4, CAO Engert bought $50k + $100k + $50k across 9/2-9/4, all in the $18-19 zone. That is real conviction from operators who know the covenant math. Retail sentiment (100% bullish of tagged) is a mild contrarian caution. Q2 print itself was solid (5% organic growth, margin expansion, reaffirmed guide with Q4 acceleration) — the selloff is entirely about the deal structure and balance sheet, not operations.
- eCential Robotics integration — €155M binding offer positions ENOV for knee robotics launch in 2028 and shoulder in 2029, addressing the primary structural gap vs Stryker Mako/J&J Velys
- U.S. Reconstructive segment growing ~6% in Q2'26 with Avis platform gaining traction — the highest-margin, highest-growth business line
- Gross margin expansion trajectory (59.9% Q3'25 → 61.6% Q2'26) suggests pricing power and mix shift toward Recon are durable
- Reaffirmed FY26 guide of $2.31-2.37B with explicit Q4 acceleration — Nov 4 print is the credibility test
- TTM FCF of ~$186M funds organic debt paydown and tuck-in M&A without dilution IF operations stay on track
- $1.37B debt vs $12.6M cash — cash balance dropped from $36.4M two quarters ago; covenant/refinancing risk is the primary equity gate
- eCential deal is debt-financed and extends leverage duration exactly when the market is punishing leverage
- Forward EPS growth cut from 7.1% to 1.4% on 9/2 signals sell-side is losing confidence in the near-term earnings path
- Analyst target dispersion $29-47 with 4 cuts in ~2 weeks — more downgrades likely if Q3 print disappoints
- European market softness explicitly flagged by management — geographic concentration of weakness
- 16.2% short float with 6.9 days to cover — can squeeze violently up but also amplifies downside on bad news
- ~$1.1B goodwill/asset impairments in H2'25 — further writedowns cannot be ruled out
- Sub-scale vs Stryker Mako/J&J Velys/Zimmer Rosa — 2028-29 robotics moat unproven, could be too late to matter
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord