ET — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live ET price forecast →
Energy Transfer offers a compelling 6.3% yield backed by strong fee-based cash flows, accelerating sales growth (+33% Y/Y TTM), and a supportive analyst consensus (1.48 recom, $24.64 target). Near price resistance at 52W high $21.84 with the AI forecast band signaling short-term downside, but insider buying of $21M+ by Chairman Kelcy Warren and improving fundamentals warrant accumulation on pullbacks rather than chasing.
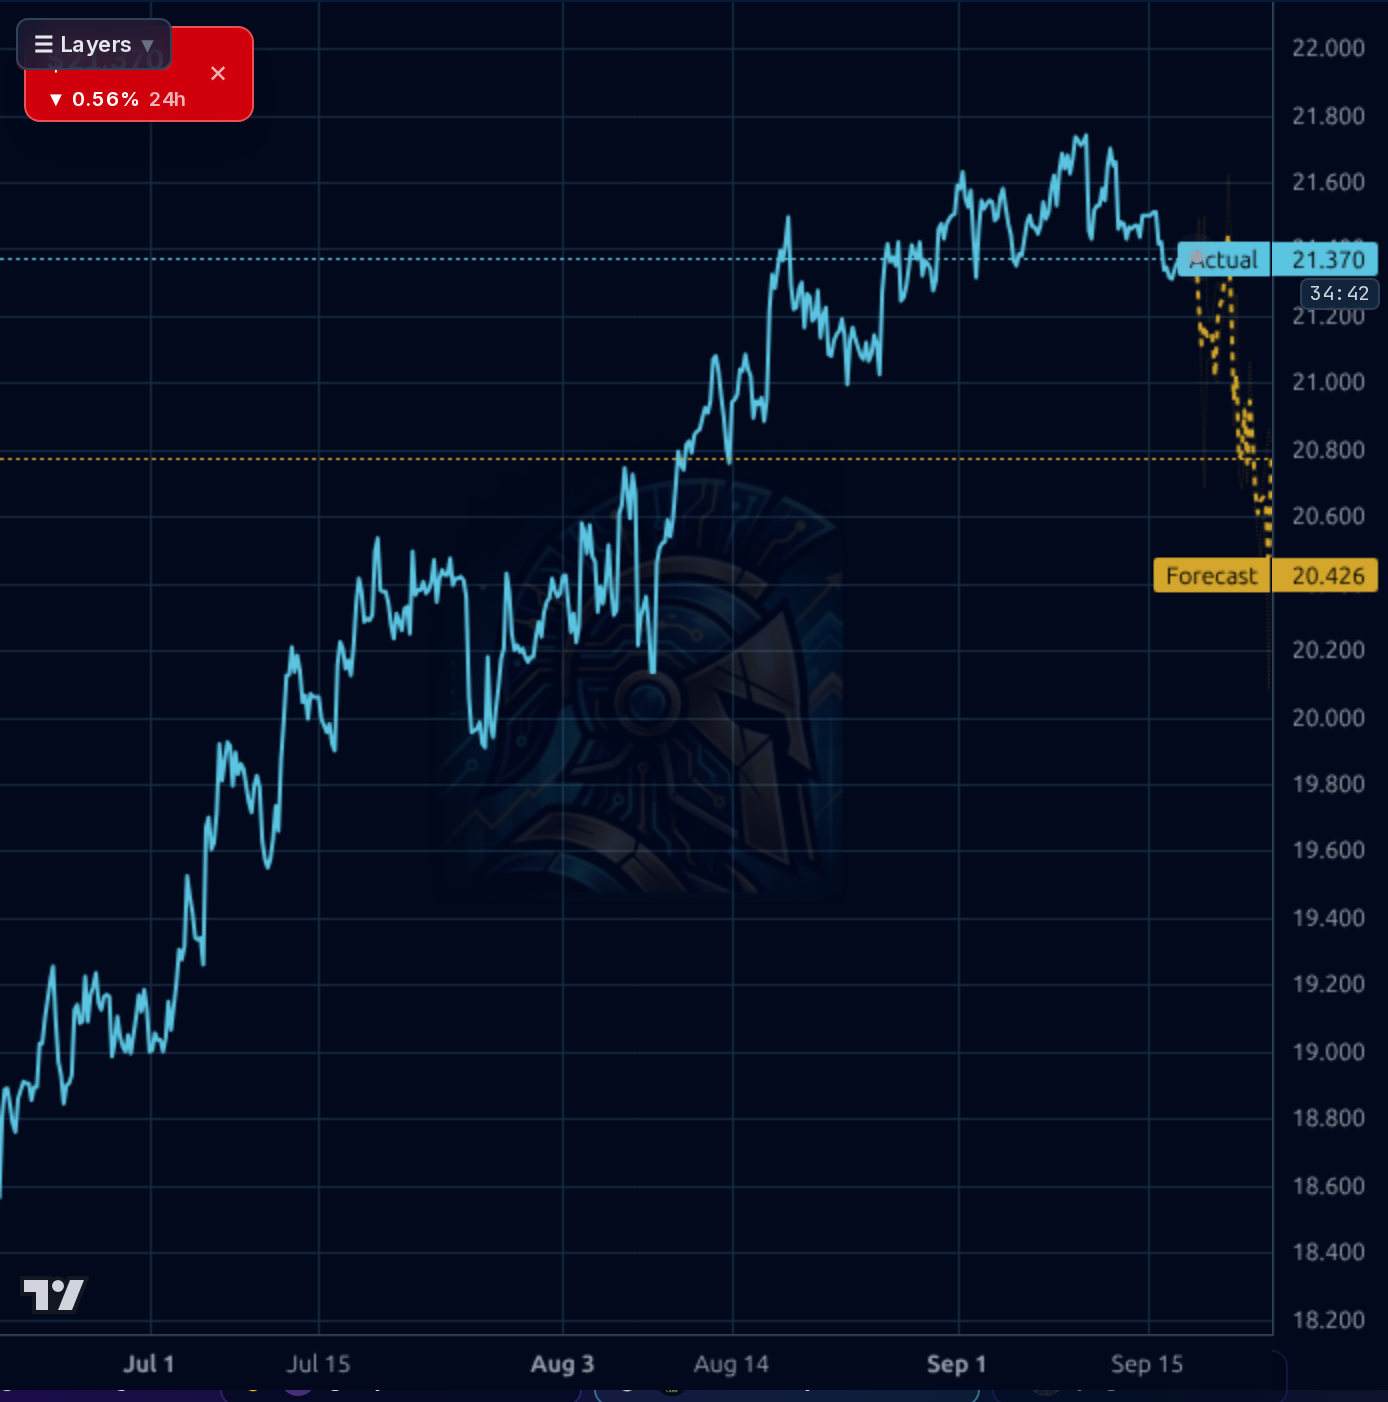
Near-term view is neutral-to-cautious given price is 2.3% off the 52W high, SMA20 has rolled negative, and the macro regime is risk-off with breadth deteriorating (44% >200dMA). Do not chase here. Wait for either (a) a pullback to $20.60-20.80 support (1h AI anchor and prior consolidation) for an initial buy, or (b) a decisive breakout above $21.84 on volume for a momentum add. Invalidation for tactical longs: daily close below $20.20 (August low structure). Position size: ¼ to ⅓ of intended full weight on any first entry.
6-month view is constructive. The combination of accelerating sales growth (33% Y/Y), insider buying at $21M+ scale, analyst target $24.64 (+15% upside), and 6.3% distribution yield sets up a total return of roughly 15-22% to base target. Catalysts: Q3 earnings 2026-11-04 (49d out), Texas exchange listing in early October, and any incremental data-center gas supply contracts. Thesis breaks if Q3 shows margin compression, distribution coverage weakens materially, or oil/gas prices collapse below cyclical support.
1-3 year terminal thesis is that ET is a beneficiary of the U.S. gas/LNG/NGL export buildout and secular data-center power demand, with fee-based cash flows compounding a mid-single-digit distribution growth rate on top of the current 6.3% yield — a plausible 10-14% annualized total return. Structural risks: (1) $70B debt load in a persistently higher-for-longer rate environment increases refinancing drag, (2) MLP tax structure headline risk if U.S. tax reform revisits pass-through treatment, (3) regulatory/permit friction on new interstate pipelines (Dakota Access precedent), (4) commodity cycle downturn compressing gathering/processing margins.
Revenue trajectory is strong: quarterly revenue climbed from $19.95B (Q3'25) to $34.33B (Q2'26), a 72% acceleration, with the fundamental-change signal flagging sales growth estimate revisions from 12.5% to 33.3%. Operating income has scaled from $2.15B to $3.57B over the same period and net income from $1.02B to $2.09B, with operating margins holding ~10.4%. Free cash flow of $3.16B TTM and $12.1B operating cash flow comfortably cover the ~$4.6B annual distribution, though the 108.7% GAAP payout ratio reflects MLP accounting quirks rather than a true coverage issue. Balance sheet is the primary blemish: $70.2B total debt against $148B assets, D/E of 1.99 (LT), and total liabilities of $97.4B — manageable given the fee-based model and 9.84x EV/EBITDA, but leaves little cushion in a credit tightening. ROE of 15.1% and ROIC of 5.0% are respectable for a capital-intensive midstream. Trailing P/E 14.6x, forward 12.2x, and PEG 0.85 all screen reasonably given the growth acceleration.
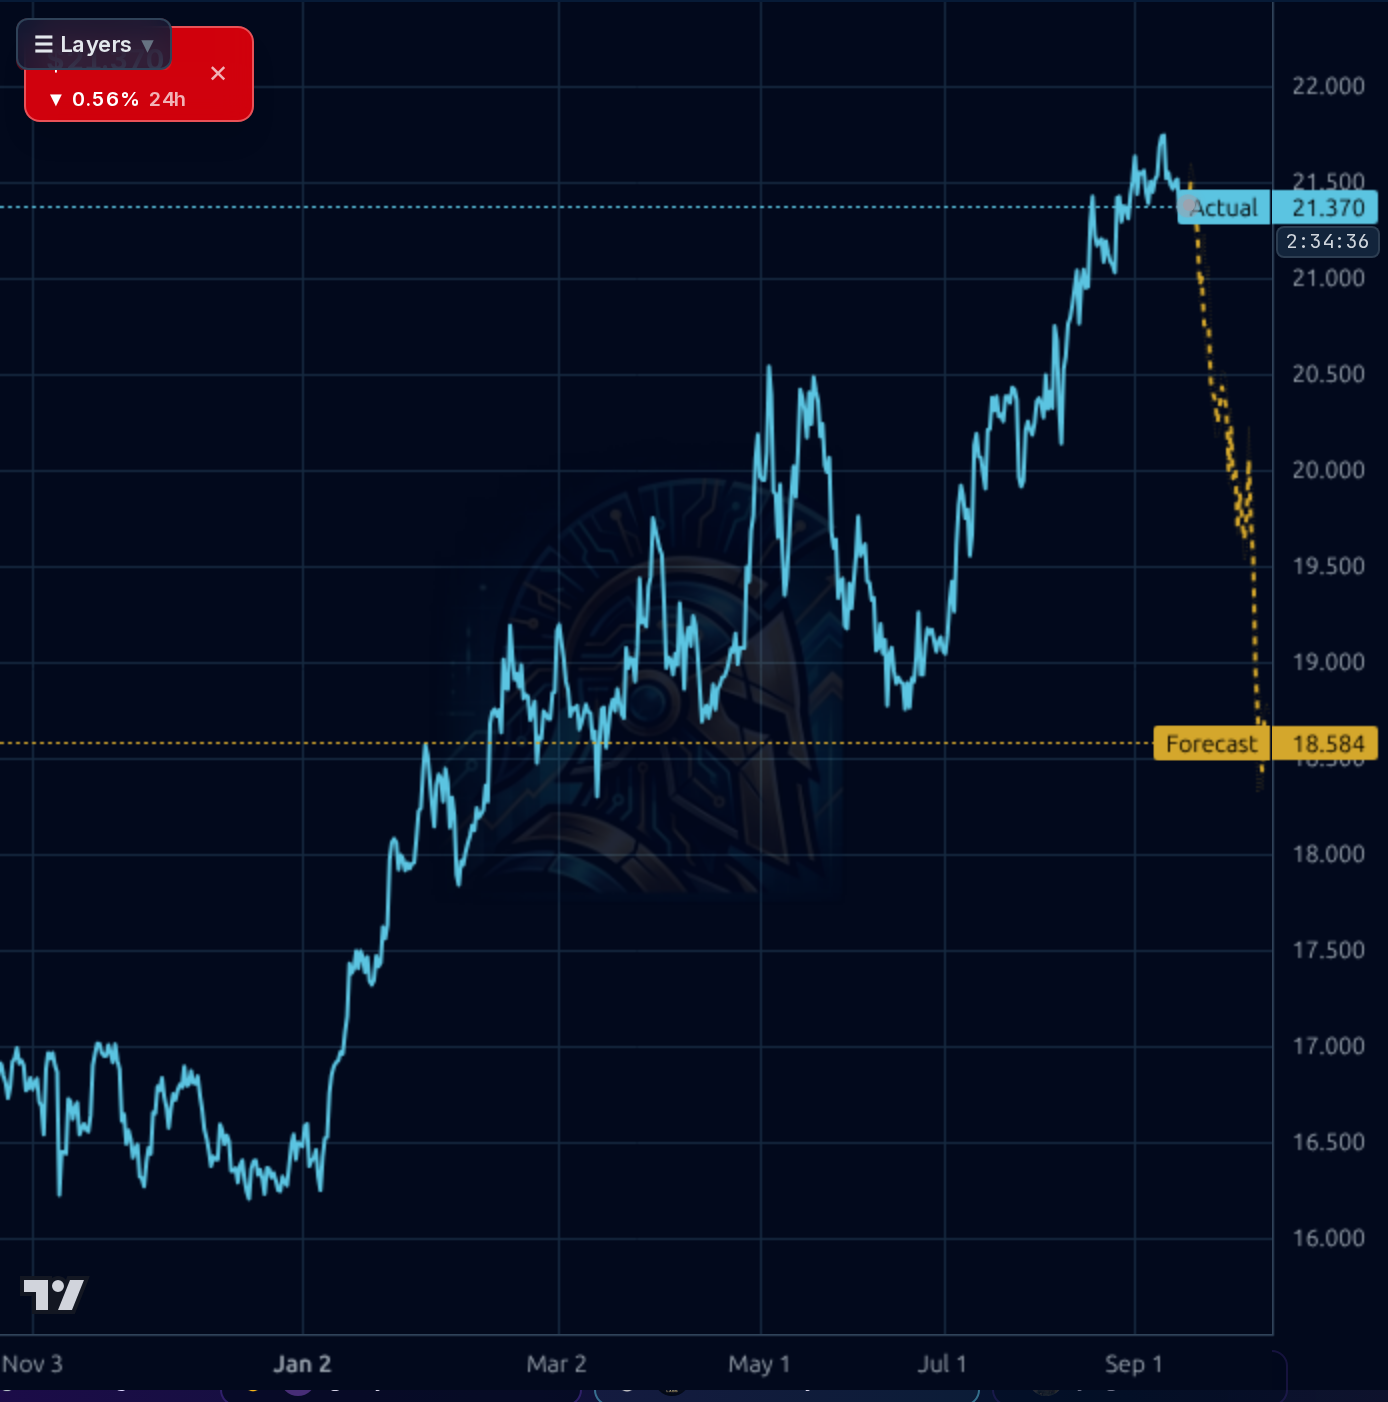
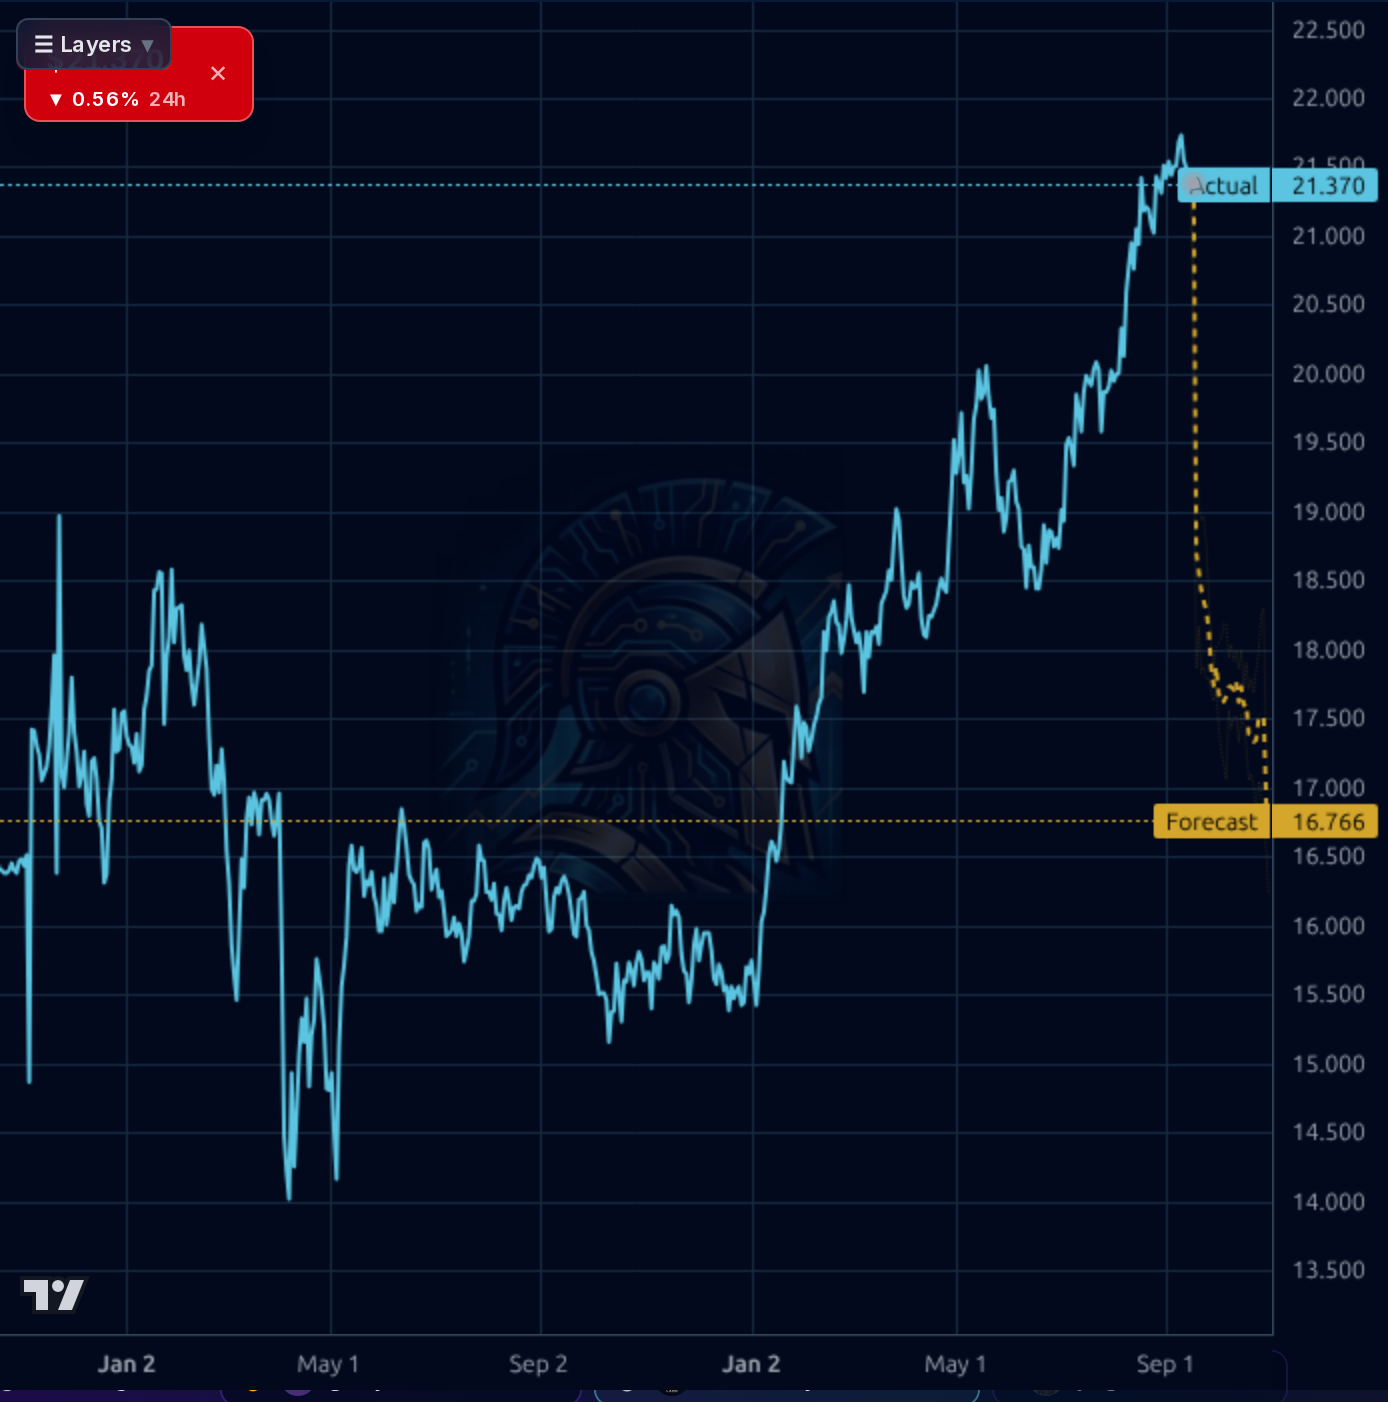
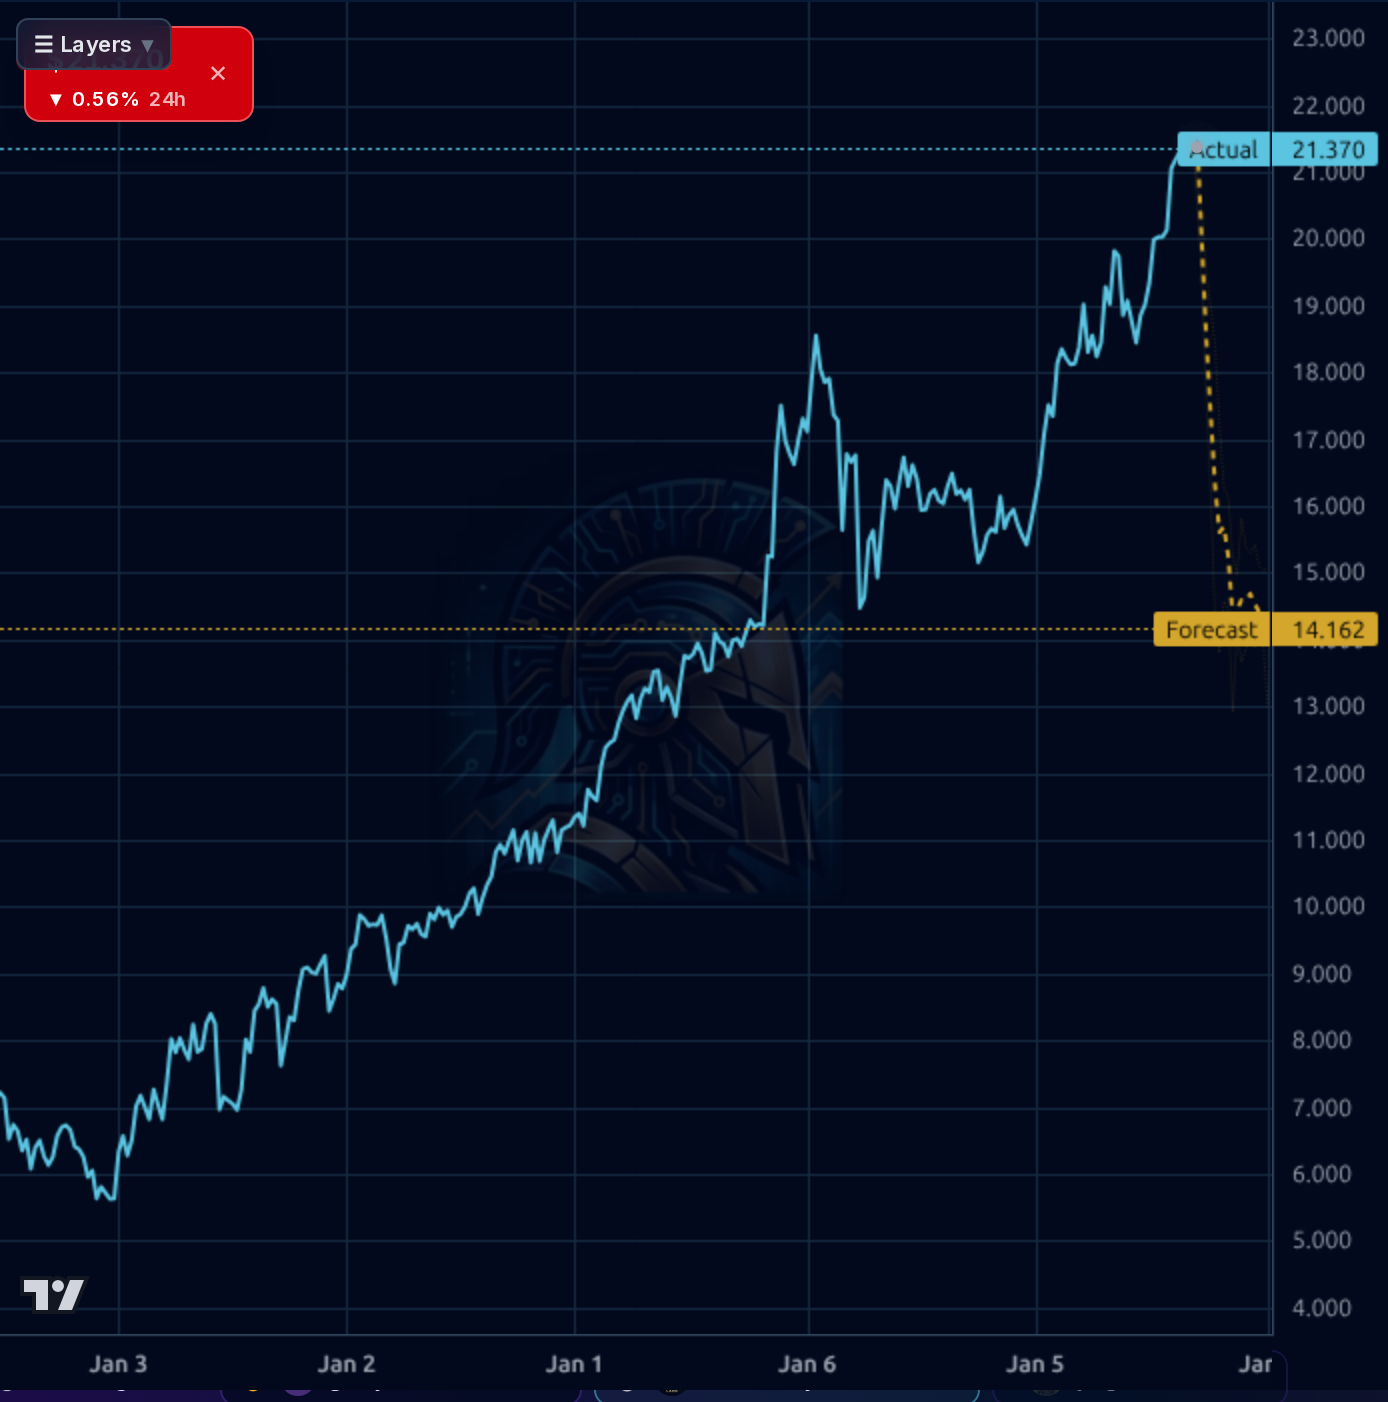
The multi-timeframe picture shows a mature uptrend meeting resistance. On the 1D/1W chart, ET rallied from ~$14 (early 2025) to a 52W high of $21.84 and is now consolidating at $21.37, just -2.3% off the high. SMA200 distance +12.0% and SMA50 +2.8% confirm the primary uptrend, but SMA20 has flipped to -0.31% and the weekly print is -0.84%, hinting at near-term exhaustion. RSI 53.8 is neutral — no overbought signal but no oversold buying opportunity either. Kronos AI forecast bands across all four timeframes (1h/4h/1d/1wk) uniformly project downside — to $20.43 (1h), $18.58 (4h), $16.77 (1d), and $14.16 (1w). However, the model's realized directional accuracy is 25% (1d) and 50% (1wk) versus naive baselines of 74% and 67% — the model is being BEATEN by naive persistence, so these bearish forecasts should be heavily discounted. Key support: $20.80 (yellow dashed line / 1h forecast anchor), then $19.60 (August base), then SMA200 area ~$19.05. Resistance: $21.84 52W high, then round-number $22.00.
The signal-heavy items are the SEC 8-K on 2026-09-10 announcing ET's voluntary listing move from NYSE to the Texas Stock Exchange in early October — a symbolic but operationally minor event that could add short-term index-inclusion friction but improve regional visibility. Multiple SeekingAlpha/Zacks/Barchart pieces reinforce the consensus 'Strong Buy' thesis: 6.3% yield, natural-gas/NGL business momentum, and AI/data-center demand tailwind. The most material insider signal is Chairman Kelcy Warren's $21.3M in open-market purchases across 2026-08-18/19, plus a $250k director buy — this is high-conviction insider accumulation into strength, not selling. Sales growth estimates were revised from 12.5% to 33.3% (+20.8pp), a material L2 bullish fundamental change. Retail sentiment is 100% bullish (small sample) with a Cramer buy call — a modest contrarian caution but not extreme.
- Q2'26 revenue of $34.3B represents a 72% ramp from Q3'25 ($19.95B), driven by NGL and natural gas segment momentum per recent SeekingAlpha coverage
- Sales growth estimate revision from 12.5% to 33.3% (+20.8pp) flagged as an L2 bullish fundamental-change signal
- Data-center-driven natural gas demand cited as a secular tailwind supporting midstream throughput visibility
- Texas Stock Exchange primary listing (October 2026) may improve regional institutional visibility and analyst coverage
- Distribution growth track record (3Y div growth 14.6%) supports continued raises on top of the 6.3% current yield
- High leverage: $70.2B total debt, D/E 1.99, LT-Debt/Eq 1.98 — refinancing risk in a higher-for-longer rate regime
- Price trading only 2.3% below 52W high in a risk-off macro regime (SPY late markup/distribution, breadth deteriorating)
- AI forecast bands across all timeframes signal 4-33% downside, though model directional accuracy is below naive baseline
- GAAP payout ratio 108.7% could concern non-MLP-literate investors; scrutinize distributable cash flow coverage on Q3 print
- Delisting/relisting friction from NYSE→TXSE move could create short-term index/ETF rebalancing volatility
- Commodity cycle exposure to natural gas and NGL price weakness, particularly if data-center demand ramp disappoints
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord