ETOR — AI Stock Forecast & Price Targets
Published 9/13/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live ETOR price forecast →
eToro has been sharply repriced to ~$30 after breaking down from the $38-41 range, leaving the stock near 52-week lows despite a forward P/E of ~10 and PEG of 0.55. Fundamentals are mixed — quarterly revenue has stepped down materially over the last two prints while margins and ROE (~19.5%) remain healthy — and the setup pits a compelling valuation and consensus target ($48) against insider selling, a broken chart, and a decelerating top line.
Do not chase the model's bullish snap-back forecast. Price is pinned to the $28-30 shelf after a sharp break; wait for either (a) a reclaim of $32.50 on volume to confirm the low is in, or (b) a test of $28 that holds. Small starter position (¼ target size) is defensible here given valuation, but invalidation is a daily close below $28 — that opens $24.74. Avoid full size until momentum stabilizes; RSI 42 is not a bottom signal on its own.
1-6 month base case: eToro re-rates modestly as revenue stabilizes and the crypto tape firms, targeting the $36-40 zone (Goldman $36, gap-fill $38-40). The setup — forward P/E 10, PEG 0.55, $946M cash, and a 30%+ discount to consensus PT ($48.47) — offers asymmetric upside if Q3 (reported 11/9) shows revenue re-accelerating sequentially. Bull case is a return toward Keybanc's $45; bear case is $24-25 if crypto rolls over and Q3 disappoints. What would change my mind: another quarter of >30% sequential revenue decline, or a hard break of $28 support.
1-3 year thesis rests on eToro's platform diversifying beyond crypto beta — deeper equities/options monetization, AI-personalized product (CopyTrader/Smart Portfolios), and international regulated expansion — funded by a fortress balance sheet. If management executes the multi-asset pivot, sustained ROE ~20% at a re-rated 15-18x multiple supports $55-70. The dominant structural risks are (i) revenue concentration in cyclical crypto trading, (ii) regulatory shifts in EU/UK/US, and (iii) competition from Robinhood, Coinbase, and IBKR compressing take rates.
Revenue trajectory is the most concerning data point: quarterly revenue has declined from $4.10B (Q3'25) → $3.87B (Q4'25) → $2.43B (Q1'26) → $1.58B (Q2'26), a >60% drop off the peak that reflects the crypto-linked trading cycle. Yet profitability is intact and improving on a mix basis — operating margin expanded from 1.7% (Q3'25) to 4.3% (Q2'26), and net margin doubled to 3.4%. Balance sheet is a genuine strength: $946M cash, only $35M debt, current ratio 3.4x, book value $16.46/sh (implying P/B of just 1.84). Cash generation is real (TTM OCF $310M, FCF ~$300M) although Q2 OCF ($39M) slowed sharply alongside revenue. Valuation screens cheap on virtually every metric: trailing P/E 10.9, forward P/E 10.0, PEG 0.55, EV/EBITDA 3.96, P/FCF 8.8. ROE 19.5% and ROIC 18.8% support a quality bias. The Keybanc initiation at Overweight ($45 PT) and Goldman's move from $32 to $36 suggest the sell side is warming despite the tape. Insider selling (Shalev Eddy $3.1M on 8/28) is a real yellow flag on top of a lowered price target signal.
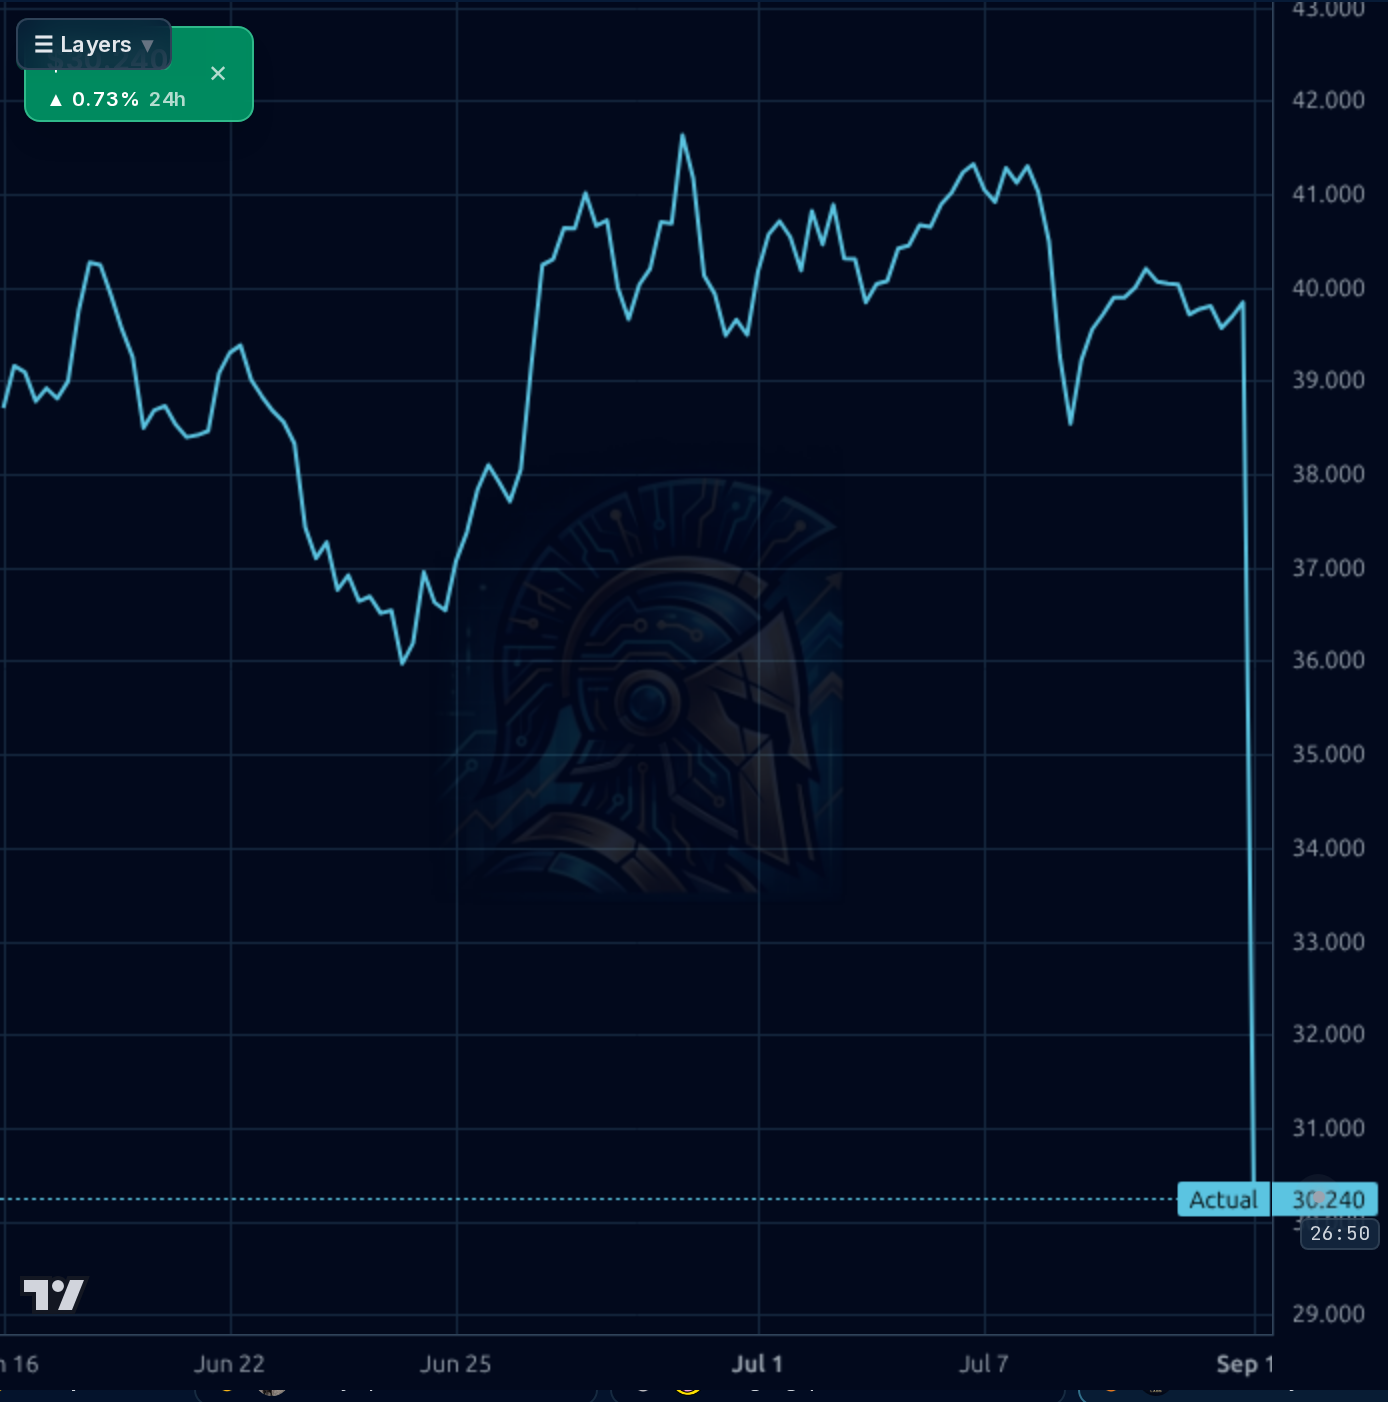
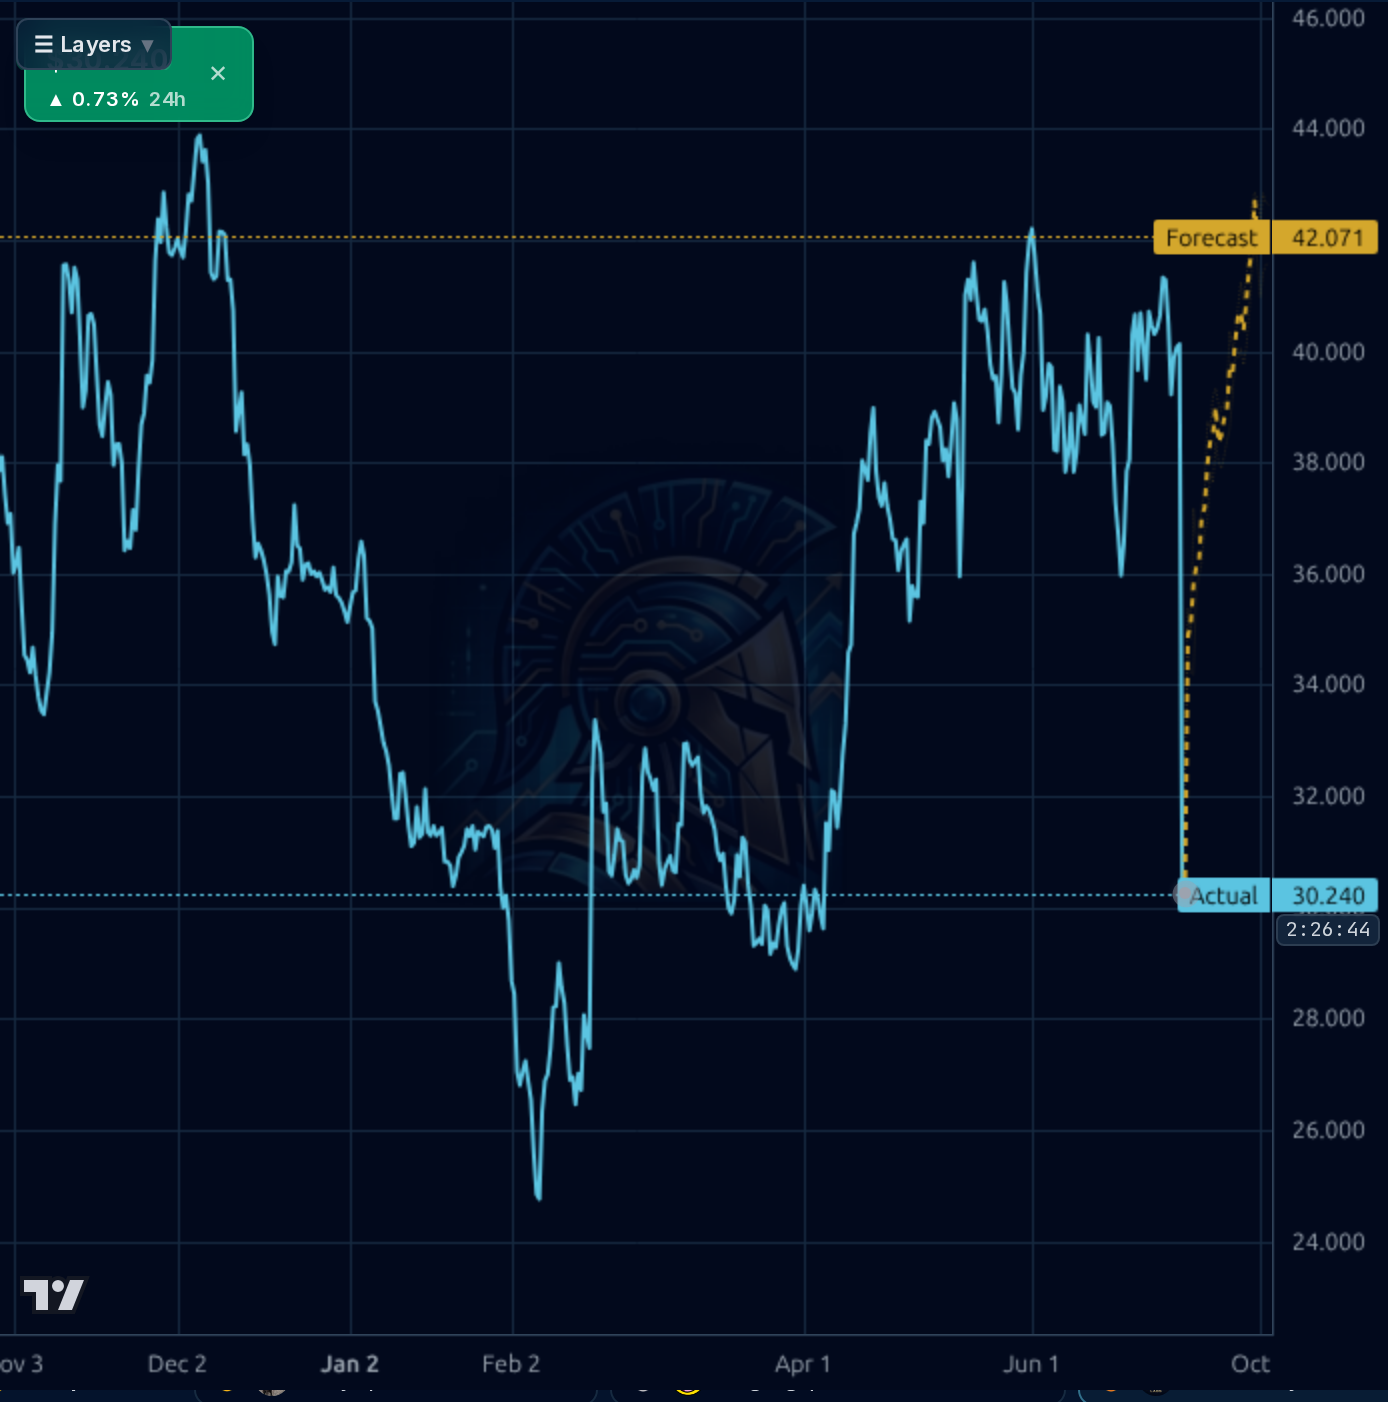
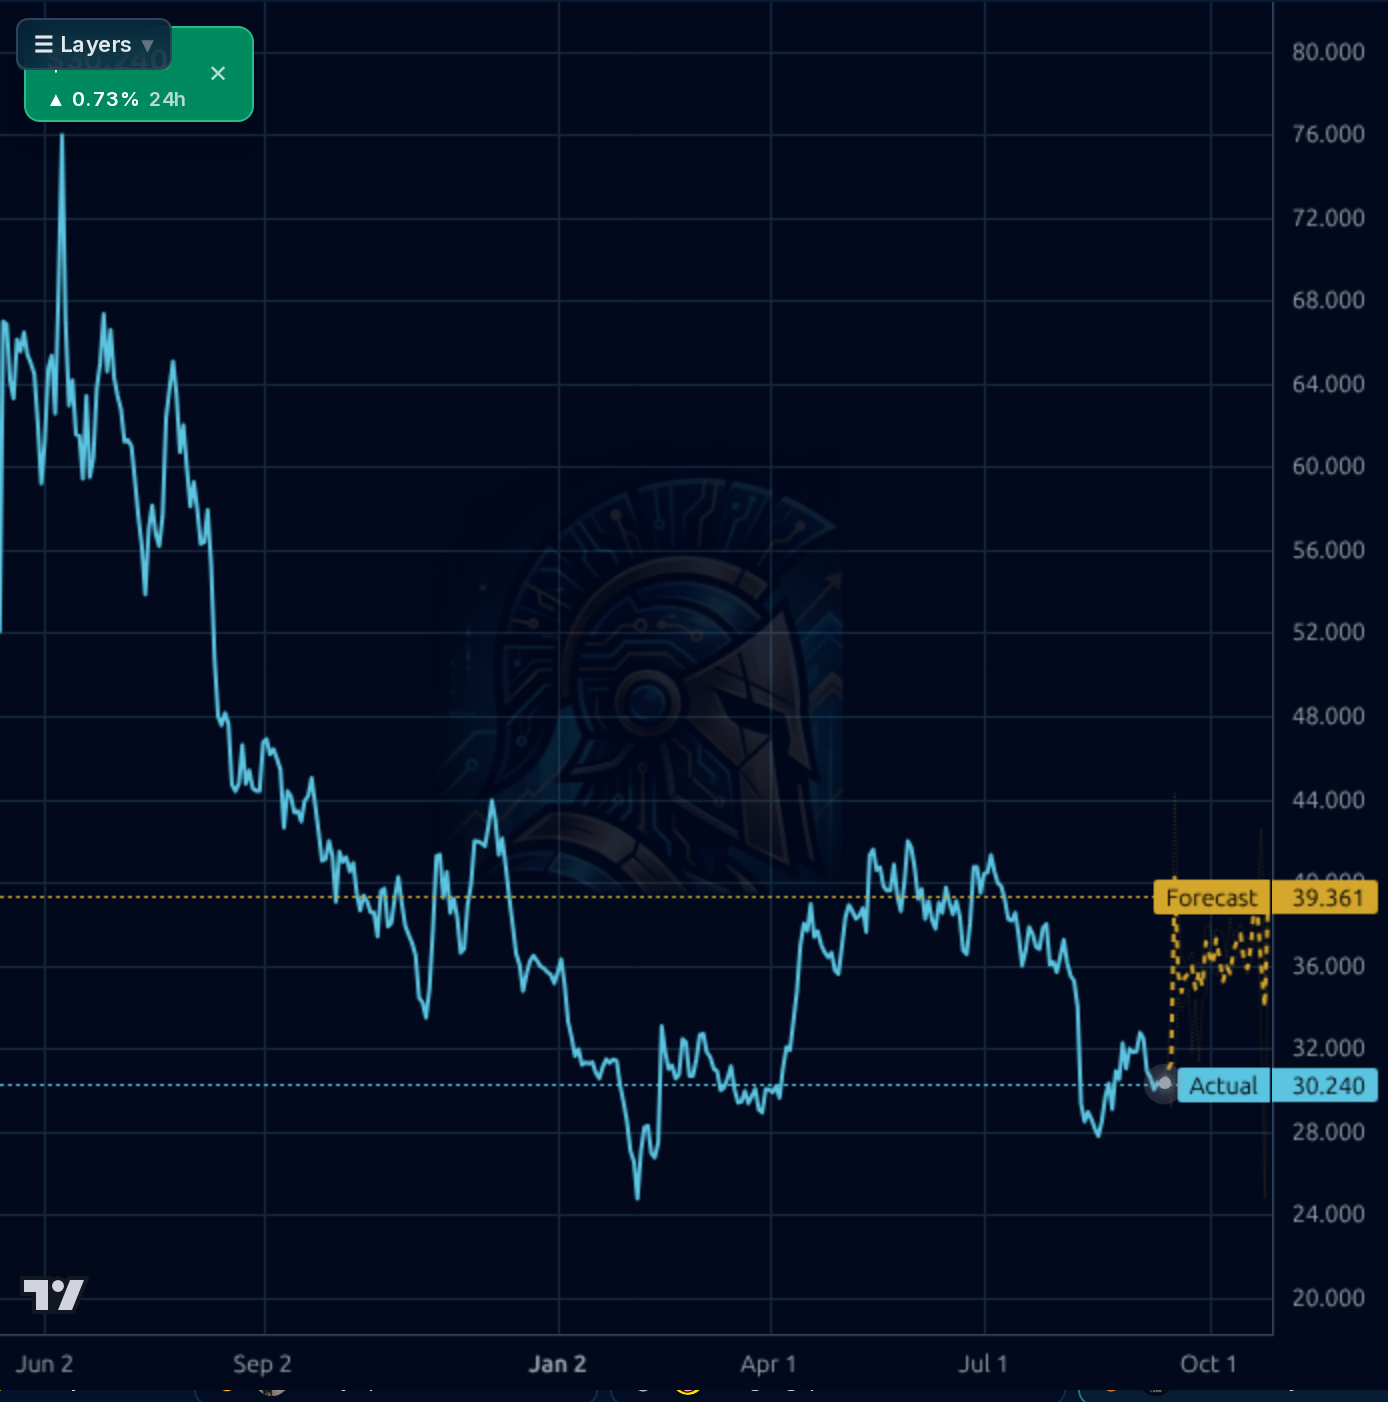
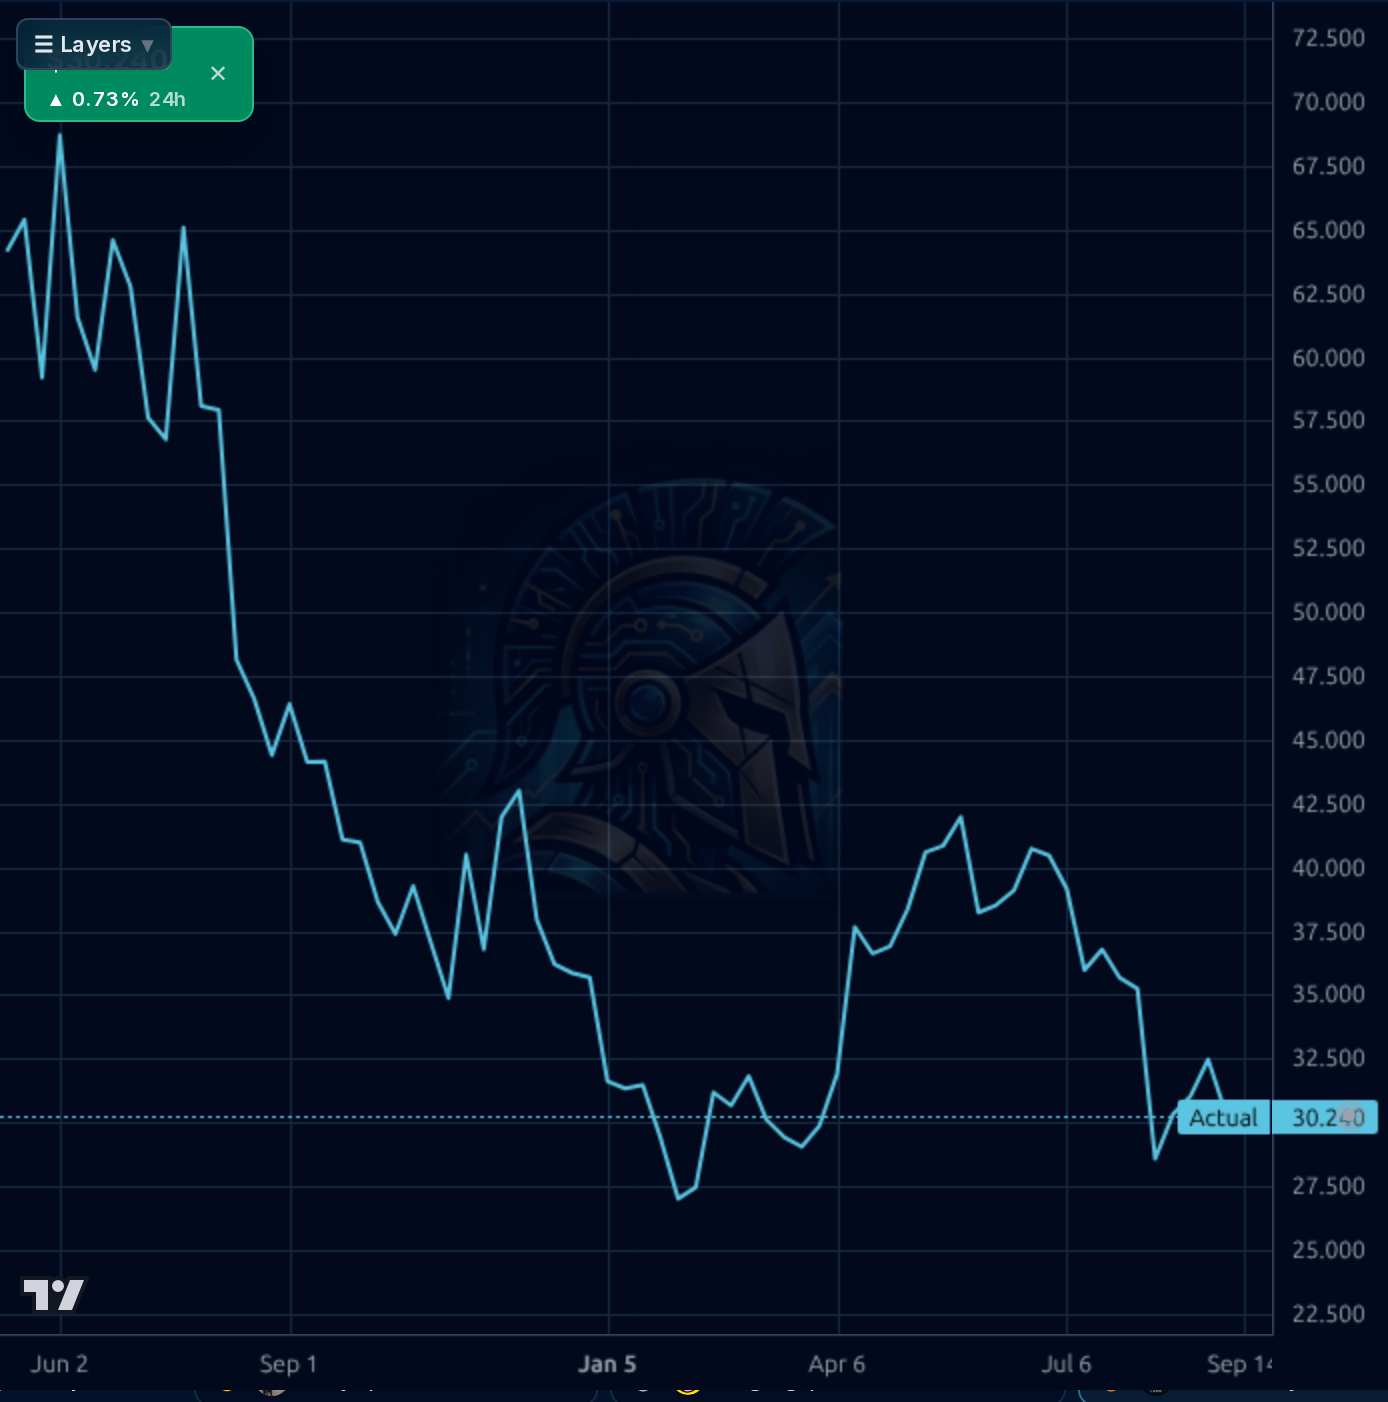
The chart is broken in the near term. The 1h view shows a violent gap/collapse from ~$40 to $30.24 into September — that's a ~24% drawdown in a compressed window and the largest move on the visible tape. On the 4h and 1d charts, price sits directly on the prior swing-low support zone from March ($28-30); a decisive close below $28 would open the door to the Jan/Feb capitulation lows near $24.74 (52w low). RSI at 42.7 is oversold-adjacent but not washed out; price is -11.2% below the 50D and -12.8% below the 200D SMA, confirming a downtrend that has re-asserted. The model's forecast band is aggressively bullish (1d/4h projections point to $42; 1d daily model $39.36) — implying mean reversion of roughly 30%+ from spot. However, historical directional accuracy at 1d is only in line with a naive baseline (70% vs 70%), and MAE grows quickly at longer horizons (MAPE >15% by day 10), so the model's bullish snap-back should be discounted. Key levels: support $28.00 / $24.74; resistance $32.50 (broken shelf), then $35, then $38-40 (gap fill).
Signal: Keybanc initiated Overweight with a $45 PT (9/1) — a meaningful institutional endorsement of the platform story. Goldman raised its target from $32 to $36 (9/9) while keeping Neutral, incrementally constructive. Offsetting that is the director sale of $3.12M on 8/31, which lands right at the price break and warrants attention as a proximate catalyst for the sell-off. Mizuho's 'crypto rally has legs' note (8/25) frames eToro as a beneficiary if crypto activity re-accelerates — this is the single biggest revenue lever given the Q1→Q2 revenue slide likely tracked crypto volumes. Noise: generic 'bitcoin analyst division' pieces and retail social chatter (100% bullish crowd of a small sample) — treat as a mild contrarian caution given the crowd is long into a downtrend.
- Crypto trading re-acceleration — Mizuho flagged three signs of a durable rally; eToro is direct beta to volumes and would see Q3/Q4 revenue snap back from the Q2 $1.58B trough
- Sell-side re-rating in progress — Keybanc initiated Overweight ($45) and Goldman raised PT to $36; further initiations could tighten the 60%+ gap to average target $48.47
- AI-enhanced platform features (CopyTrader, Smart Portfolios, eToro Academy) monetization — supports the higher-margin recurring revenue narrative embedded in 17.95% projected 5Y EPS growth
- Balance sheet optionality — $14.98/sh in cash (roughly half of market cap) enables buybacks, tuck-in M&A, or geographic expansion into regulated US equities/options
- Multi-asset expansion into US options and extended-hours equity trading — diversifies away from crypto-cycle dependence
- Revenue deceleration is severe: quarterly revenue fell ~61% from Q3'25 peak to Q2'26, indicating heavy exposure to crypto trading volumes
- Insider selling: Director sold $3.1M on 8/28 immediately before the price break, and prior director sale 8/12 — a cluster worth respecting
- Chart is technically broken: -22% quarter performance, price 12.8% below 200D SMA, next real support at 52w low $24.74
- Regulatory overhang: crypto/CFD regulation in EU, UK, and post-CLARITY US remains a live risk to product mix and margins
- Debt/Equity of 2.57 (per Yahoo) versus 0.03 (Finviz) — discrepancy likely reflects customer liability treatment, but worth diligence
- Recent price target cut (-8.4% to $51.38 on 8/12) signals sell-side estimates trending down before the drop
- Retail crowd is 100% bullish into a downtrend — contrarian caution flag
- Beta 1.6 in a neutral-to-deteriorating breadth regime (46% >200D) amplifies downside if SPY distributes
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord