FOXA — AI Stock Forecast & Price Targets
Published 9/11/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live FOXA price forecast →
FOXA offers a compelling value setup at ~11x forward earnings with resilient sports/news content revenue and a strong balance sheet, backed by a Q4 FY26 revenue beat ($4.21B, +28% YoY estimated) and a recent Wells Fargo upgrade to $80. However, extreme short interest (23.28% float), a deteriorating forward EPS estimate revision (-14.9pp), and a bearish long-term model forecast argue against chasing the recent rally — accumulate on weakness rather than breakouts.
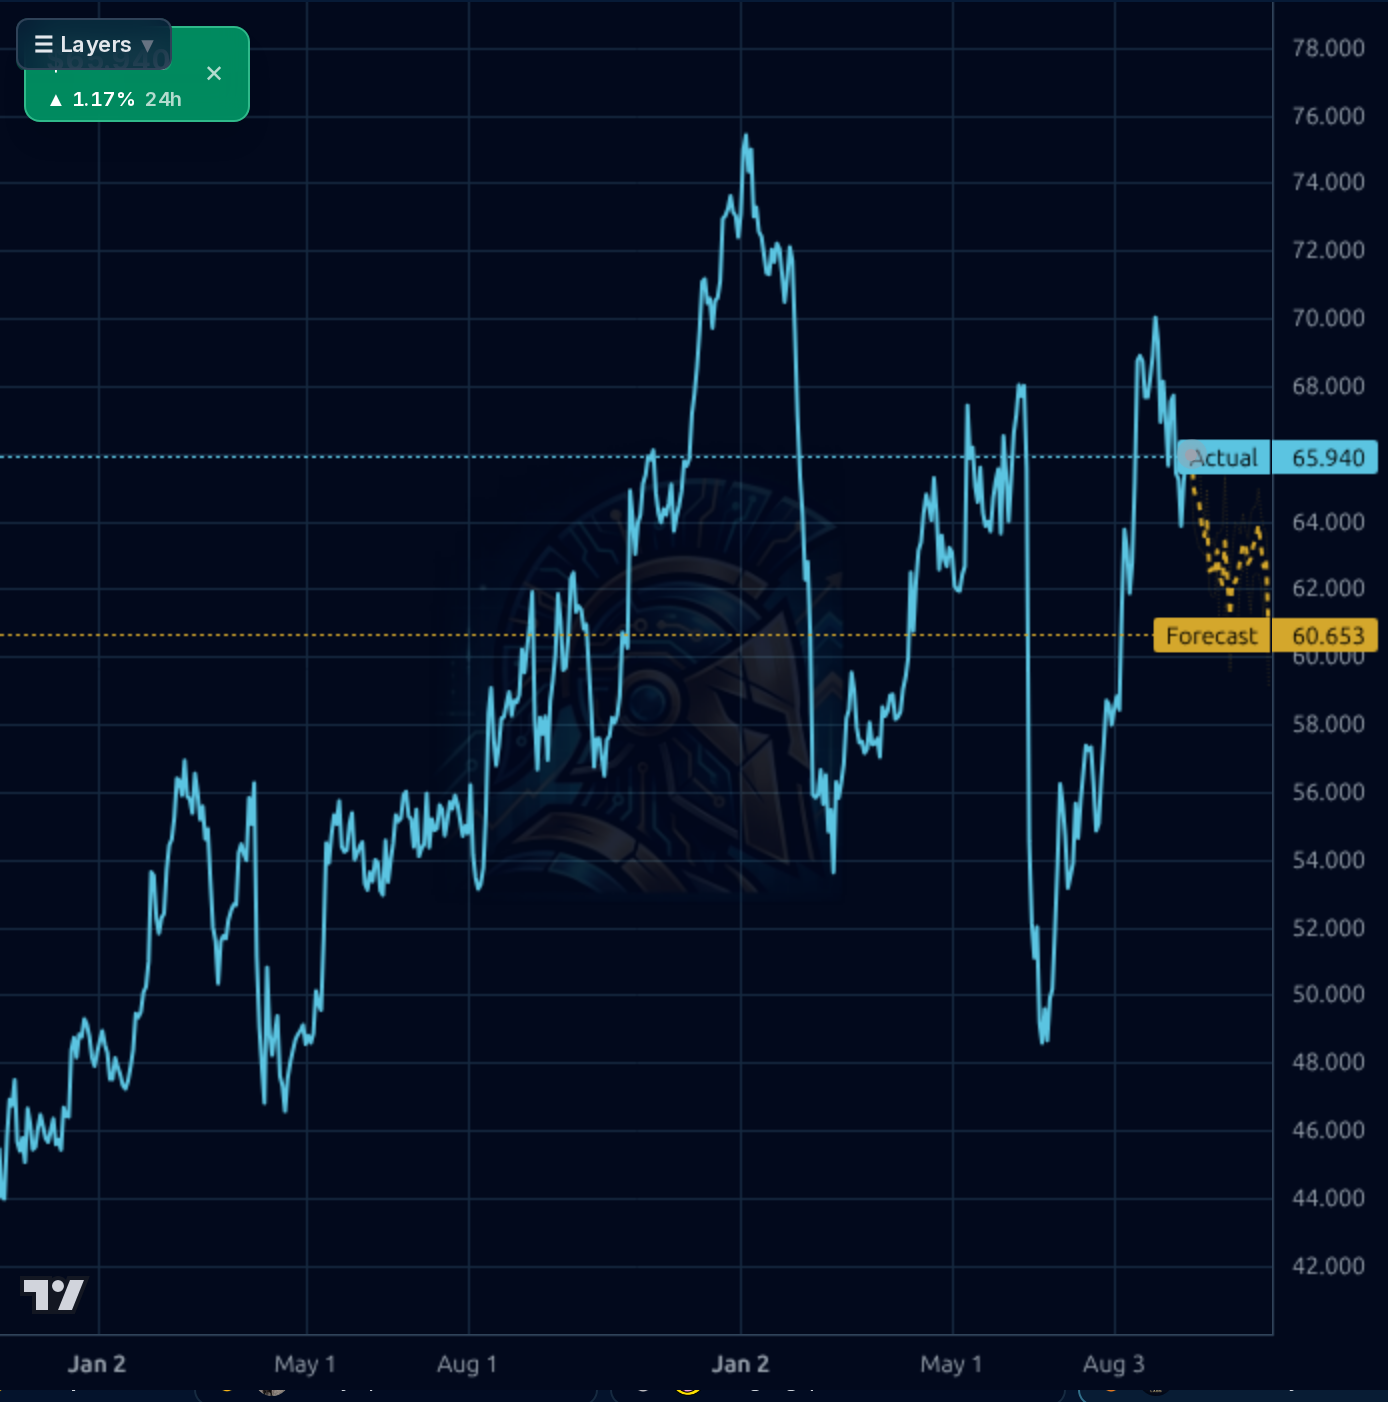
1-4 weeks: HOLD existing positions, add on pullbacks to $63-64. The stock has run +20% since the July low and gapped up on the earnings/upgrade cycle — chasing at $66 with a 1d model forecast of $60.65 offers poor risk/reward. Ideal entry zone $62-64 (breakout retest). Invalidation of the constructive setup: sustained close below $61 (breakout failure). Upside cap near-term: $68-70 resistance. Position sizing: half-size given 23% short float can drive violent squeezes both ways.
1-6 months: ACCUMULATE toward a $72-76 target range (10-15% upside). Thesis rests on (a) sustained Tubi/digital ad monetization visible in Q1 FY27 print (Oct 29), (b) continued sports content pricing power, and (c) potential short-covering catalysts as sentiment shifts. Expected return range: -8% to +18% (bear/bull). What would change my mind: Q1 FY27 revenue miss below $3.6B or operating margin compression below 22%, forward EPS revisions continuing to trend negative, or breakdown of $58 support.
1-3 years: Structural thesis is that FOXA is the last pure-play live sports/news broadcaster with declining but cash-generative linear TV funding a credible AVOD (Tubi) transition and the new FOX One streaming platform. Multi-year drivers: sports rights renewals at premium pricing, Tubi scaling toward $1B+ revenue contribution, disciplined capital returns via buybacks and dividend growth (3-4% CAGR). Biggest structural risk: accelerated cord-cutting compressing affiliate fee revenue faster than digital revenue can replace it, combined with any regulatory pressure on political broadcasting. Fair value in a 3-year window: $75-85 assuming margin stabilization at current ~20% operating margin.
Revenue quality is bifurcated but improving: Q4 FY26 revenue of $4.21B with operating margin of 25.7% and net margin 16.4% marks a sharp sequential recovery from Q3's $3.99B / 21.4% op margin / 4.2% net margin, driven by live sports monetization (FIFA World Cup) and Tubi traction. TTM revenue of $17.13B (+5% YoY) with operating margin of 20.4% and ROE of 14.3% is respectable for the sector. Balance sheet is a genuine strength — $4.2B cash vs $7.57B debt (net debt ~$3.4B), current ratio 3.17, debt/equity 0.65 — well within investment-grade norms. FCF quality is lumpy ($726M in Q4 vs -$791M in Q2 FY26) but full-year operating cash flow of $1.97B comfortably covers the $0.58 annualized dividend (14.6% payout) and the recently raised $0.29 semi-annual dividend signals board confidence. What's broken: the L1 bearish signal — forward-year EPS estimate revision falling from +14.8% to -0.2% — is the single most important fundamental data point and tempers the bullish narrative. TTM EPS declined -20.95% YoY, meaning the reported growth story is really an H2 rebound story that must be sustained.
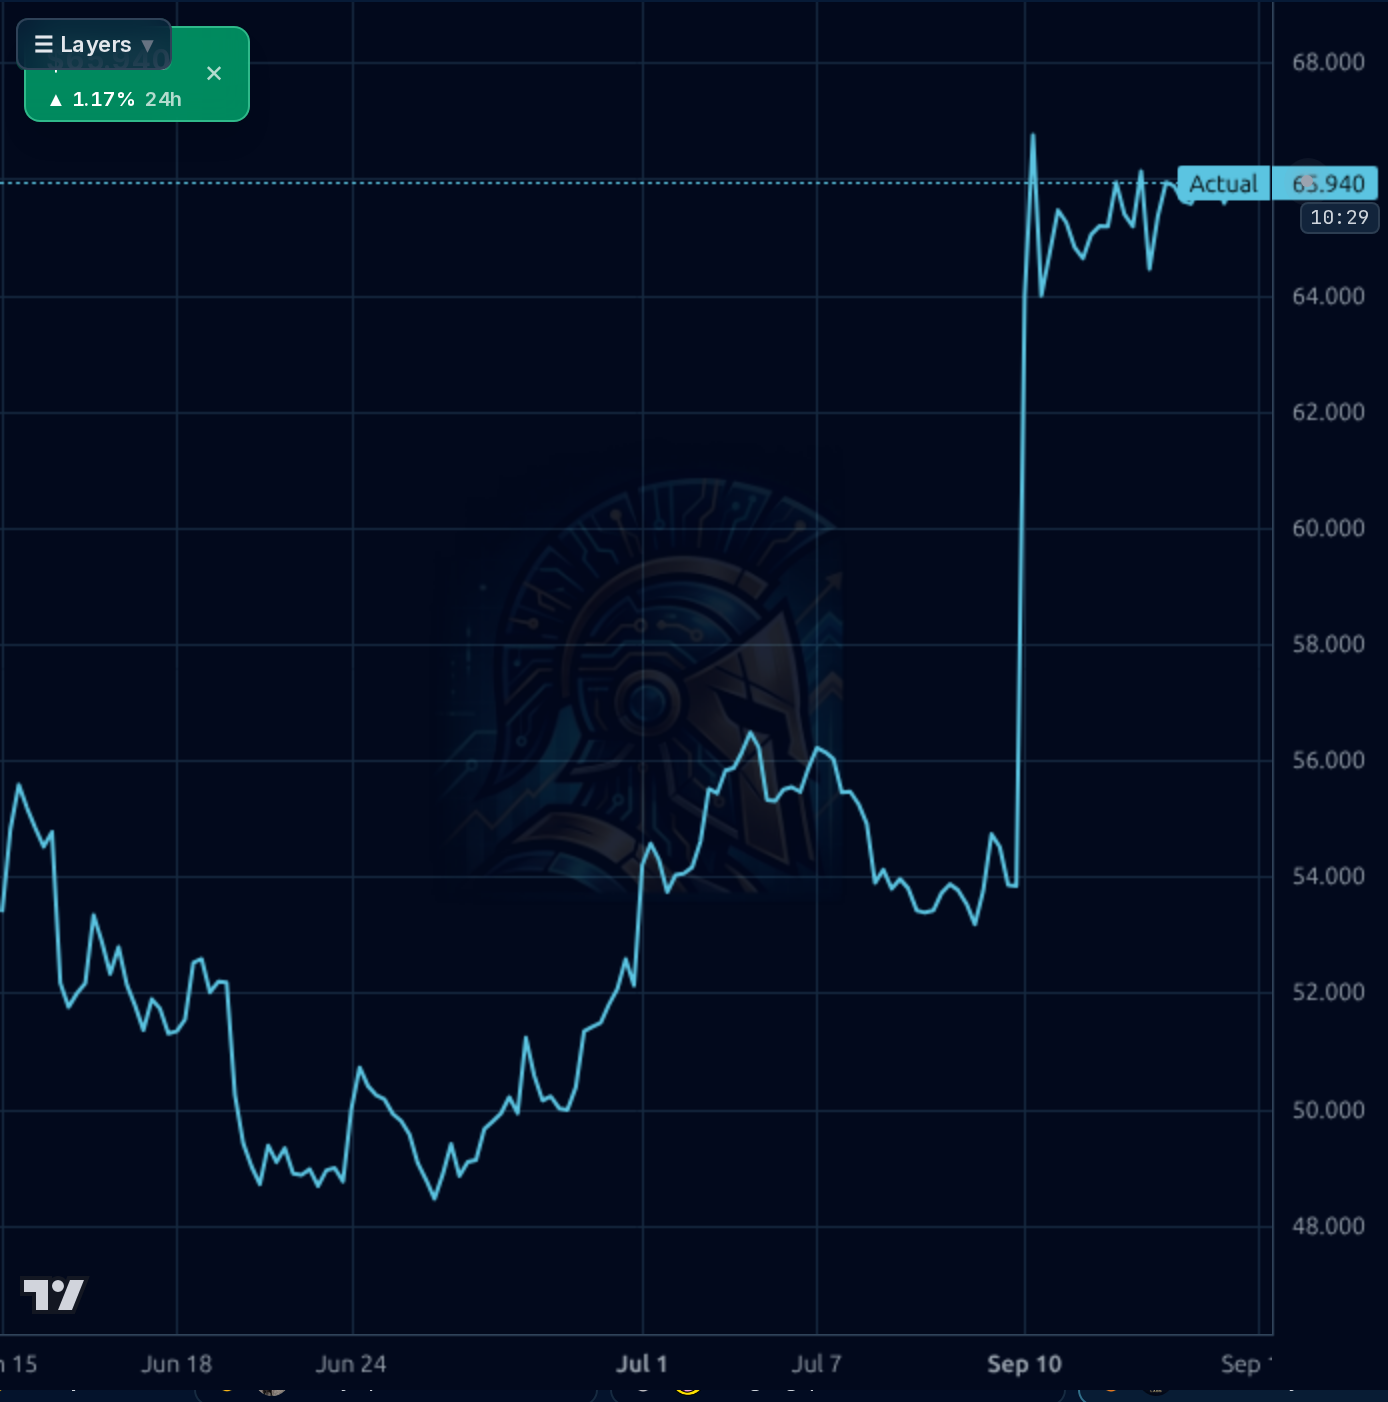
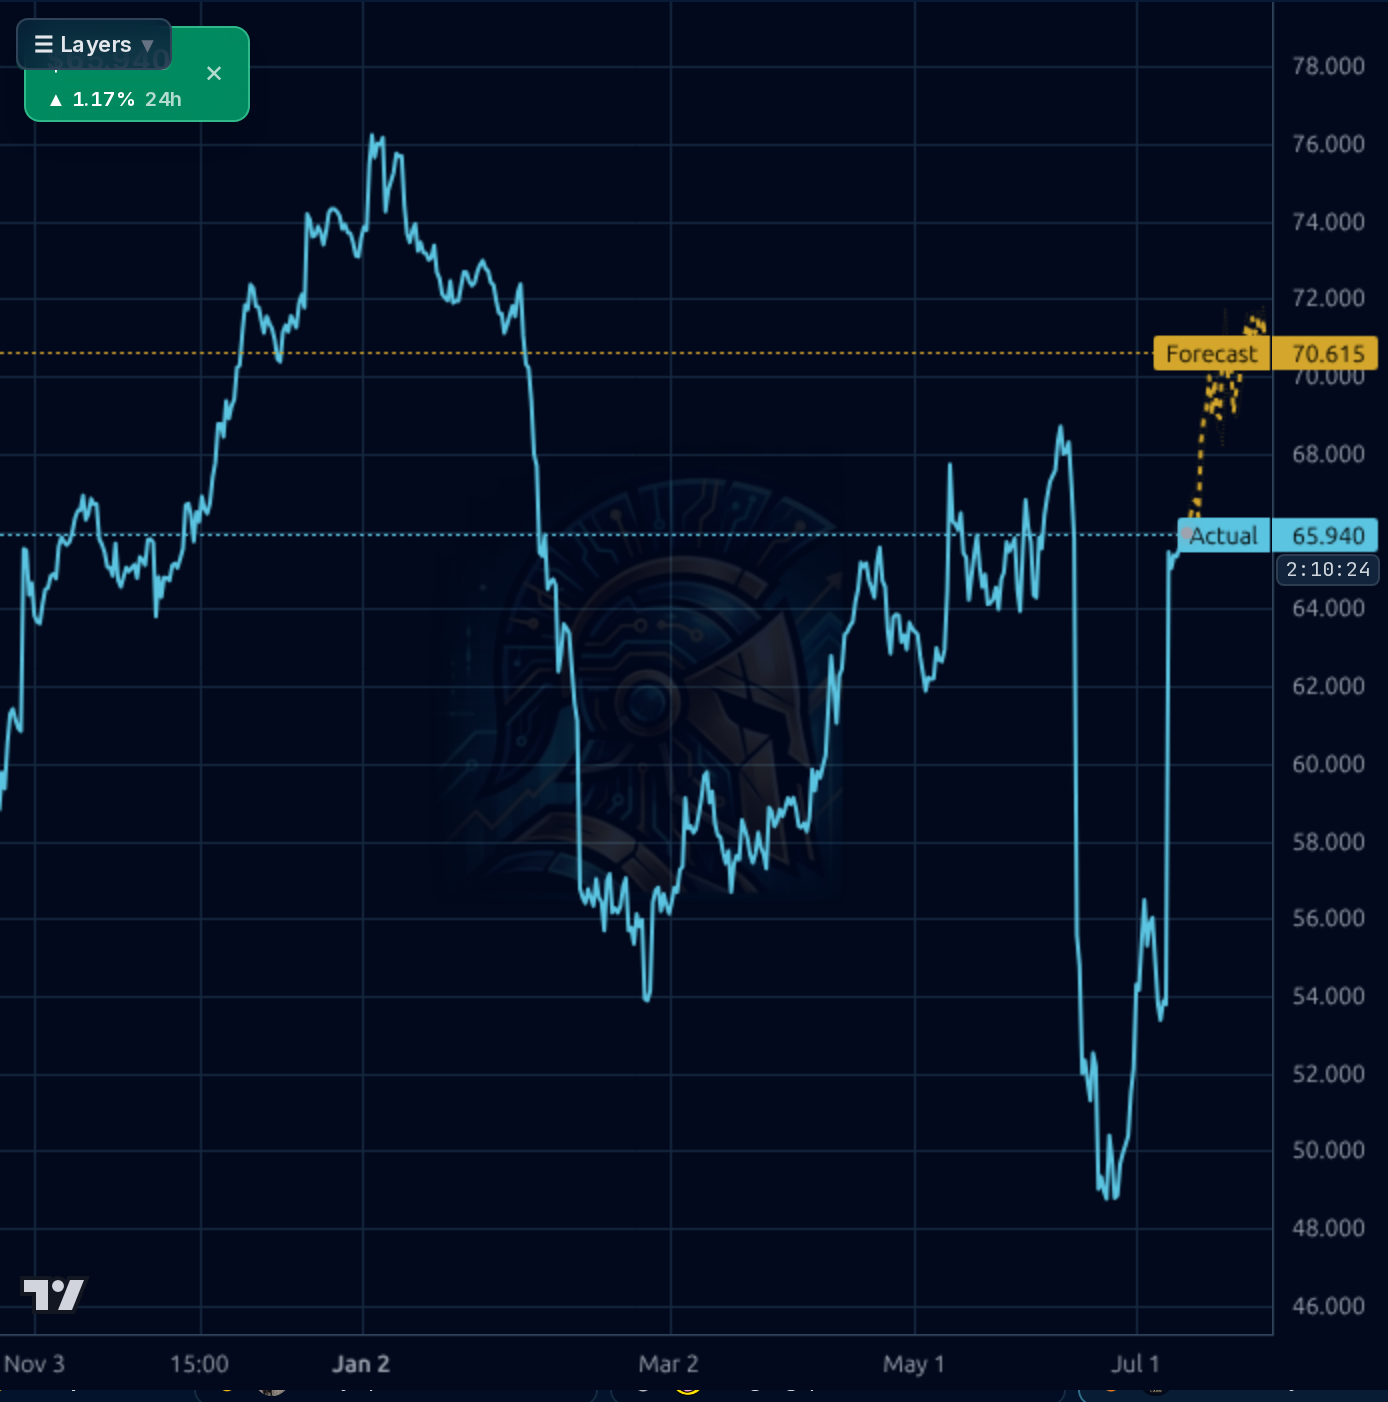
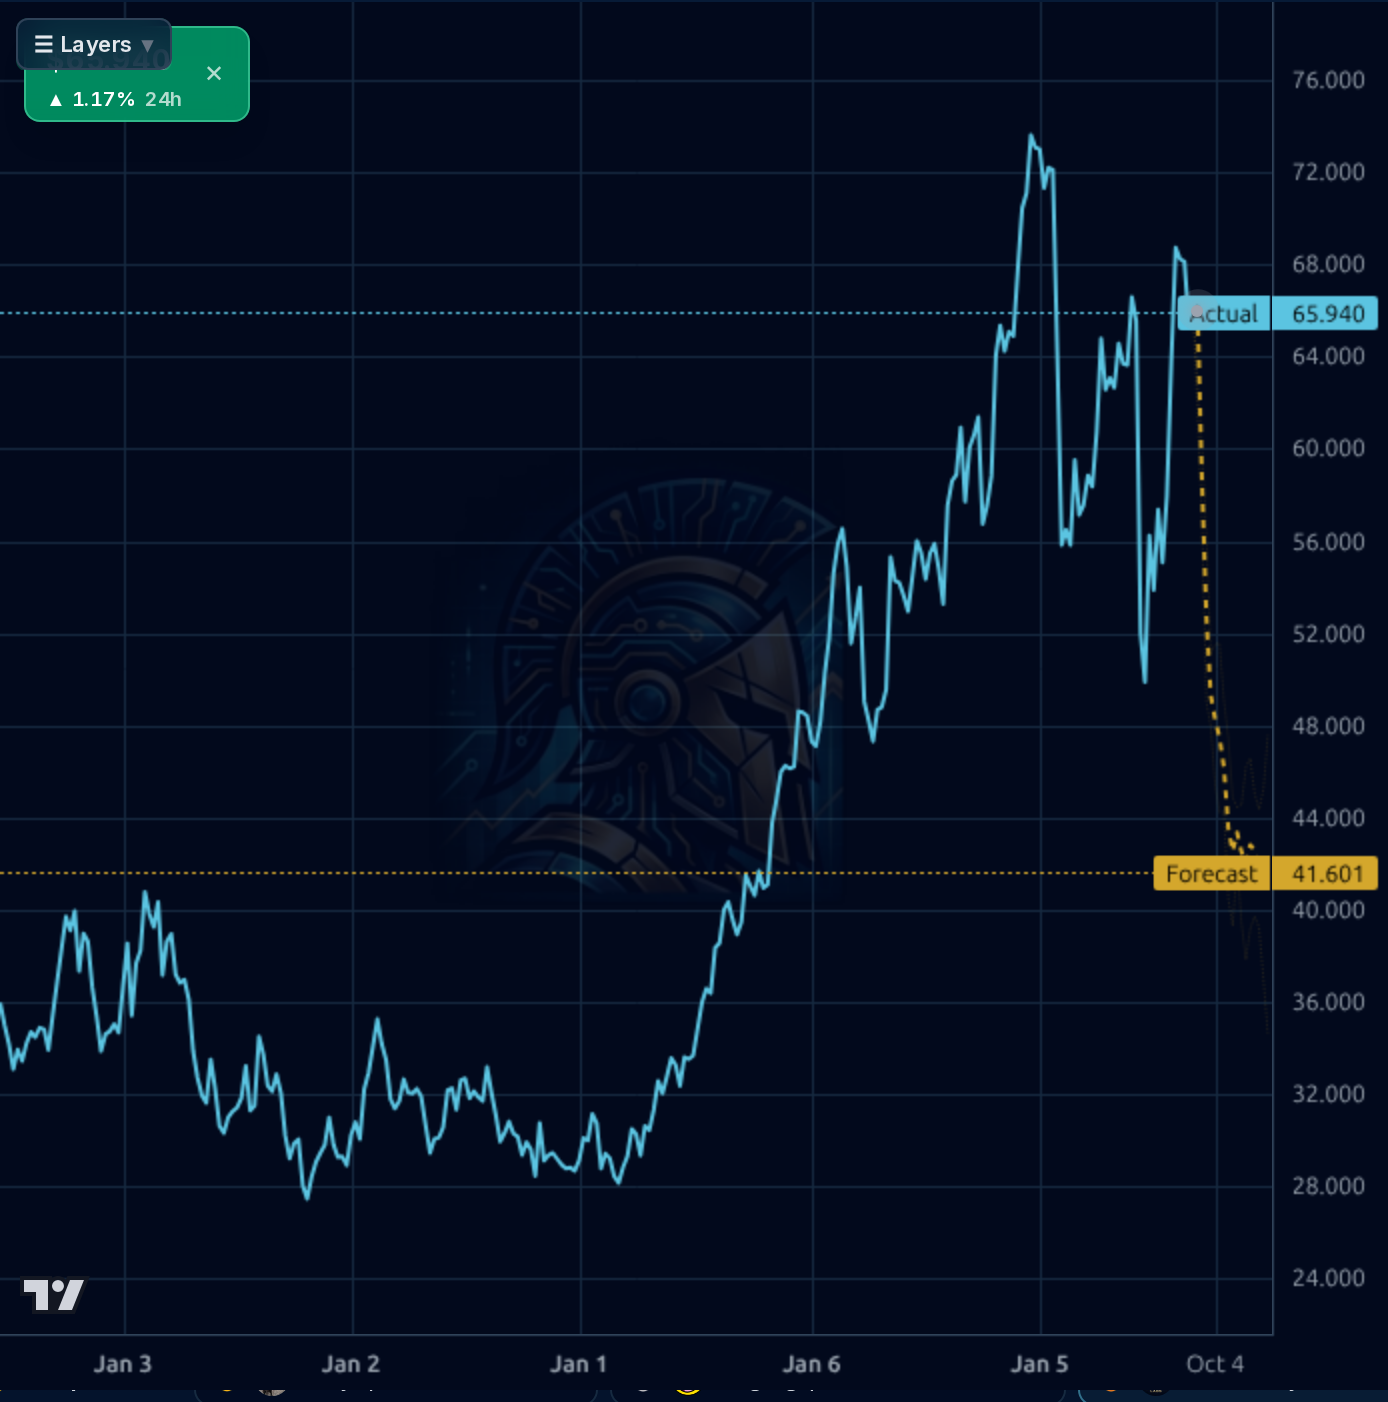
Multi-timeframe picture is constructive but stretched. The 1h chart shows a violent gap-up from ~$54 to ~$65 in early September (post-earnings/upgrade cycle), followed by consolidation in a tight $64-$66 band — classic post-breakout digestion. The 4h chart's forecast band of $70.6 is optimistic and would require breaking the $68 area that capped the November/January highs. The 1d chart is more sobering: price sits just below the multi-quarter resistance shelf ($68-$76) with the model forecasting a mean-reversion pullback to $60.65. The 1wk view forecasting $41.6 is an outlier the realized accuracy data suggests to discount heavily — the 1d model beats naive only marginally (76% vs 78%). Momentum indicators are neutral: RSI 52.4 (mid-range), SMA20 -2.4% (short-term pullback), SMA50 +6.7% and SMA200 +3.95% (intermediate uptrend intact). Key support: $62-64 (breakout base), $58 (SMA50 equivalent). Key resistance: $68 (recent high), $72 (Jan swing), $76.39 (52w high). ATR of 1.85 implies typical daily range ~3%.
Signal: Wells Fargo upgraded to Overweight with an $80 PT (Aug 14) and Guggenheim reiterated Buy at $85 (Aug 25) — a clear positive shift in sell-side posture, consistent with the 2.17 analyst recom and $76.56 consensus PT (16% upside). The dividend hike to $0.29 semi-annual is a shareholder-friendly capital allocation signal. Q4 FY26 earnings featured strong ad demand from live sports (FIFA Men's World Cup, FOX One launch) — real operational catalysts, not financial engineering. The upcoming Goldman Communacopia participation (Sept 9) is a modest visibility event. Noise: The Rupert Murdoch trust settlement ($3.3B) is a governance headline but has no direct impact on FOXA cash flows or strategy — the succession question is now more settled. Retail social sentiment is 100% bearish among tagged messages but is dominated by political/Trump-adjacent noise ($DJT co-mentions) rather than fundamental commentary; treat as contrarian noise, not signal.
- Tubi AVOD platform continues to gain traction as evidenced by management commentary on Q4 call highlighting rapid growth and incremental ad revenue
- FOX One direct-to-consumer streaming launch tied to live sports content is a stated FY27 growth vector
- FIFA Men's World Cup 2026 broadcast rights driving both linear and streaming ad demand — recurring quadrennial catalyst
- Semi-annual dividend increase to $0.29/share signals sustainable FCF generation and shareholder returns
- Forward-year EPS estimate revision turned negative (-14.9pp swing) — the most material fundamental signal in the past 45 days
- Short interest of 23.28% of float / 6.56 short ratio creates two-sided volatility risk; a bearish thesis is being actively expressed by sophisticated capital
- Q1/Q3 seasonal FCF is heavily negative (-$791M in Q2 FY26) — investors unfamiliar with the pattern may react to weak interim prints
- Secular decline in linear TV subscribers pressures affiliate fees; Tubi must scale fast enough to offset
- Market regime is late-cycle with deteriorating breadth (46% >200dMA) — high-beta media names could see multiple compression
- Governance concentration: 53.5% insider ownership limits activist pressure and gives Murdoch family effective control regardless of minority views
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord