HLI — AI Stock Forecast & Price Targets
Published 10/29/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live HLI price forecast →
Houlihan Lokey delivered a strong Q2 FY2027 (revenue $692M, +5% YoY; adj. EPS $1.85 vs ~$1.63 est.) but the stock fell ~5-6% post-earnings on cautious guidance, reflecting deal-flow sensitivity and a stock down ~21% YTD / ~32% off its $204 high. Fundamentals remain high-quality (ROE ~18%, net margin ~16%, low 0.22x D/E, 2% yield), but near-term direction hinges on corporate-finance recovery, and the model's 1-week forecast is unreliable (17% vs 83% naive). Valuation is reasonable on forward terms (fwd P/E ~15.9) but not cheap on trailing (P/E ~23).
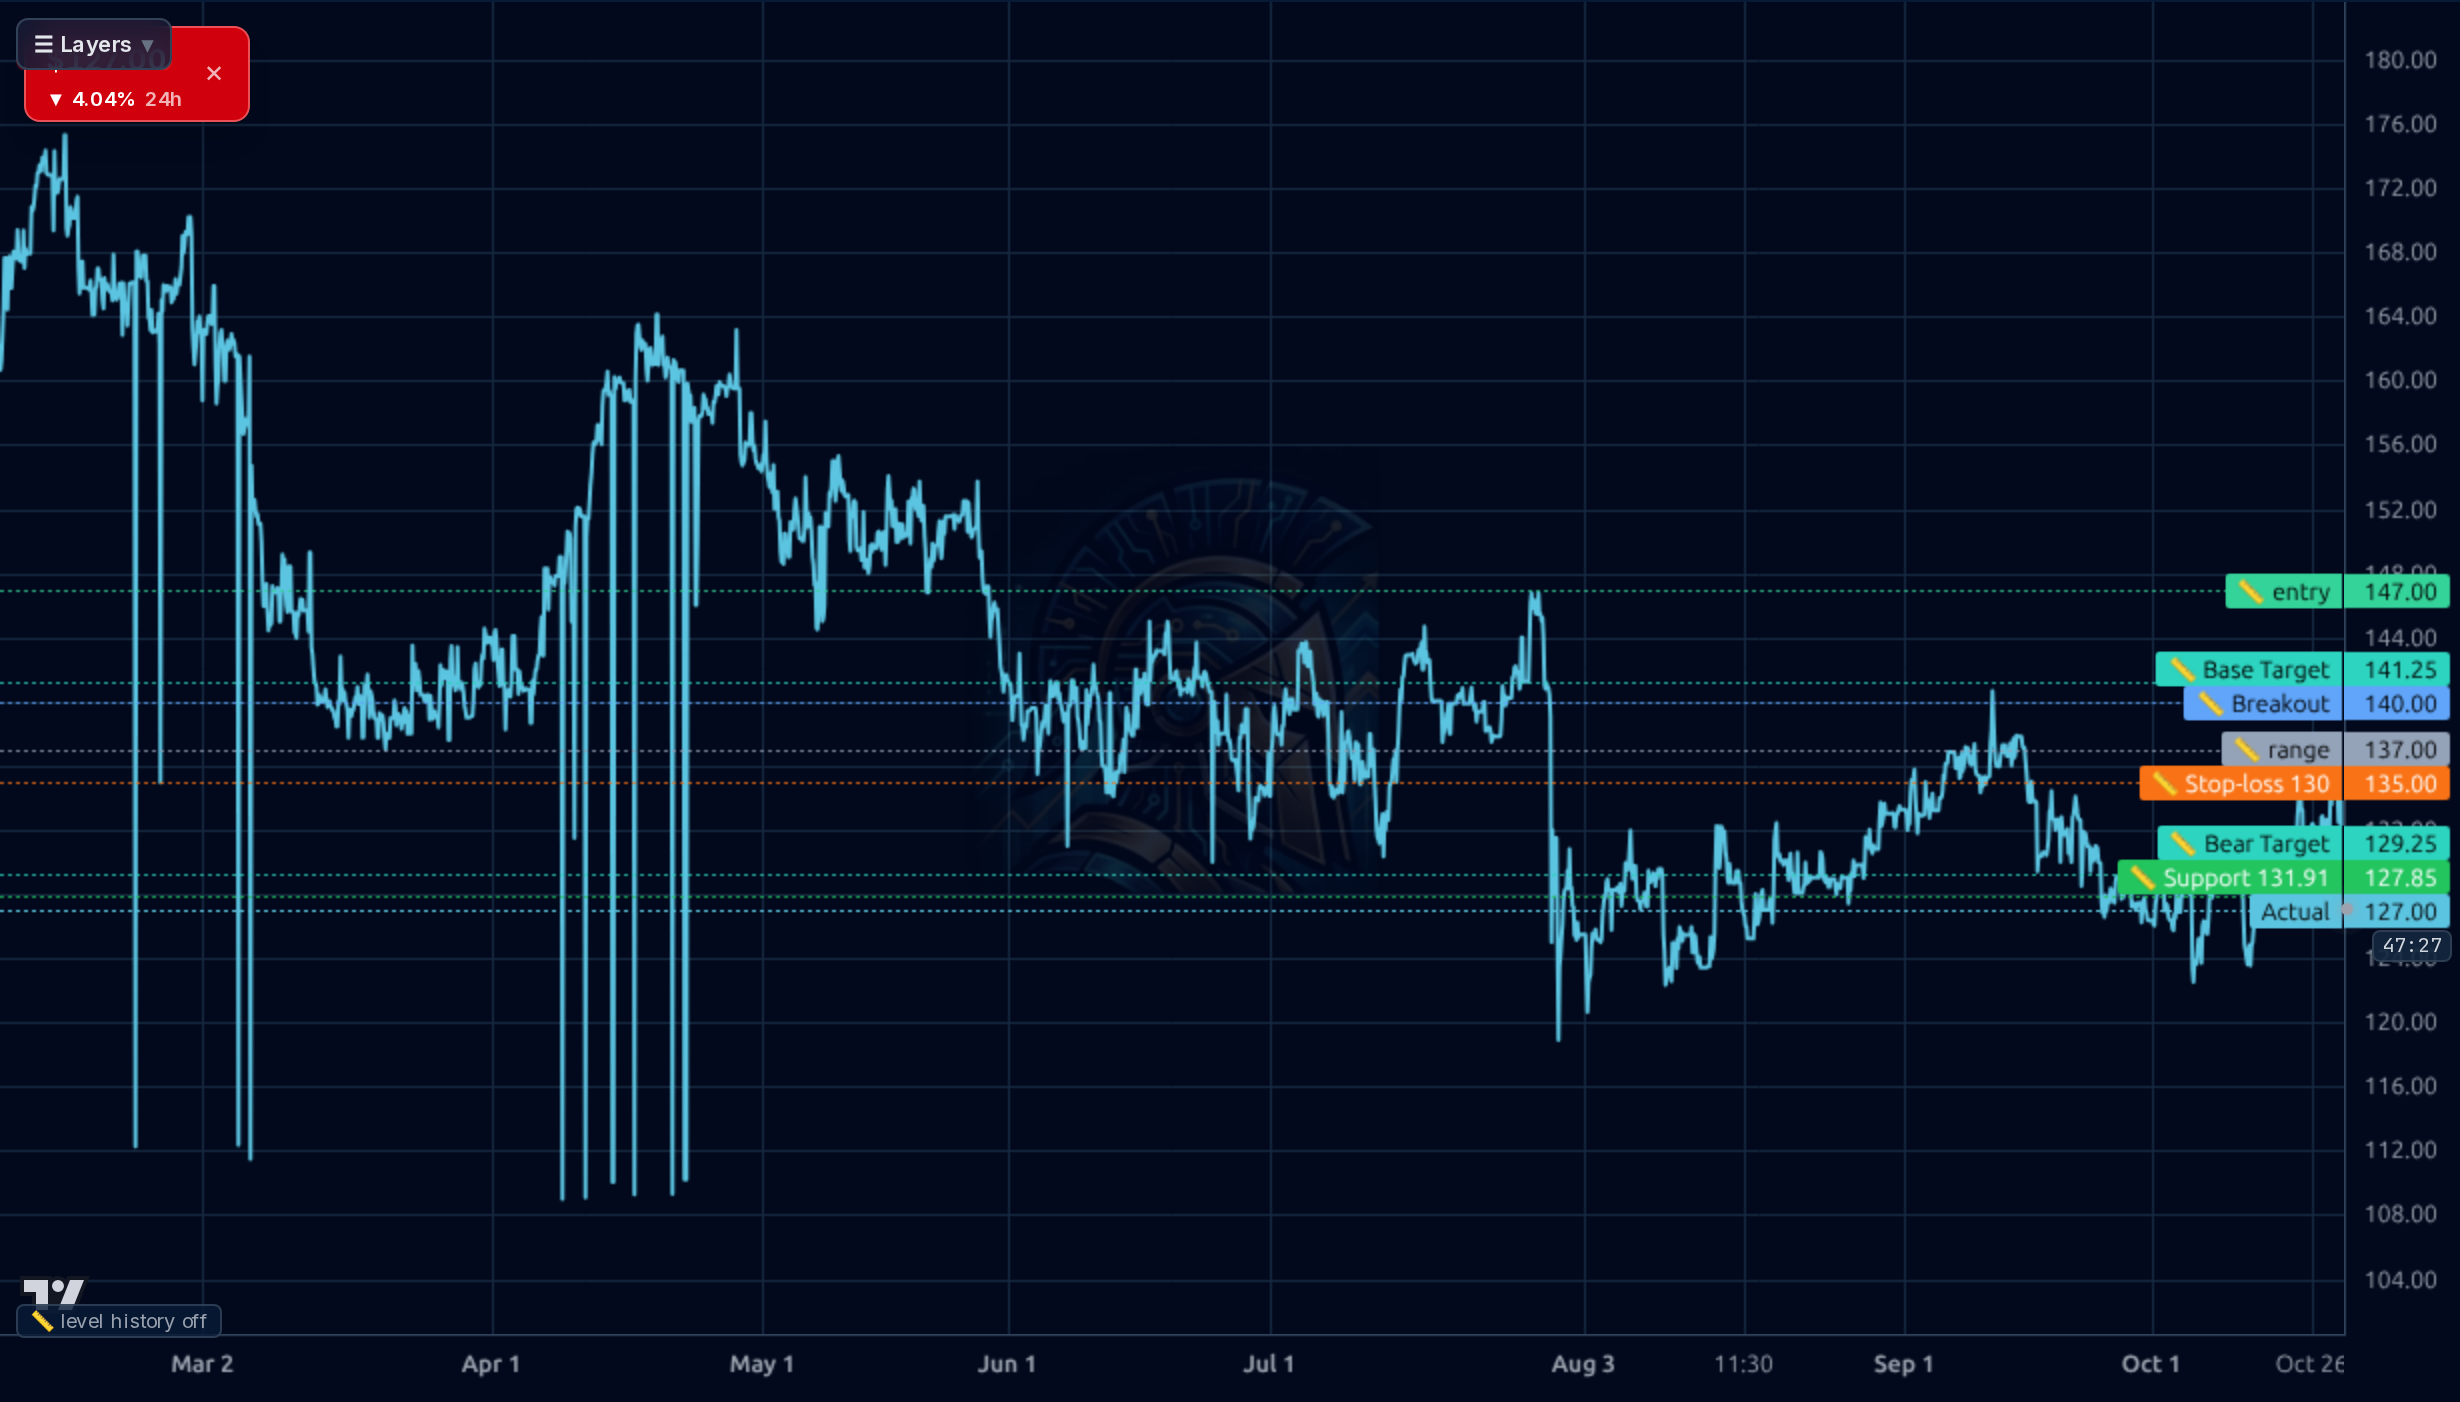
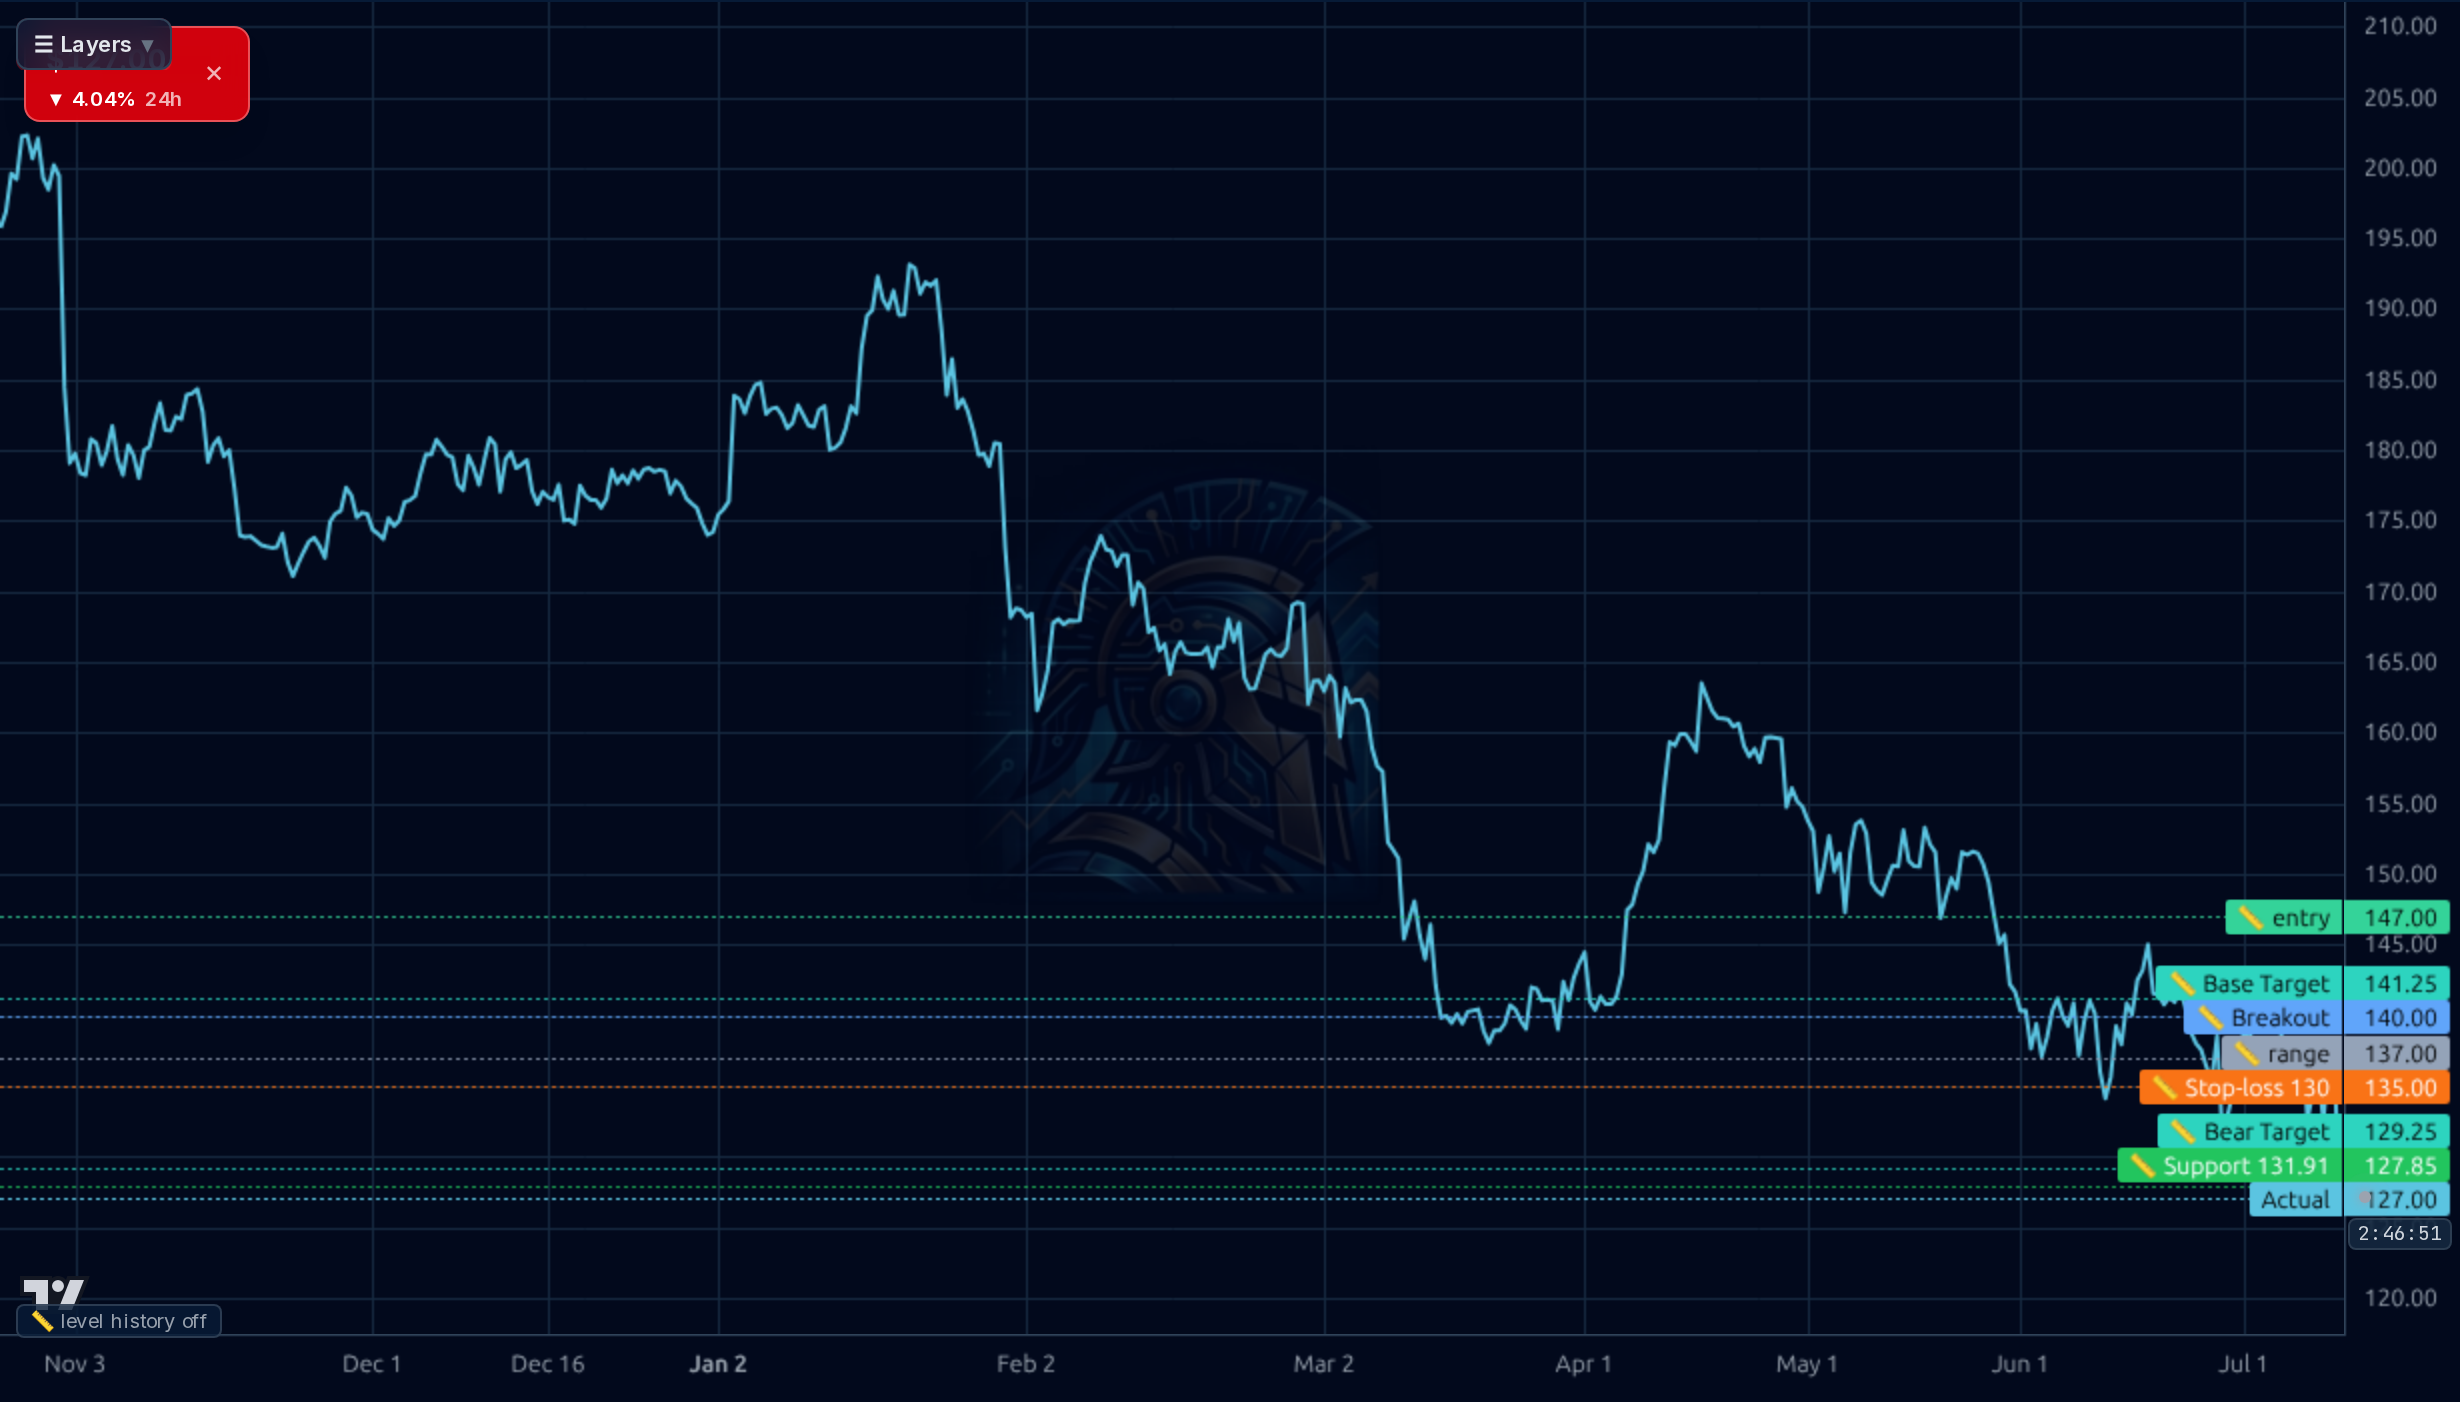
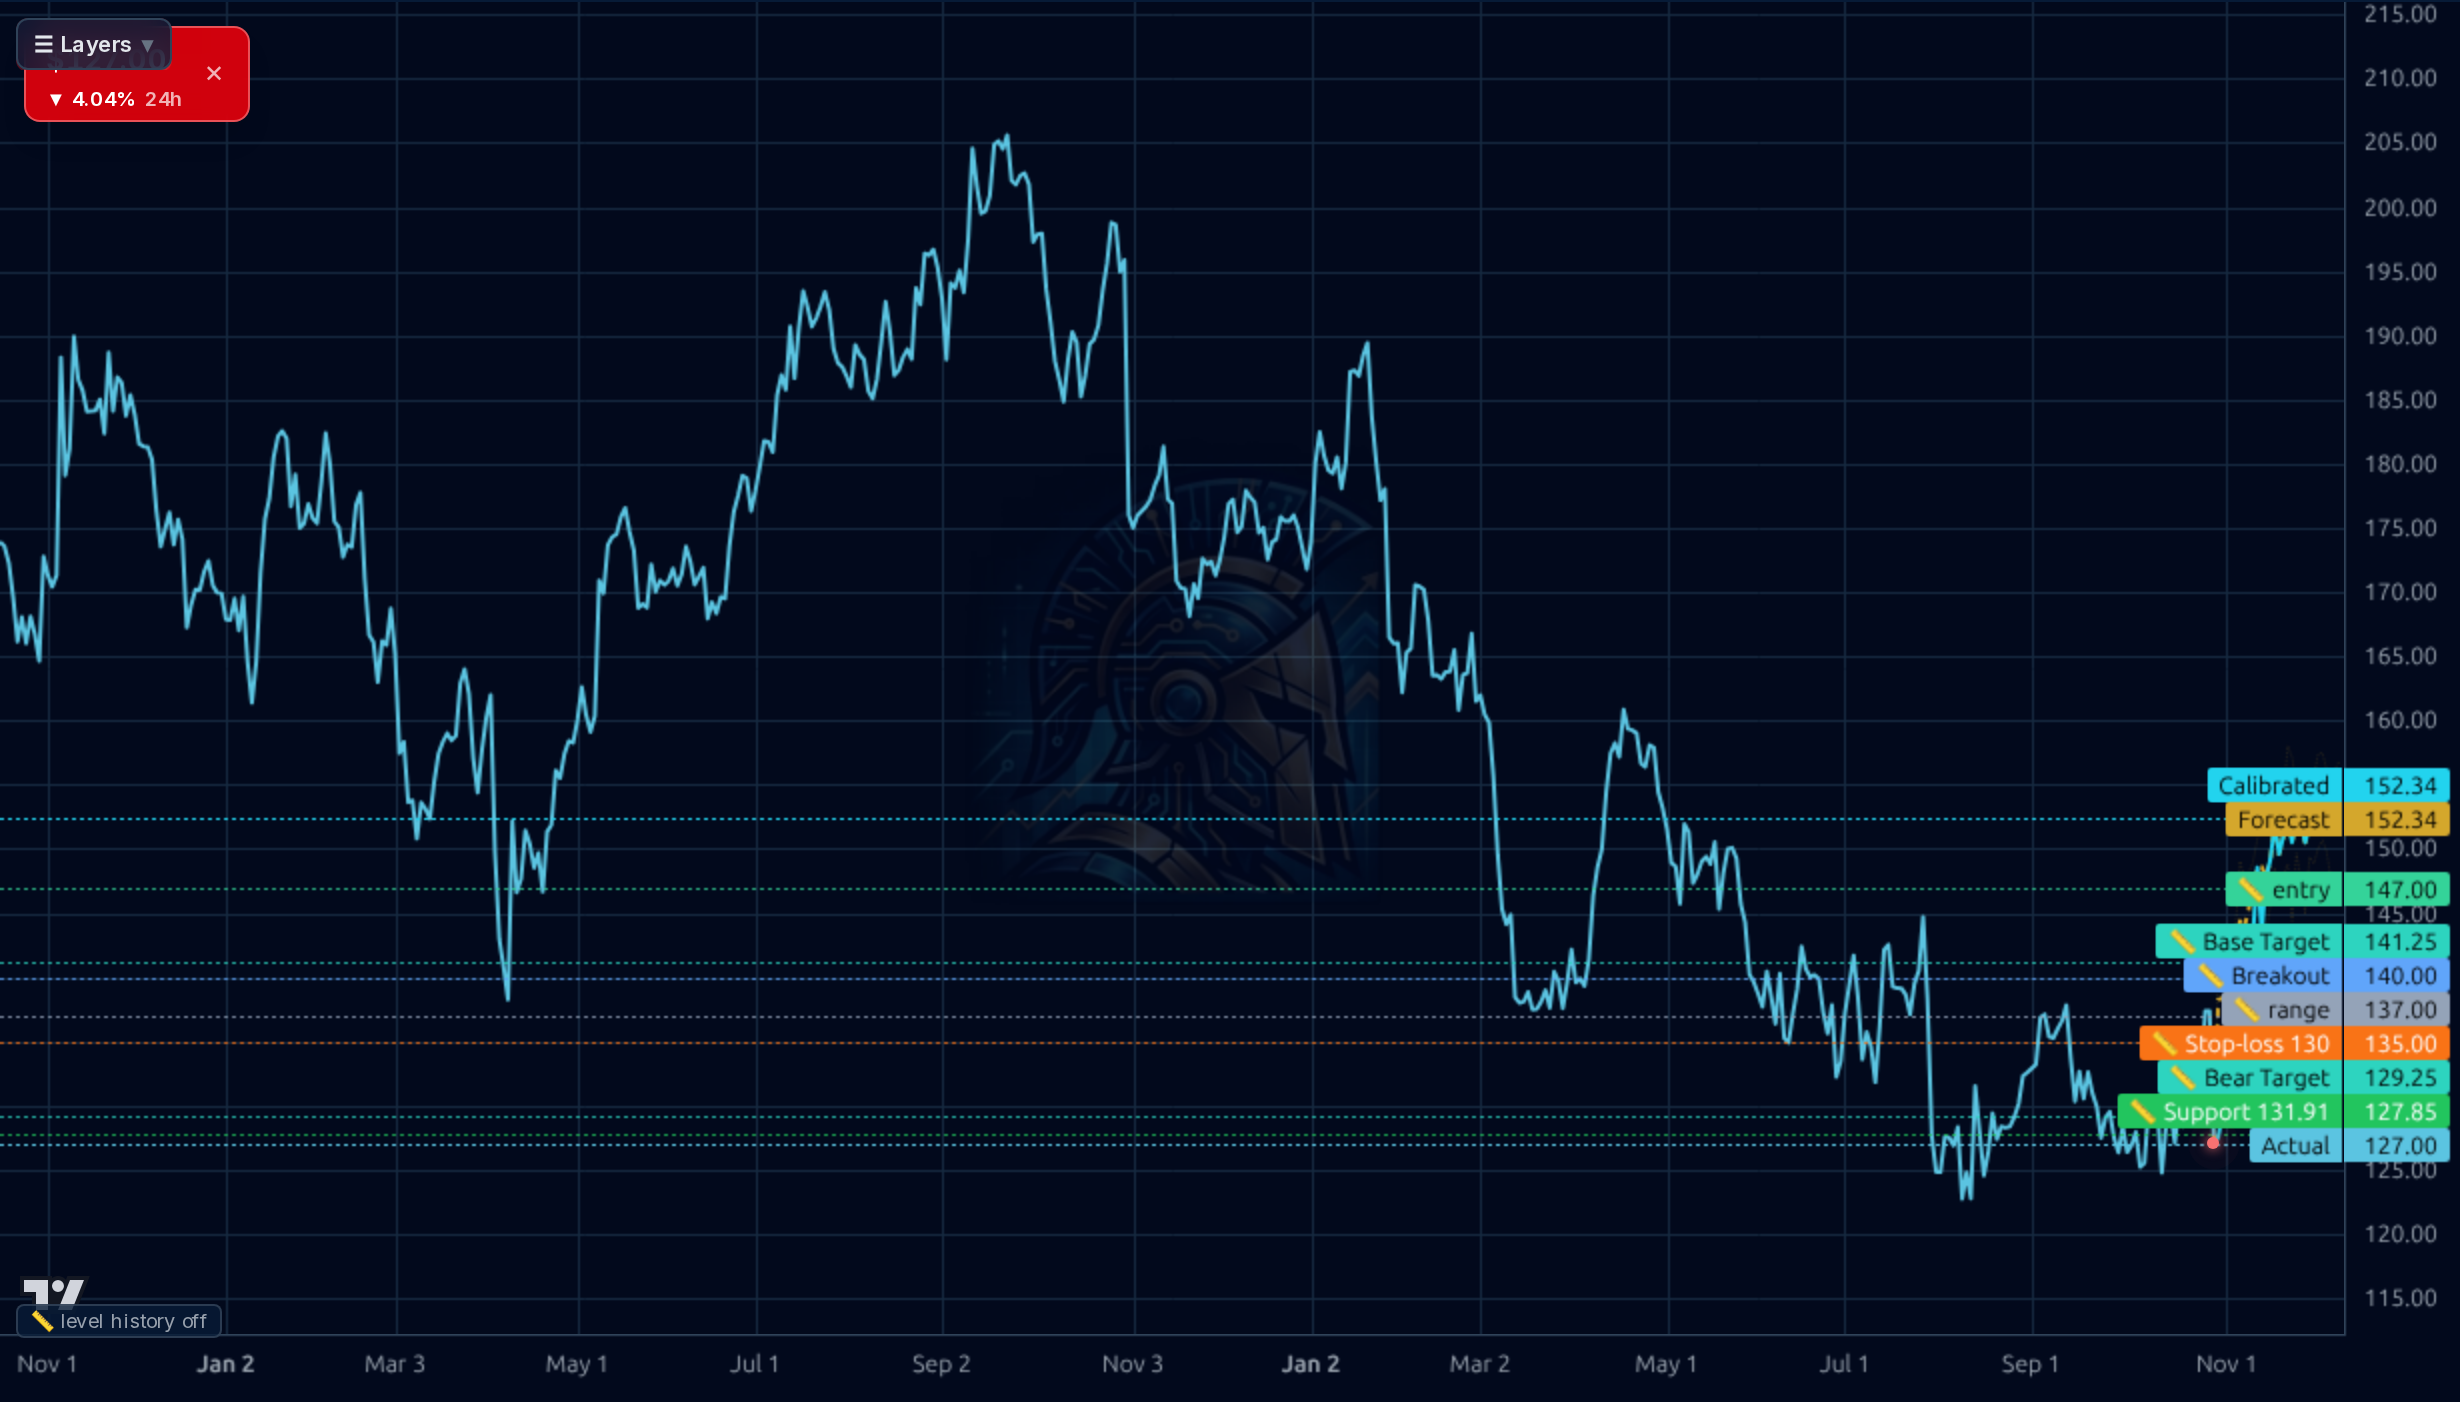
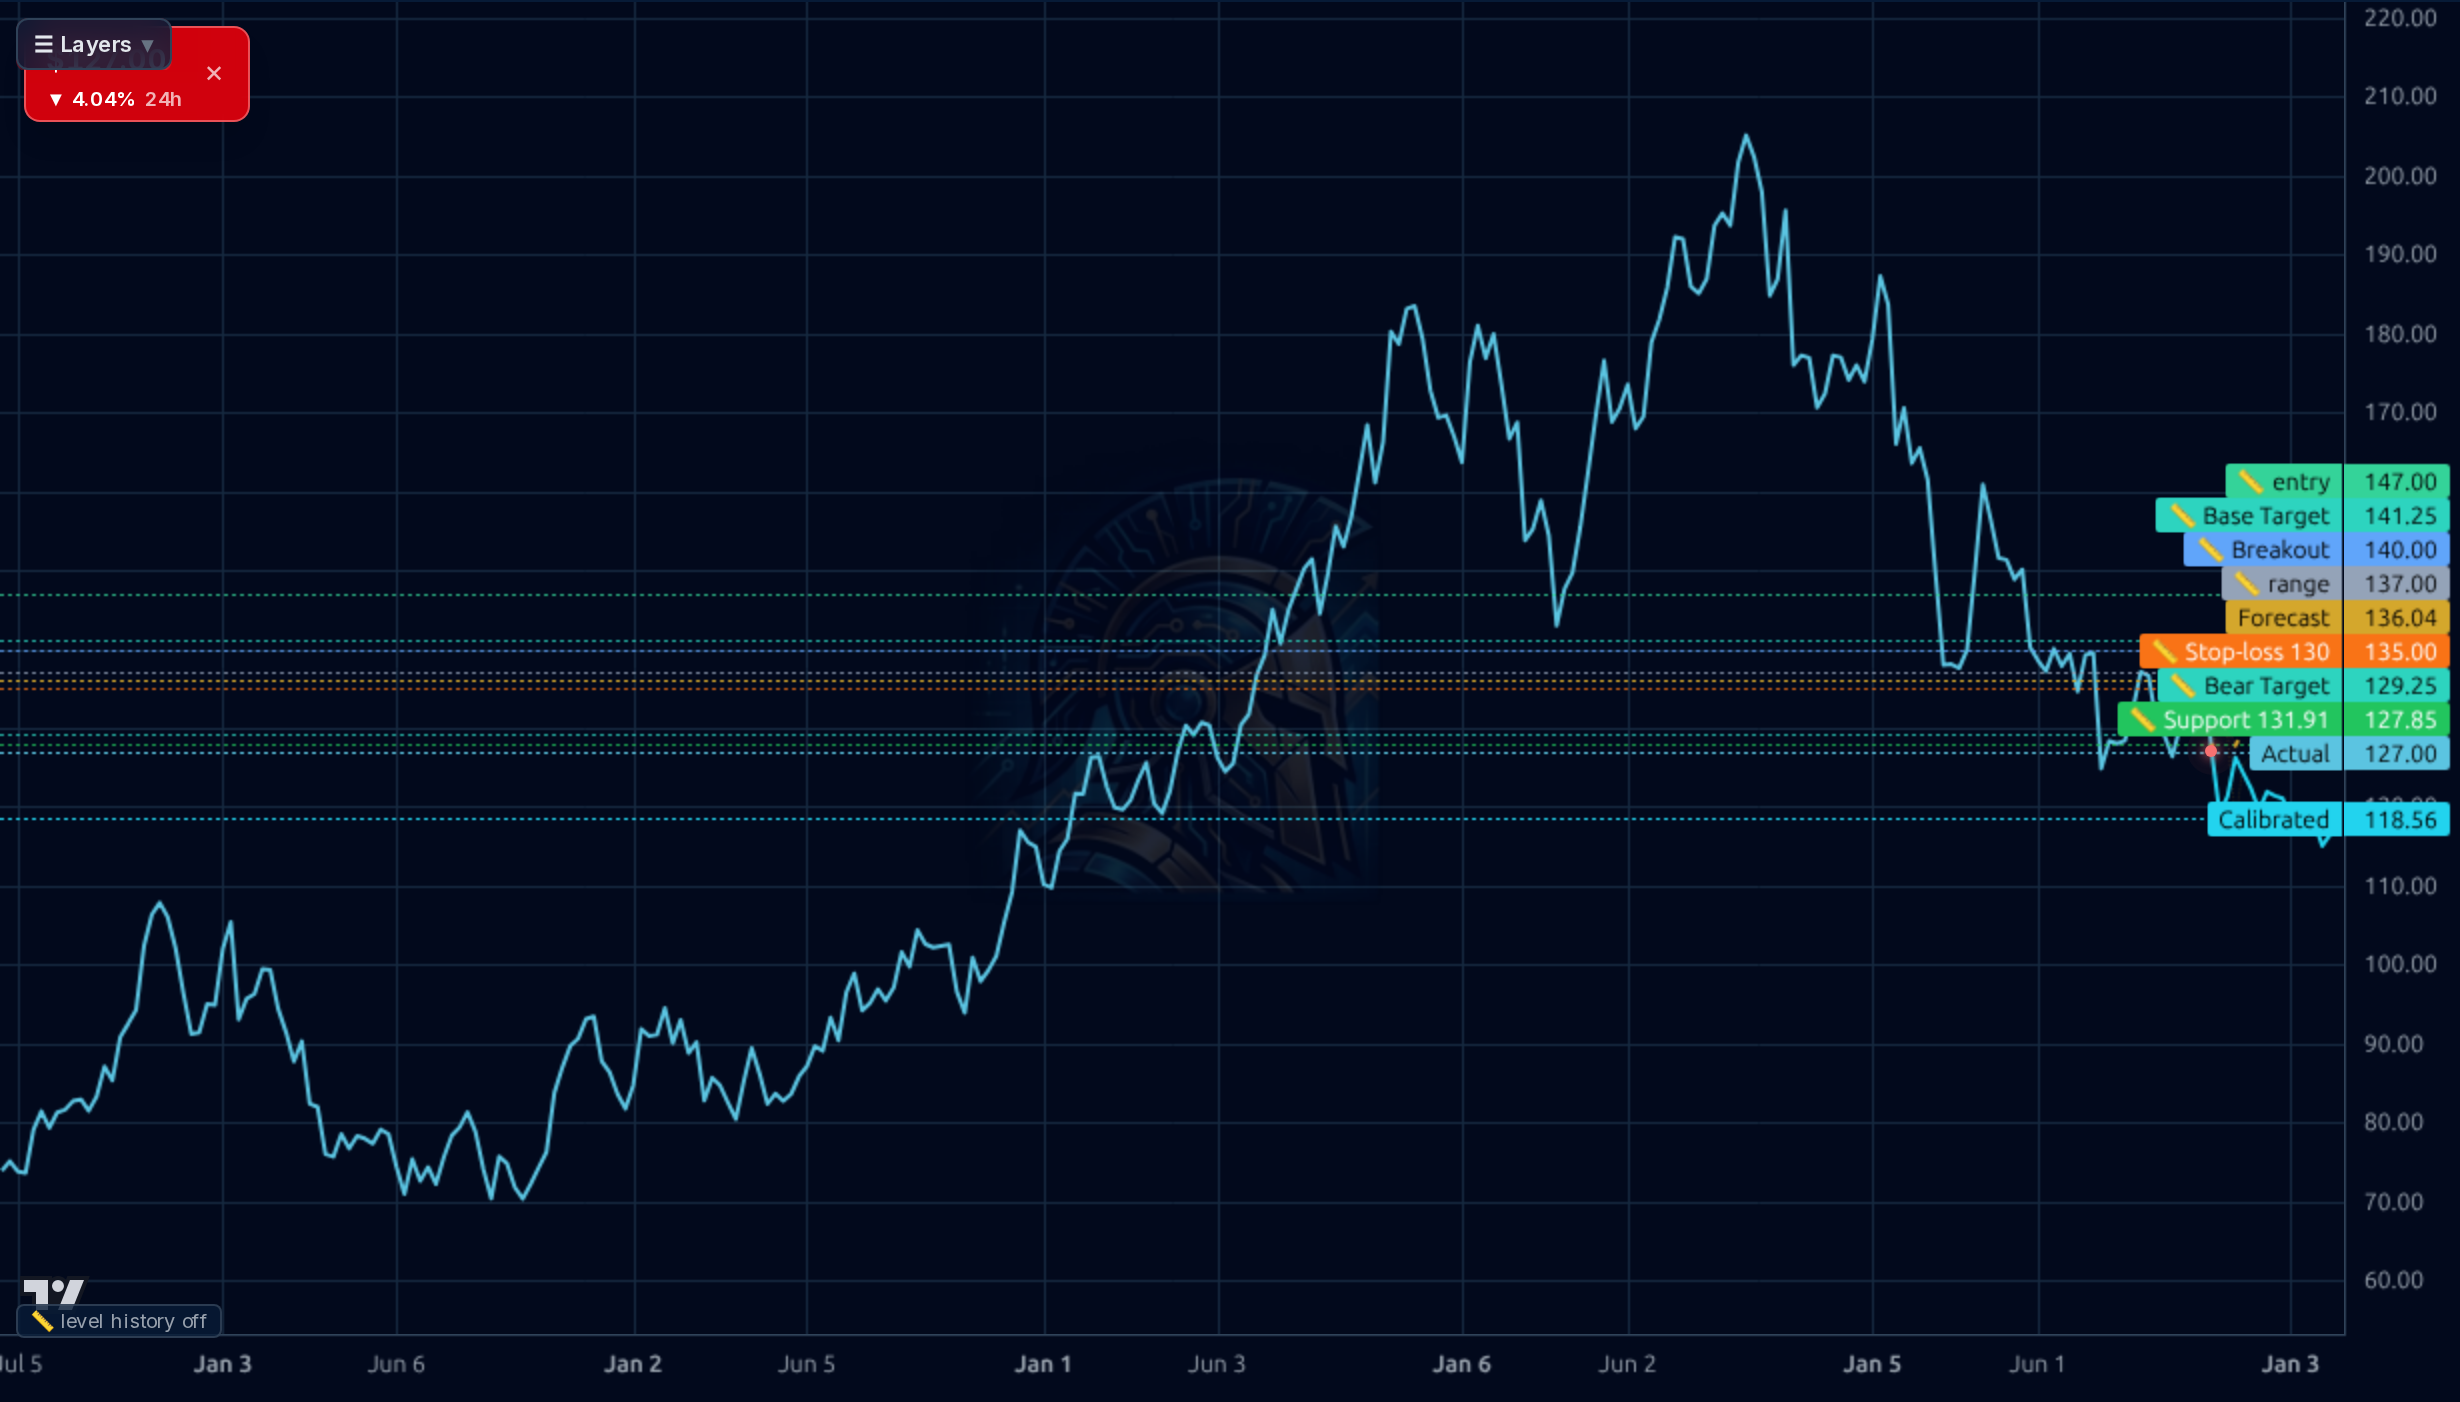
Neutral-to-cautious over 1-4 weeks. The post-earnings negative reaction and unreliable 1wk model argue against chasing. Accumulate on dips toward $130-132 (the $131.91 support / $130 stop zone) with invalidation below $128; a decisive reclaim of $140 then $147 would flip this constructive. Size small until the base confirms. Avoid trading the $137-140 chop without a breakout.
1-6 month view is a cautious BUY if deal-flow recovery materializes. Thesis: Restructuring backlog growth and FVA momentum offset a still-weak Corporate Finance segment; forward P/E ~15.9x leaves room for re-rating. Expected return range ~$135 (bear, if deal market stays soft) to $175 (Citizens target, base case) with a bull extension toward $187. Catalysts: H2 guidance beats, restructuring win activity, M&A/capital-markets recovery. What would change my mind: a return to Q1-style revenue declines or a break below $130 on volume.
1-3 year thesis: HLI's diversified advisory franchise (CF, FR, FVA), high ROE (~18%), and low leverage make it a quality compounder that is highly cyclical to deal activity. Multi-year drivers: the restructuring tailwind, FVA/valuation demand, and inorganic sector expansion (e.g., energy). Biggest structural risk: corporate-finance revenue is boom-bust and sensitive to interest rates and market liquidity; a prolonged low-deal environment keeps the stock capped and volatile around earnings.
Q2 FY2027 (quarter ended Sep 30, 2026) was a clear beat: revenue $692M (+4.9% YoY), adjusted EPS $1.85 (12.1% above consensus), GAAP net income $109M / $1.64 diluted. Trailing metrics are solid — profit margin ~16.1%, operating margin ~18.4%, ROE ~17.8-18.3%, ROA ~11.2%, and a strong balance sheet (cash $745M vs debt $493M, D/E 0.22, current ratio 1.63). Dividend is sustainable at ~2% yield with a ~38-47% payout. The weakness is in the trajectory: Q1 FY2027 revenue fell ~15.5% YoY to $511M with adjusted EPS nearly halved ($1.35 vs $2.14), signaling a soft Corporate Finance environment; Q2 sales still fell -15.7% QoQ and EPS -18.5% QoQ. Cash flow quality is mixed — Q1 FY2027 operating cash flow turned negative (-$336M) with negative FCF (-$342M), though Q2 recovered to +$293M OCF. Capital allocation is disciplined (low leverage, buyback-capable). What's working: Restructuring backlog and FVA momentum per Citizens; what's broken: Corporate Finance cyclicality and the market's refusal to reward the beat.
On the 1d chart, HLI is in a clear downtrend off the ~$204 high, bottoming in the low-$120s and bouncing ~3.8% on the day to $137.38. Immediate support sits at the $131.91 (labeled 'Support 131.91') and $130 stop-loss zone, with the $135-138 area (prior deep-research support) now acting as a pivot-turned-support after the bounce. Resistance overhead: the $137 'range' line, then the $140 'Breakout' level, and the $147 'entry' zone. The Calibrated forecast (152.34) sits well above price, implying upside if the recovery thesis holds; the amber Forecast line reads ~136.04, roughly at current price. Momentum is neutral-to-improving (RSI 62, price +6.31% above SMA20, +5.06% above SMA50, but -5.28% below SMA200). The 1wk forecast is unreliable — directional accuracy 17% vs 83% naive baseline, so discount it. Key invalidation is a break below $130/$131.91; a reclaim of $140/$147 would signal a genuine base.
Signal: HLI beat Q2 FY2027 on both revenue ($692M, +5% YoY) and adjusted EPS ($1.85 vs ~$1.63 est.), and Citizens upgraded to Outperform with a $175 target citing strengthening Restructuring and FVA pipelines and record backlog. Management flagged an expected stronger-than-normal second half with improving deal activity. Noise: despite the beat, the stock fell ~5-6% pre-market on Oct 29 on cautious commentary, and several banks cut targets in October (Morgan Stanley $177→$165, BofA $152→$150, KB $153→$150) while others raised (UBS $147→$154, Goldman $148→$153). Analyst targets span ~$147-187, reflecting a split Buy/Hold consensus. Insider activity is mildly constructive (CFO Alley bought $501K in Aug; GC Crain sold $140K in Sep). The negative price reaction to a beat is the dominant theme — upside may be largely priced in near-term.
- Restructuring pipeline growth: Citizens cited a strengthening outlook with record backlog and new-business wins, a durable revenue source even in soft M&A markets.
- FVA (Financial and Valuation Advisory) momentum: growing backlog and pitch activity ahead of last year, supporting revenue diversification beyond deal-fees.
- Corporate Finance recovery: management signaled a stronger-than-normal second half with improving deal activity — the key swing factor for revenue re-acceleration past Q2's +5%.
- Inorganic expansion: strategic acquisitions (e.g., energy coverage) and new MDs added in Equity Capital Solutions, Financial Services, and FinTech/Digital Assets to broaden sector reach.
- Valuation re-rating: forward P/E ~15.9x vs a ~23x trailing multiple leaves room for multiple expansion if earnings trend upward.
- Deal-flow sensitivity: revenue and earnings are highly cyclical; Q1 FY2027 revenue fell ~15.5% YoY, and Q2 sales fell -15.7% QoQ.
- Post-earnings negative reaction: the stock fell ~5-6% despite a beat, indicating upside may be priced in and guidance dominates the tape.
- Analyst split: targets range $147-187 with mixed Buy/Hold ratings and several October target cuts (Morgan Stanley, BofA, KB).
- Macro/interest-rate headwinds: higher-for-longer costs pressure private-market dealmaking, exits, and advisory demand; management specifically flagged software-sector risk.
- Valuation: trailing P/E ~23x and P/B ~4.3x are not cheap on a cyclically-troughed earnings basis (PEG ~2.08).
- Cash flow volatility: Q1 FY2027 operating cash flow turned negative (-$336M) with negative FCF, though Q2 recovered.
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord