IBN — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live IBN price forecast →
ICICI Bank has sold off to $28.40, breaking the prior $28.50 support flagged in earlier work, but the underlying franchise remains high-quality: 40%+ net margins in the June quarter, ROE ~16%, forward P/E ~14.6 with a PEG under 1, and a Street consensus recommendation of 1.11 with a $36.61 target. With RSI at 36, price sitting below all key SMAs, and Kronos forecasts pointing to a modest mean-reversion bounce (~$29.4-$29.8) rather than a durable trend change, this is an accumulate-on-weakness setup into the Oct 17 earnings print, not a chase.
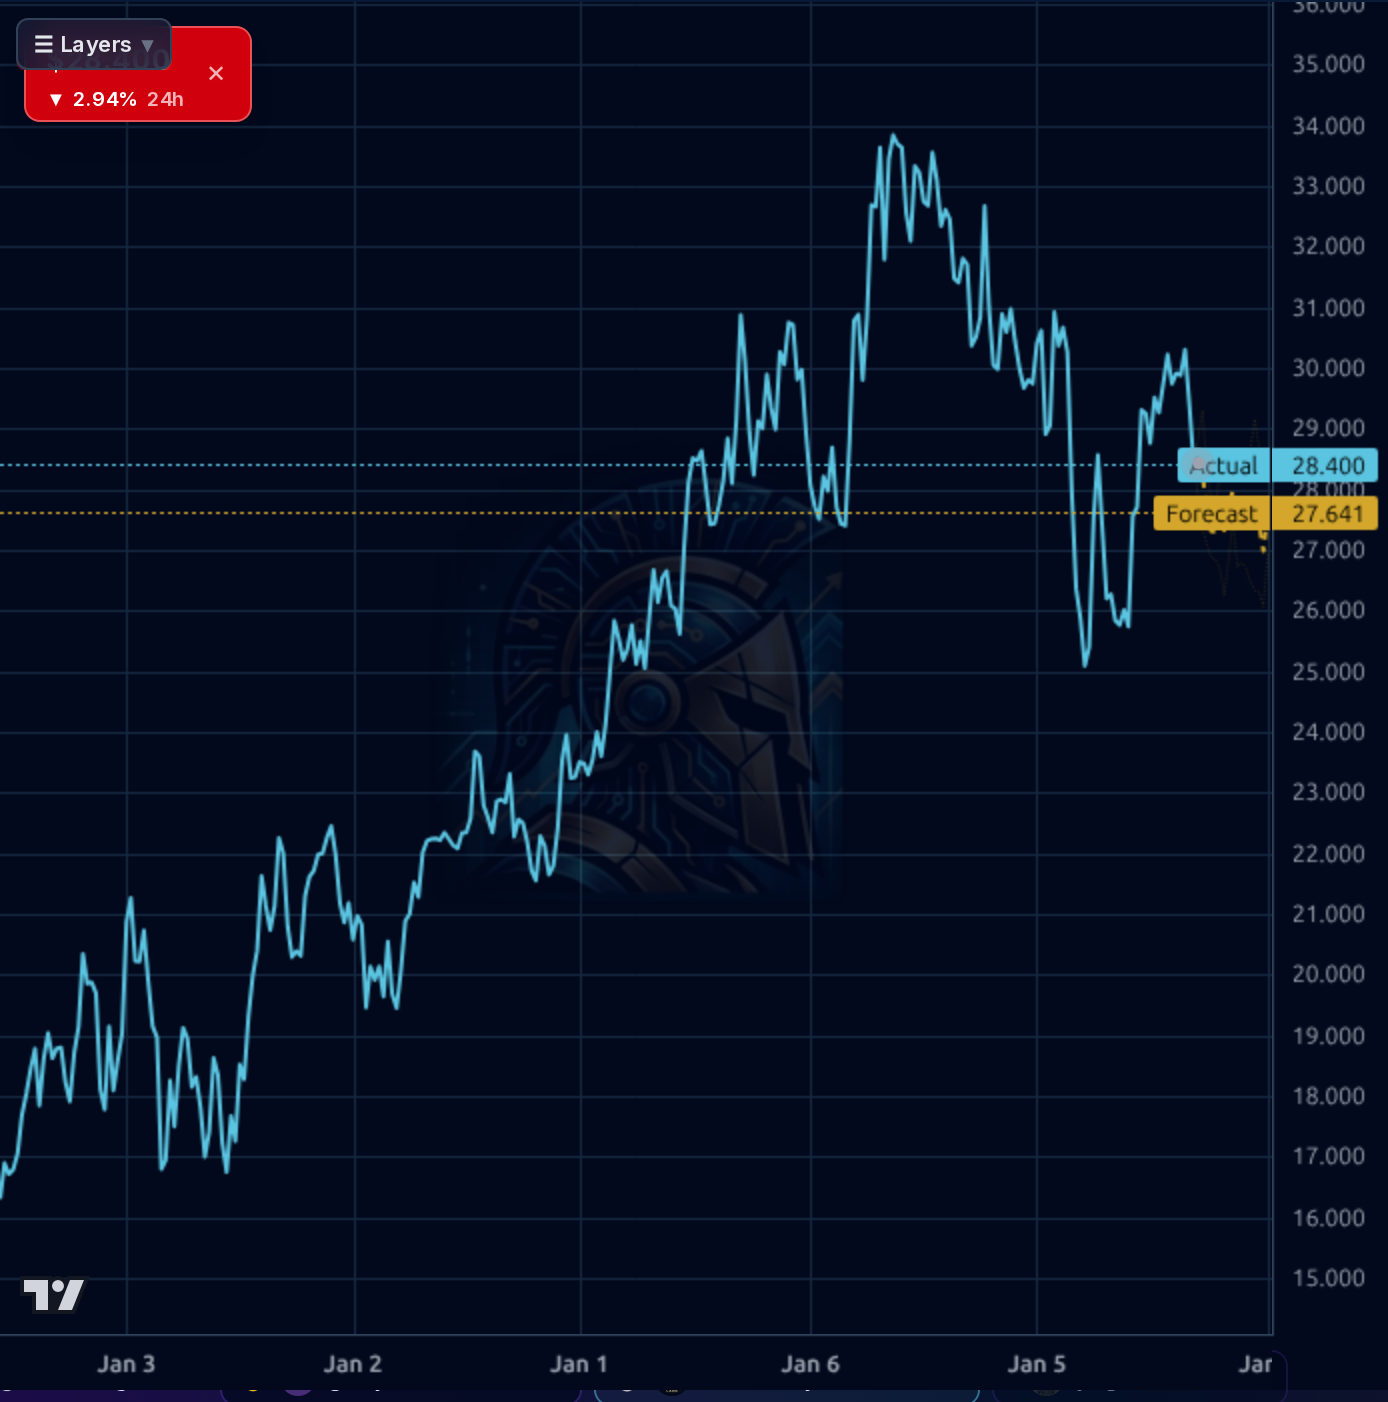
1-4wk: Accumulate in the $28.00-$28.50 zone with a stop below $27.50 (which would break the multi-quarter consolidation floor and open the door to the $27.00-$27.60 area shown on the 1W chart and Kronos long-horizon forecast). Kronos short-term band $29.4-$29.8 is the first realistic upside; $30.20 (prior range midpoint) is the second. Do NOT hold a full position through the Oct 17 earnings print — this is a binary event ~32 days out; either trim into a bounce toward $29.5-$30 before the report or size the initial entry small (¼ to ⅓ of intended size) so an earnings gap is survivable. Invalidation: daily close below $27.50 or a break of the June-2025 low of $25.08.
1-6mo: Base case is that Q2 FY27 earnings on Oct 17 confirm the margin/NII acceleration seen in the June quarter, which should re-rate the stock back toward the $31.50-$33 range (the top of the 12-month range) — roughly +11% to +16% from spot. Bull case is a clean beat plus commentary on the AMC's ~10% stakes in other banks being deployed accretively, taking the ADR to $34-36 (close to Street consensus $36.61). Catalysts: Oct 17 earnings, any update on the $1B bond issuance, RBI rate path, and INR/USD (ADR-specific FX drag). What would change my mind: NIM compression, credit costs rising materially, or a break of $27.50 on volume.
1-3yr: ICICI remains a structural compounder in the Indian private-banking oligopoly with 15-17% sustainable ROE, mid-teens EPS growth (EPS next 5Y consensus 15.3%), and optionality from life insurance, general insurance, AMC and securities subsidiaries. At current forward P/E ~14.6 and P/B 2.53, the stock is not cheap but it is not expensive relative to its return profile. A 3-year fair value in the low-to-mid $40s (~15x forward EPS on ~$2.30 EPS) is defensible if credit quality holds. Biggest structural risk is not company-specific but sovereign/macro: an INR devaluation cycle, an Indian credit downturn, or a change in the RBI's regulatory posture toward large private banks would compress both earnings and the multiple simultaneously.
The income statement is the clear positive: quarterly revenue has stepped up sequentially from ₹346B (Sep-25) → ₹353B → ₹357B → ₹384B (Jun-26), with net income rising from ₹133B to ₹154B and net margin expanding to 40.2% in the latest quarter — best of the last four. TTM ROE of ~15.7% and ROA ~2.0% are best-in-class for a large lender, and equity has grown from ₹3.36T to ₹3.81T over four quarters, indicating steady internal capital generation. Balance sheet: total assets ₹30.0T against ₹2.26T of debt and ₹1.96T cash — the leverage picture is normal for a bank and the book/share of $11.21 gives a P/B of 2.53, which is a premium but justified by the ROE profile. Valuation is reasonable: trailing P/E 16.66, forward P/E 14.59, PEG 0.95 with EPS growth expectations of ~15% next year and past 5Y growth 18.5%. Dividend yield ~0.9% with a low 12% payout leaves ample room for reinvestment. The main watch-item flagged previously — operating expense creep — is not visible in the reported operating margin of 38.5% / 24.8% (Finviz), but Q/Q sales growth of -3.4% (TTM basis) and EPS Y/Y TTM -1.7% show the growth has been lumpy, so the June acceleration needs confirmation in October.
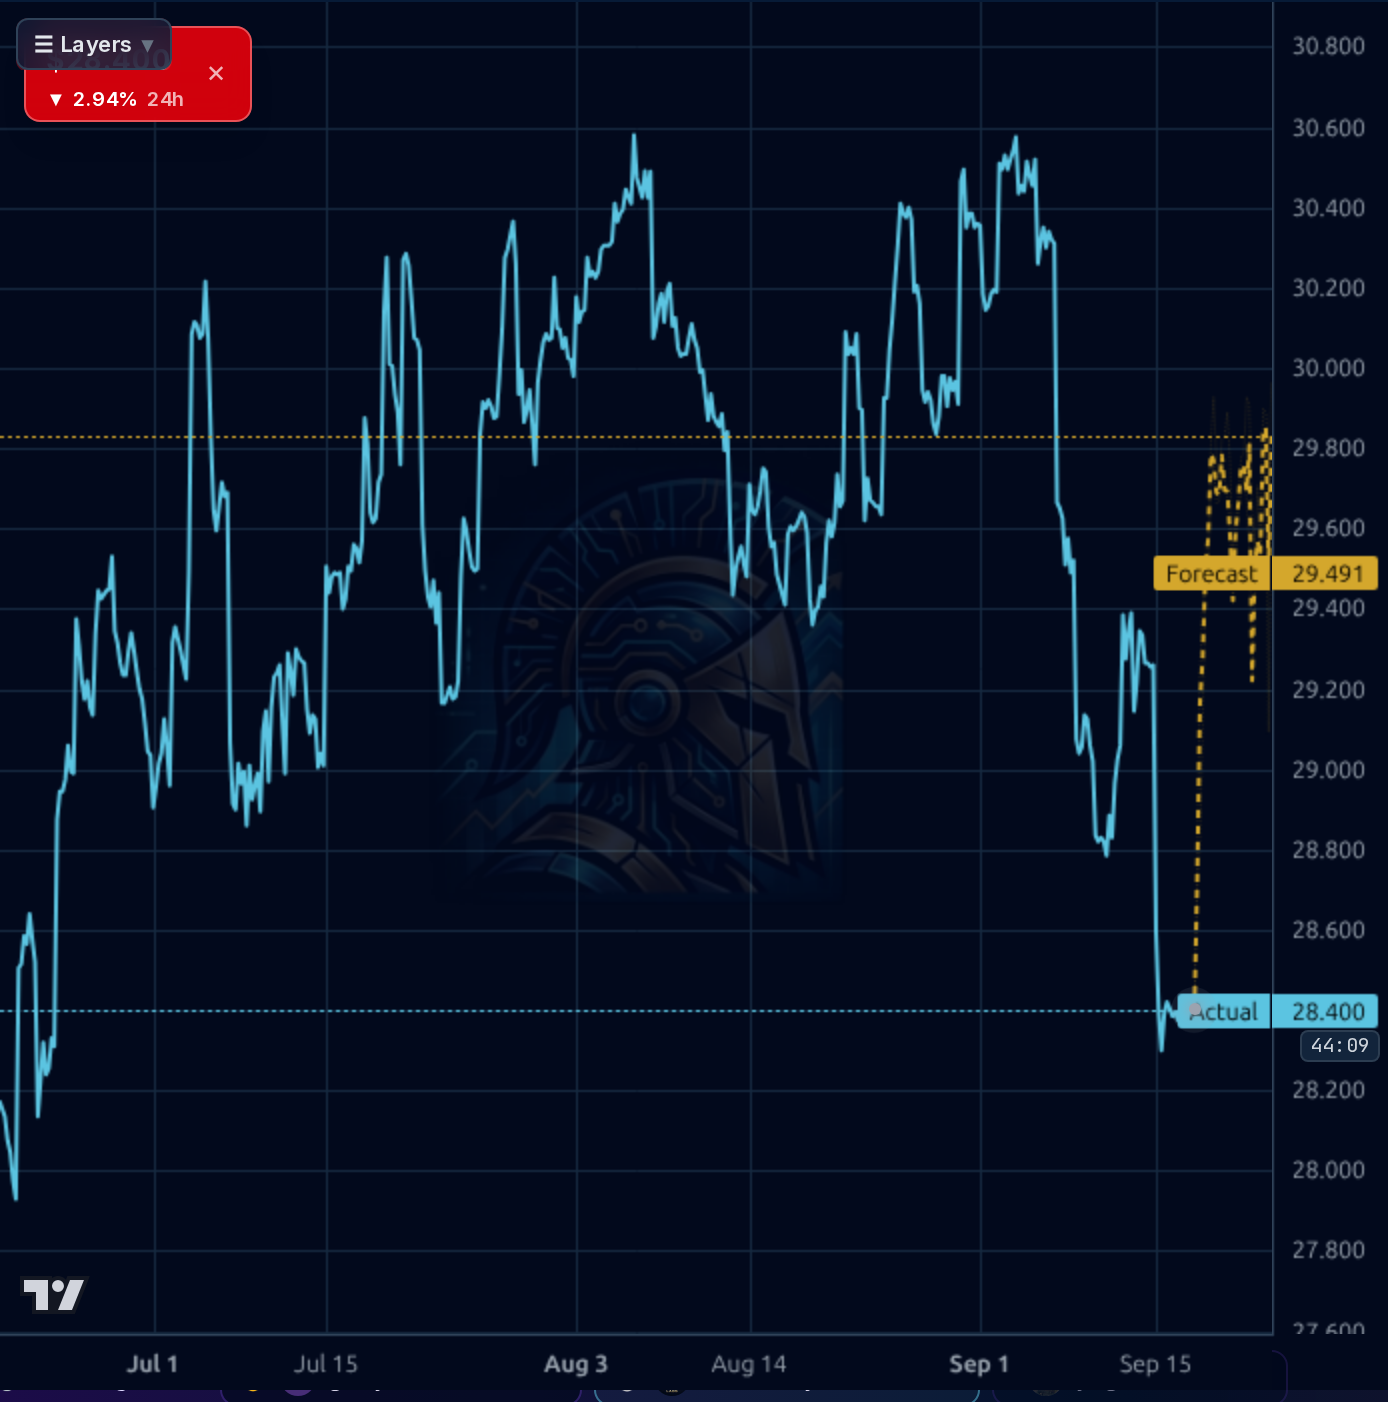
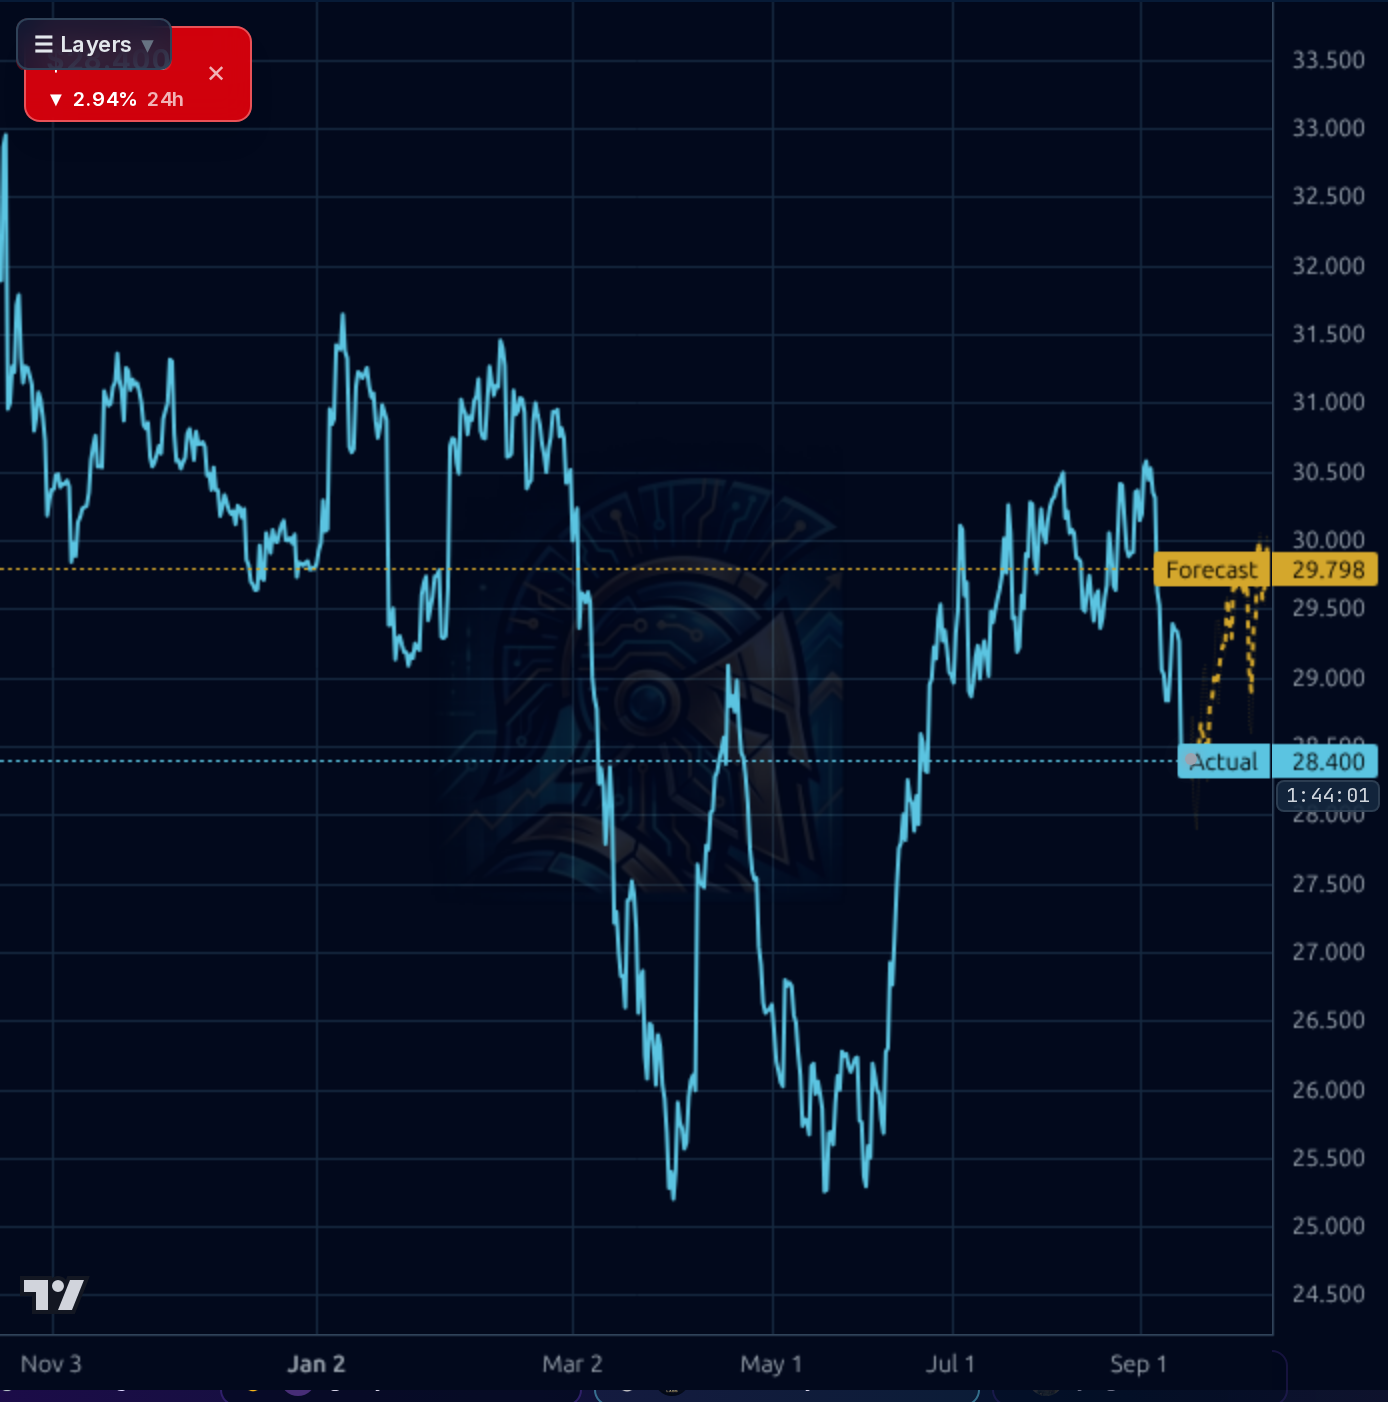
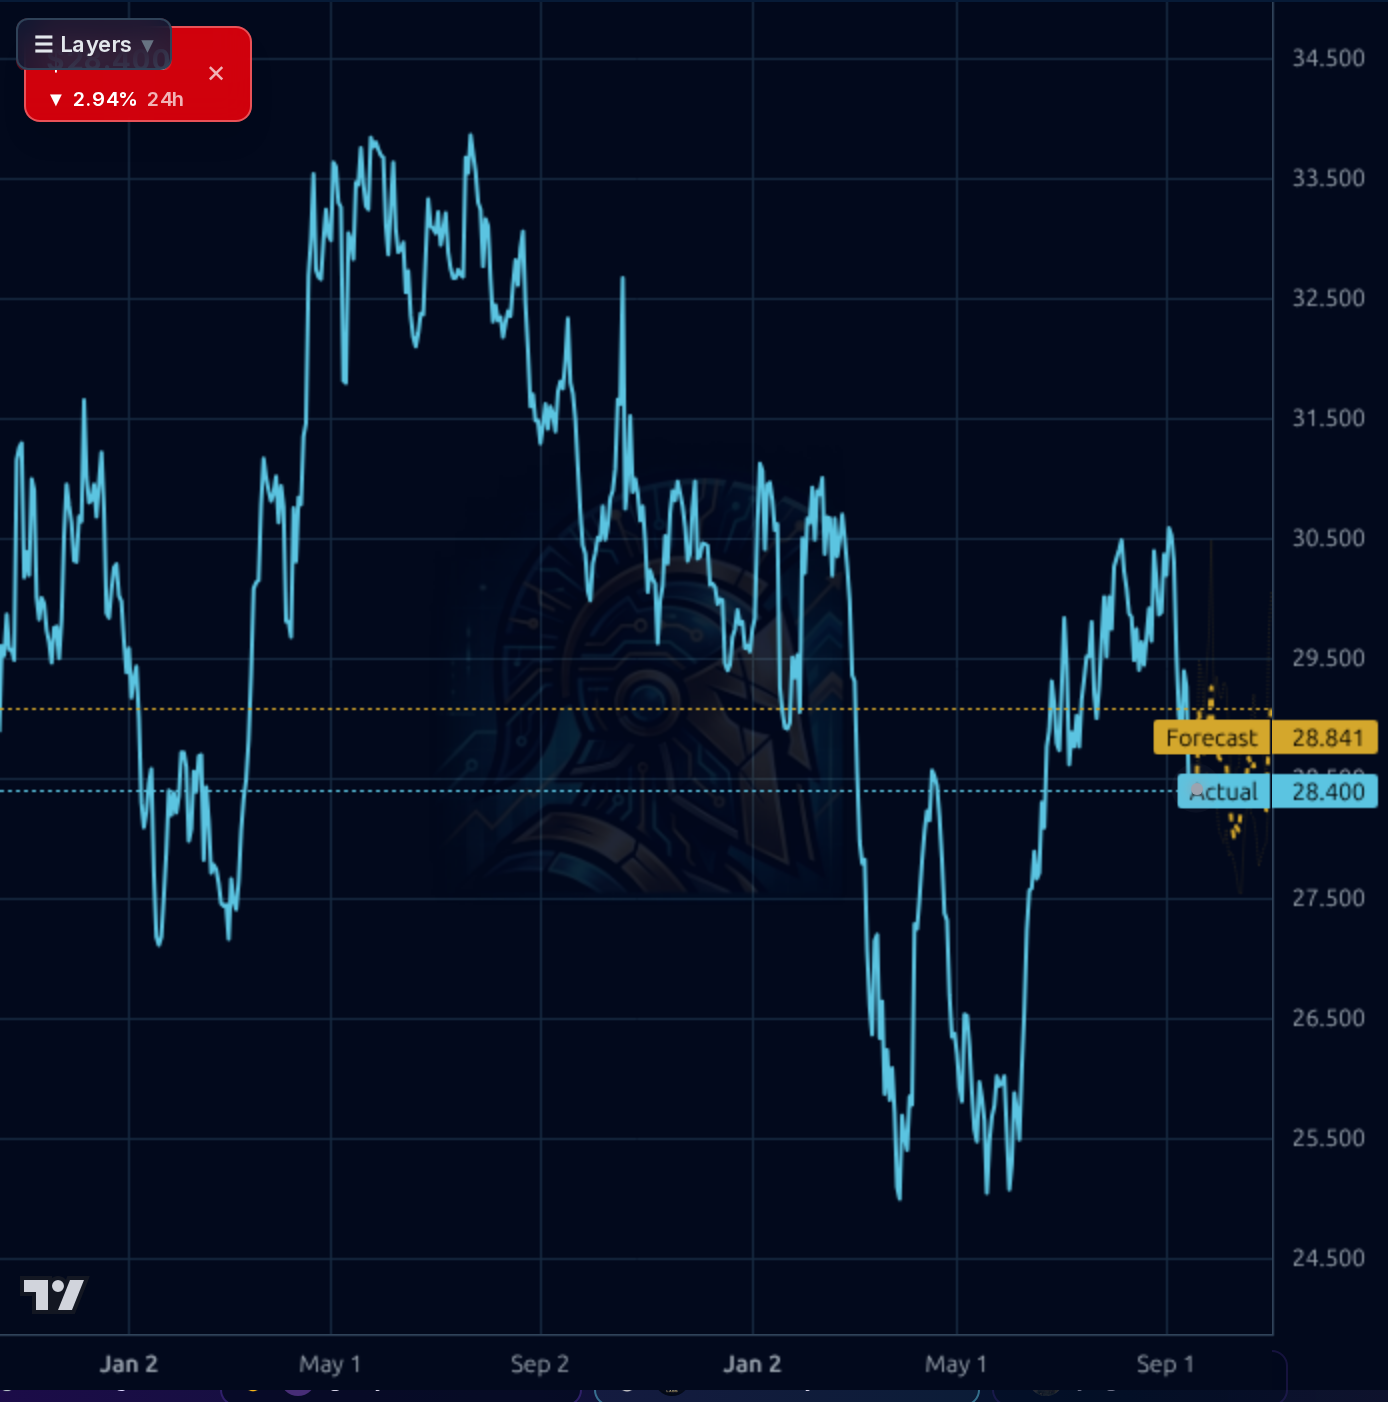
Across the four timeframes the trend has clearly rolled over near-term. The 1h chart shows a decisive break from the $29.00-$30.60 range down to $28.40 in the last two sessions — a ~7% drawdown in roughly a week. The 4h chart puts price back at the dashed support that also held in mid-2025, and the 1D shows we are now testing the lower boundary of the year-long consolidation between roughly $28 and $34. The 1W chart confirms we are well off the $34 high but still in a multi-year uptrend structure originating in 2023. Momentum is weak but not capitulated: RSI 36.4, price -4.5% below SMA20 and SMA50 and -1.5% below SMA200, sitting -14% from the 52w high of $33.03 and only +13% above the 52w low of $25.08. Kronos forecasts across the 1h/4h/1D timeframes cluster in the $28.8-$29.8 range — a mean-reversion bounce of 1-5% — while the 1W forecast at $27.64 hints that any bounce could fail into a retest of the mid-$27s. Model reliability is mixed: 1d directional accuracy 61% vs 59% baseline (marginal edge), 1wk 83% matches baseline (no edge), and the model's bullish_prob is 0.0, so I treat its bounce forecast as a low-conviction technical rebound signal, not a trend call.
[Correction: 8 recent article(s) were provided — see the news.] Signal: (1) The Sep-11 note that Erste raised FY2027 EPS estimates is a small but genuine positive from a covering analyst — consistent with the strong June quarter. (2) SEBI/regulatory clearance for ICICI Prudential AMC (subsidiary) to buy up to 9.95% of four other lenders (CSB, DCB, AU SFB, Kotak) is a meaningful capital-allocation optionality for the group. (3) The launch of 'ICICI Life Partner Stack 2.0' with AI-enabled advisor tooling is incremental digital-distribution color for the insurance subsidiary. Noise: the India-Russia payments/BRICS de-dollarization piece is macro/geopolitical context with no direct P&L impact on IBN. The Sep-14 broad-market note about Asian ADRs falling sharply captures today's weakness — it is a beta/flow story, not a company-specific fundamental problem. Net: nothing in the news flow damages the thesis; the price move is technical/flow-driven.
- June-quarter operating leverage: revenue +7.3% Q/Q to ₹384B while net income +4.6% pushed net margin to 40.2%, a four-quarter high
- AMC subsidiary cleared to acquire up to 9.95% stakes in CSB, DCB, AU SFB and Kotak — an unusual capital-deployment optionality
- Erste's Sep-8 FY27 EPS estimate upgrade is early Street corroboration of accelerating profitability
- Life-insurance digital re-platforming ('Partner Stack 2.0') to lift advisor productivity in the insurance vertical
- Planned bond issuance to fund international expansion, referenced in prior period
- Technical break of prior $28.50 support opens a path to $27.00-$27.60 per Kronos 1W forecast and 1W chart structure
- Oct 17 earnings is a binary event ~32 days away; IV crush and gap risk cap the case for large pre-print size
- ADR carries INR/USD translation risk on top of underlying equity risk — dollar strength can mute rupee-denominated gains
- Rising operating expenses flagged in prior work not yet visible but remains a watch-item into the print
- Broader Asian ADR flow weakness (Sep 4 and Sep 14 notes) shows the name is being sold as part of a regional risk-off trade, unrelated to fundamentals
- Consensus is already very bullish (Recom 1.11, target $36.61 = +29% upside) — leaves little room for positive-surprise re-rating and creates downgrade risk if the print disappoints
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord