KRMN — AI Stock Forecast & Price Targets
Published 9/11/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live KRMN price forecast →
KRMN has cratered ~30% in days on a CFO transition, a fresh $100M debt raise for the Walker acquisition, and a bearish short-seller report, taking shares to $35.28 near 52-week lows with RSI 23.5. Fundamentals remain a paradox — 58% Q/Q sales growth and expanding gross margins vs. 32x EV/EBITDA, $875M debt, and negative FCF — but the valuation reset (fwd P/E now ~37x vs. 61x prior) plus deeply oversold technicals create an asymmetric setup for patient buyers, tempered by a J Capital short thesis that has yet to be rebutted.
Do not chase. Price is oversold (RSI 23.5) and could bounce toward $40–45 on any short-cover or J Capital rebuttal, but the gap from $50 needs to be respected as heavy overhead supply. Starter position (25% of intended size) $34–36 with a hard stop below $32 (loss of 52-week low and prior weekly support invalidates the bounce thesis). Take partial profits into $42–45. Position small — realized volatility is 6.7% daily.
Over 1–6 months the fight is between a $3B pipeline / 50%+ revenue growth story and a leveraged, cash-burning balance sheet under short attack. If management issues a substantive rebuttal to J Capital and Q3 (Nov 5 earnings) confirms revenue run-rate + shows FCF inflection, the stock can retrace to the $55–65 zone (still below the $61 sponsor secondary ceiling). If Q3 disappoints or debt covenants become a topic, $28–30 is the next major support. Base case return: +40–70% from $35 to $50–60 over six months. Change my mind: another debt raise, guidance cut, or covenant issue.
The secular thesis — hypersonics, missile defense, and space launch propulsion are non-discretionary US defense spend categories — remains intact and is now reinforced by European defense exposure via Walker. If Karman converts even half of its $3B pipeline into revenue over 3 years and de-levers via FCF, the stock is materially undervalued at current levels. Terminal risk is that the J Capital thesis proves partially correct (aggressive accounting, pipeline optics, or channel-stuffing) and the company requires equity dilution to service debt. This is a binary-ish name over multi-year horizons: either it grows into the multiple or the leverage catches up with it.
Operating fundamentals continue to accelerate: Q2'26 revenue of $182M is up 58% Y/Y, gross margin expanded to 43.0% (from 39.9% in Q4'25), and operating margin hit 19.1%. TTM EPS growth of 366% and next-year EPS growth estimated at 61% support the growth narrative, and analyst recom of 1.17 with a $92.67 PT signals sell-side is still constructive despite the recent PT trim from $102. However, the balance sheet is deteriorating meaningfully — total debt jumped to $875M (D/E 2.08), cash is only $52M, and the fresh $100M term loan for the Walker acquisition (8-K, Aug 28) piles on more leverage. FCF was -$17.7M in Q2 and -$57M TTM, so growth is being funded by debt, not internally generated cash. EV/EBITDA of 32x and P/S of 7.9 remain rich for a levered, cash-burning industrial, even after the drawdown. Capital allocation is aggressive (M&A + debt), and the CFO transition mid-integration is not the timing you want.
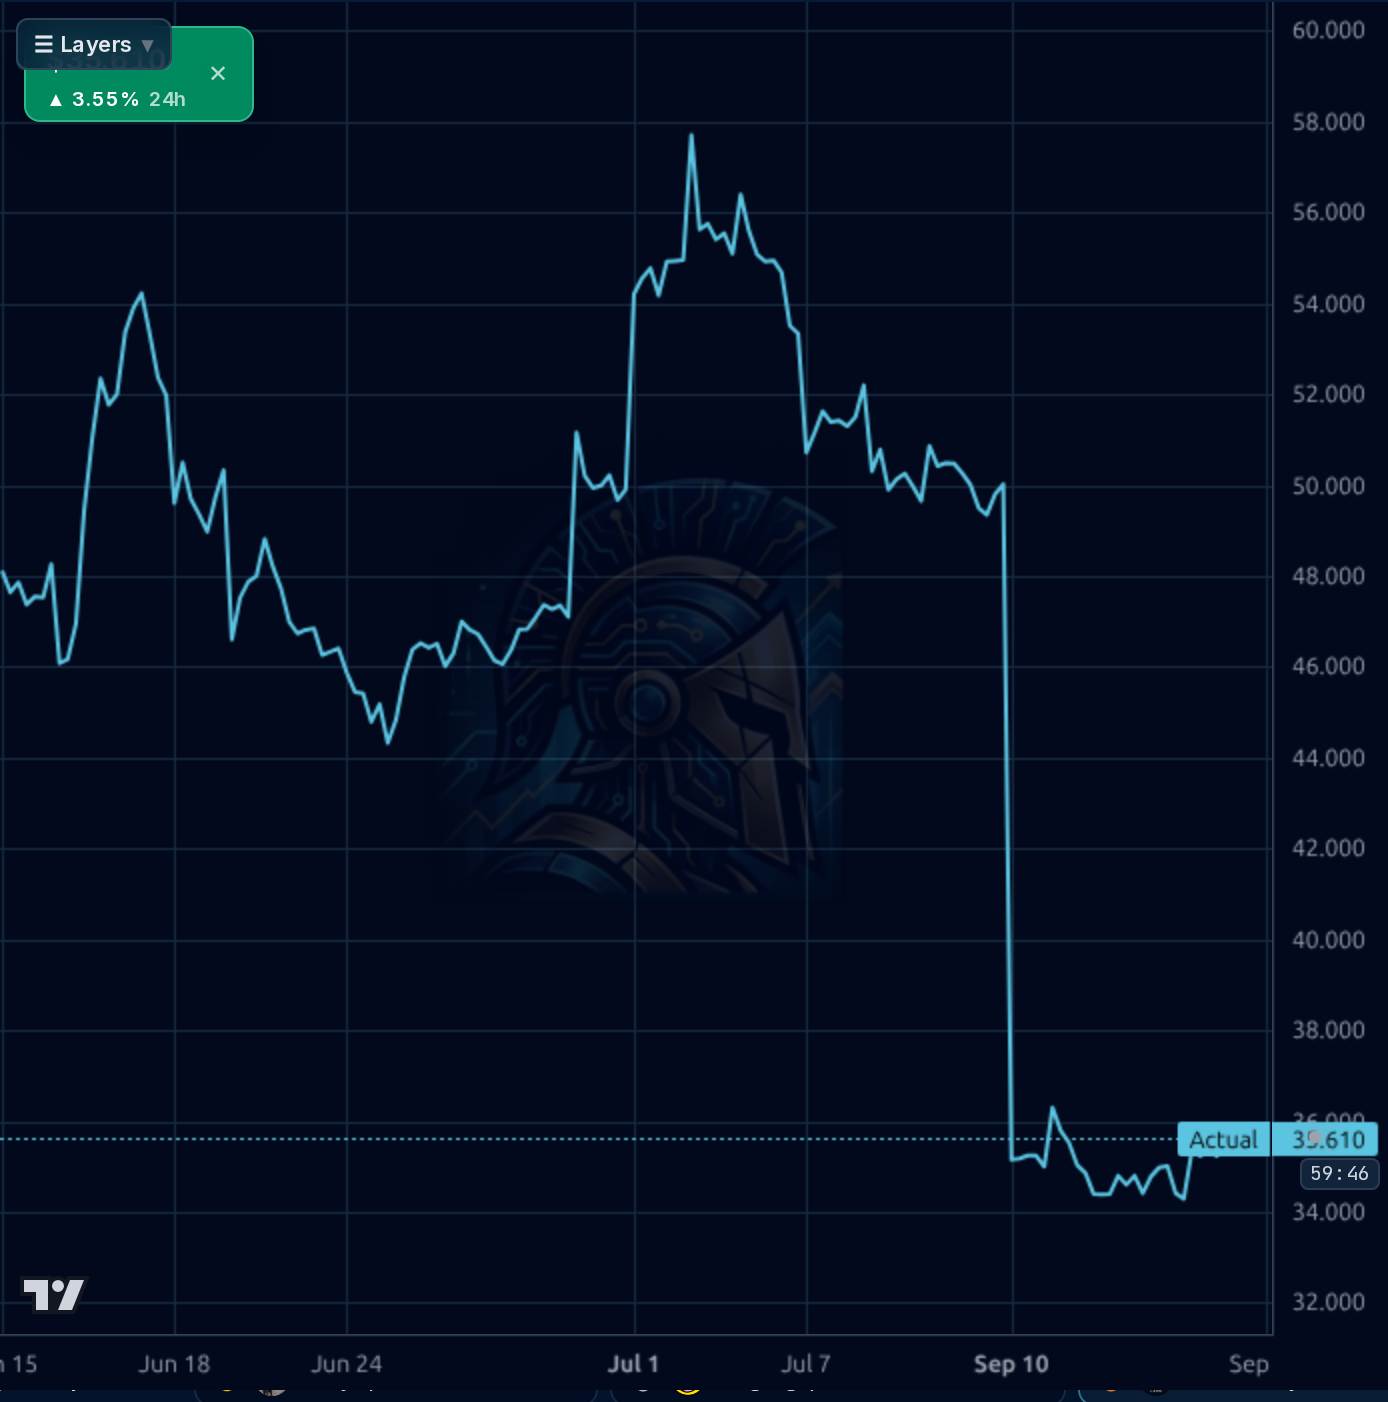
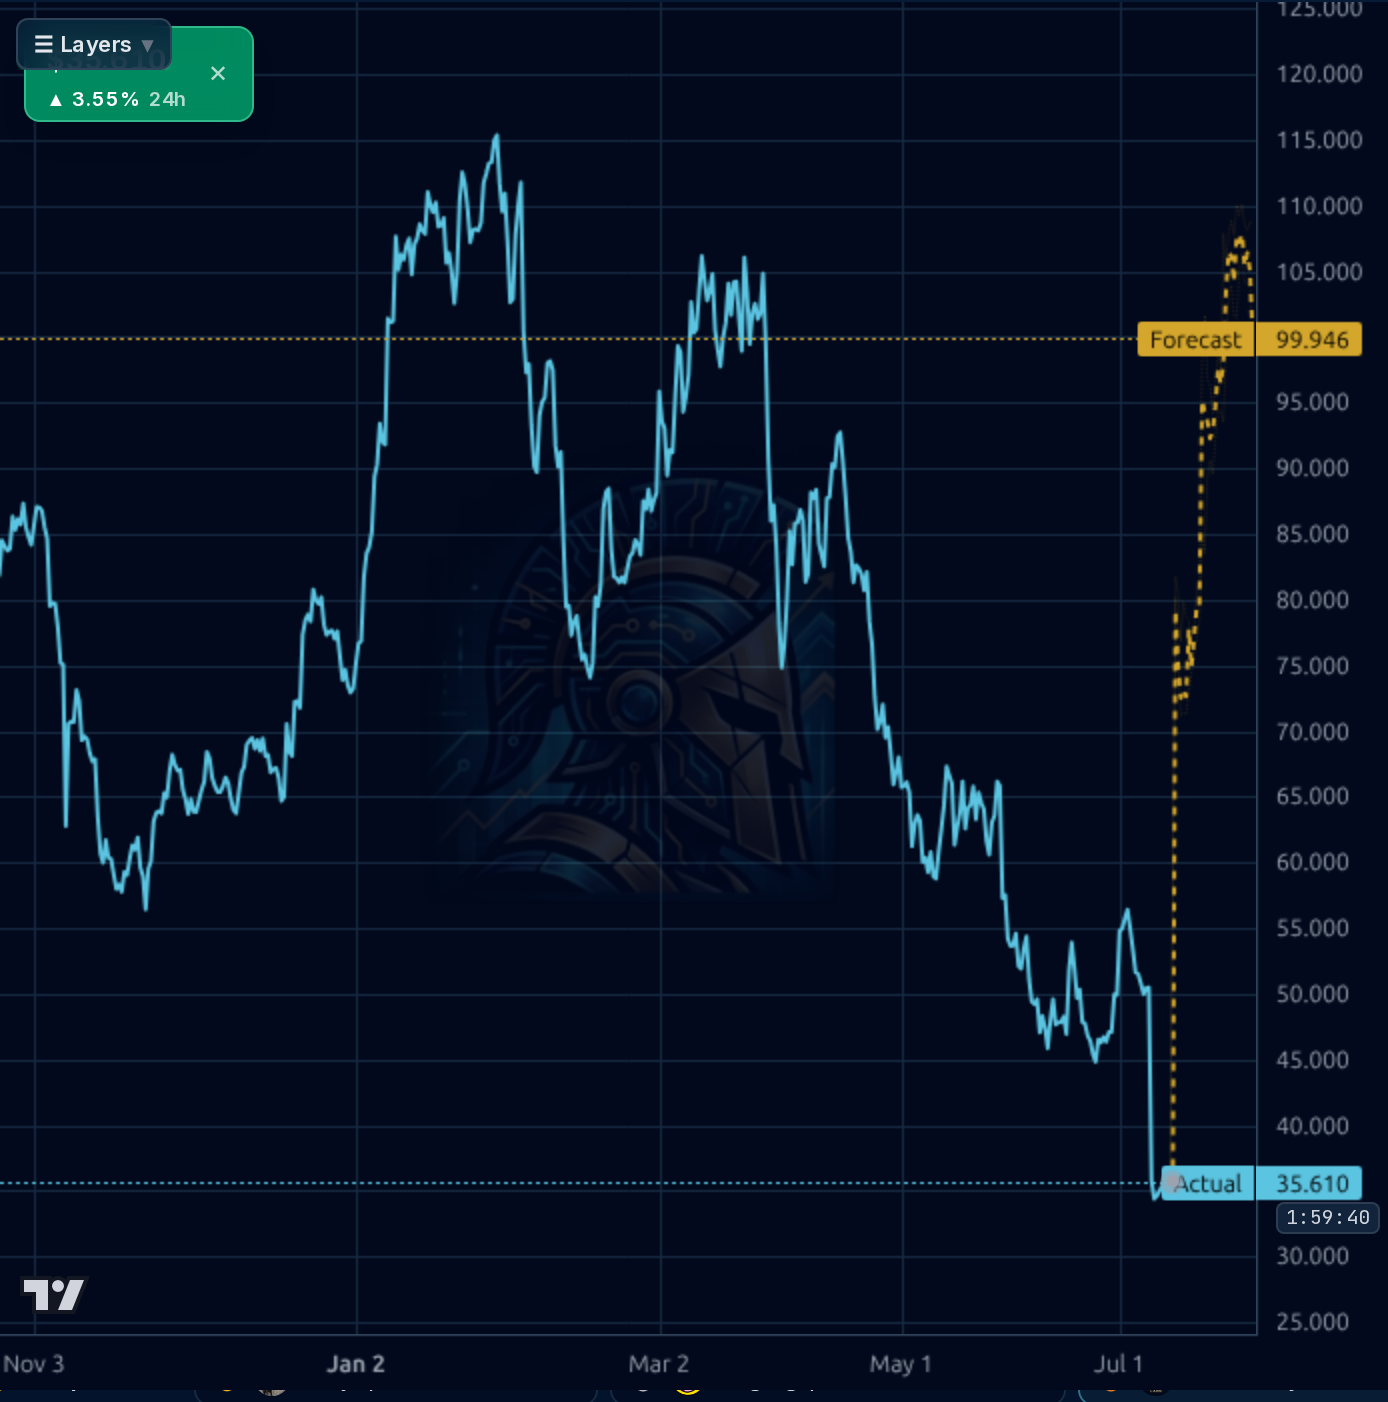
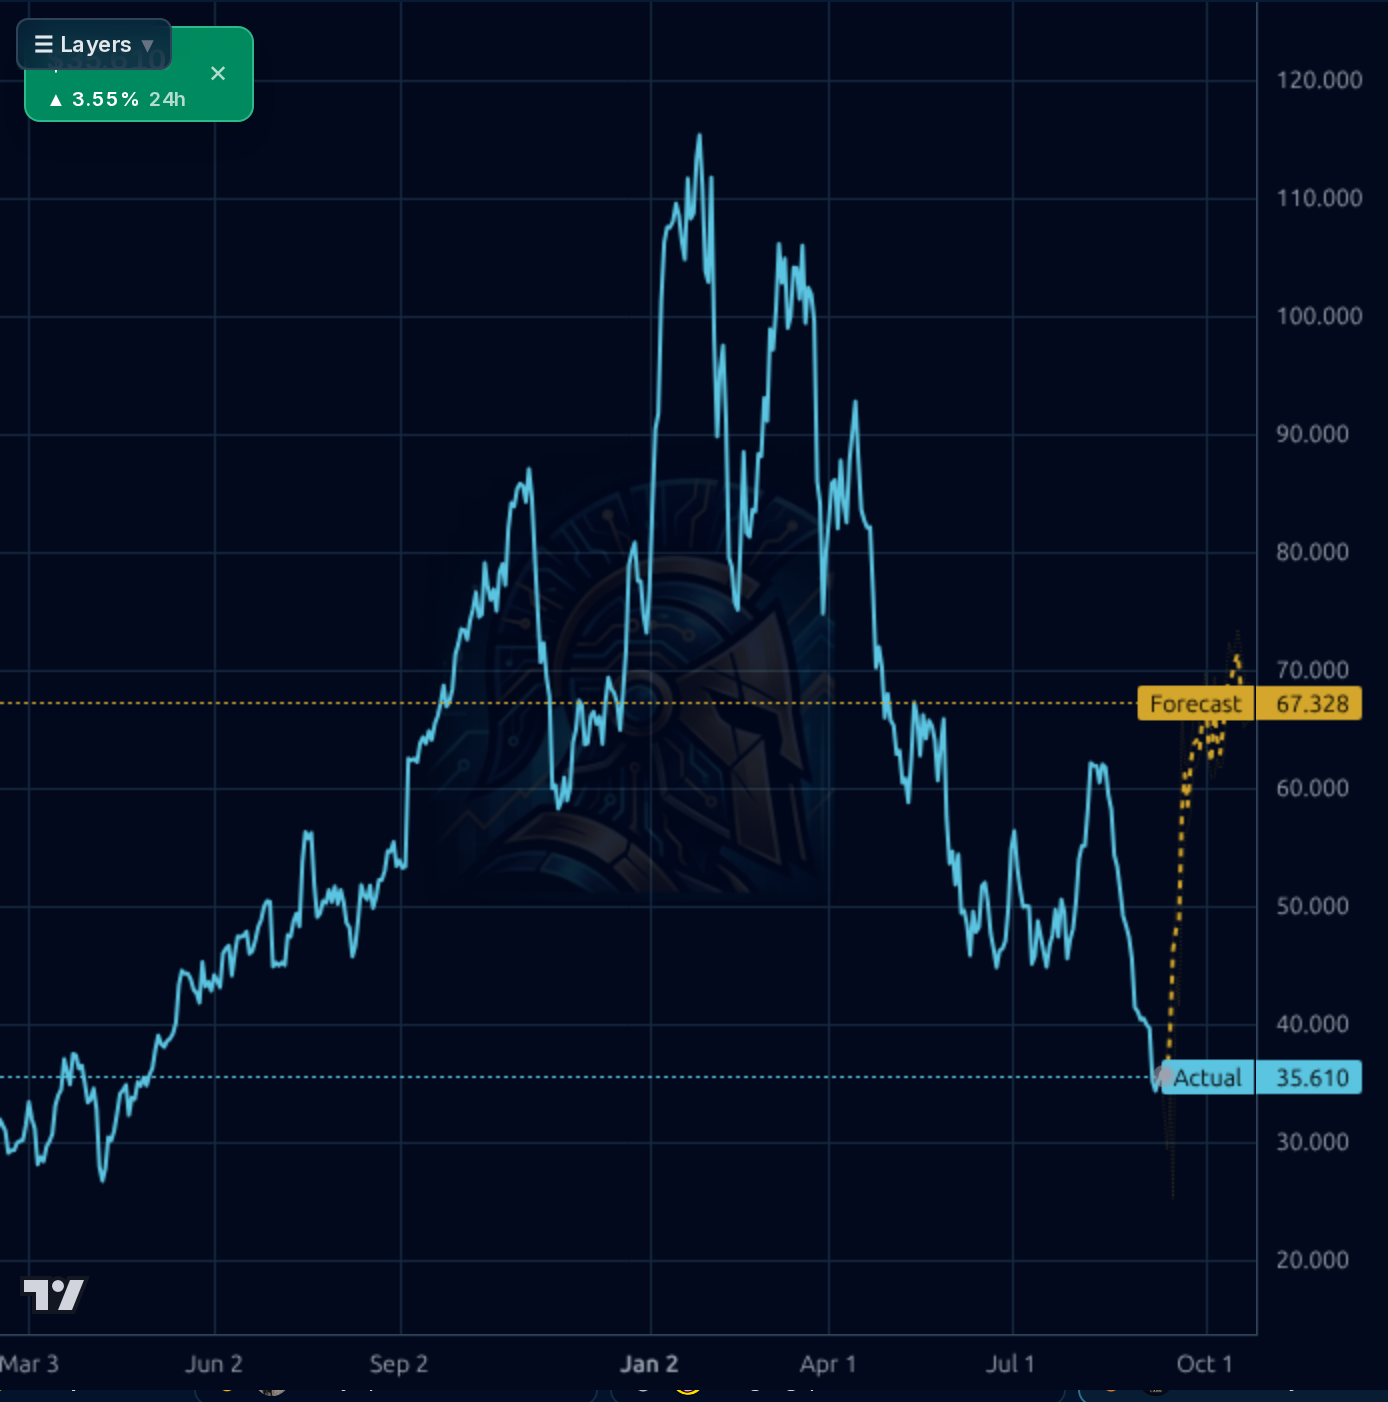
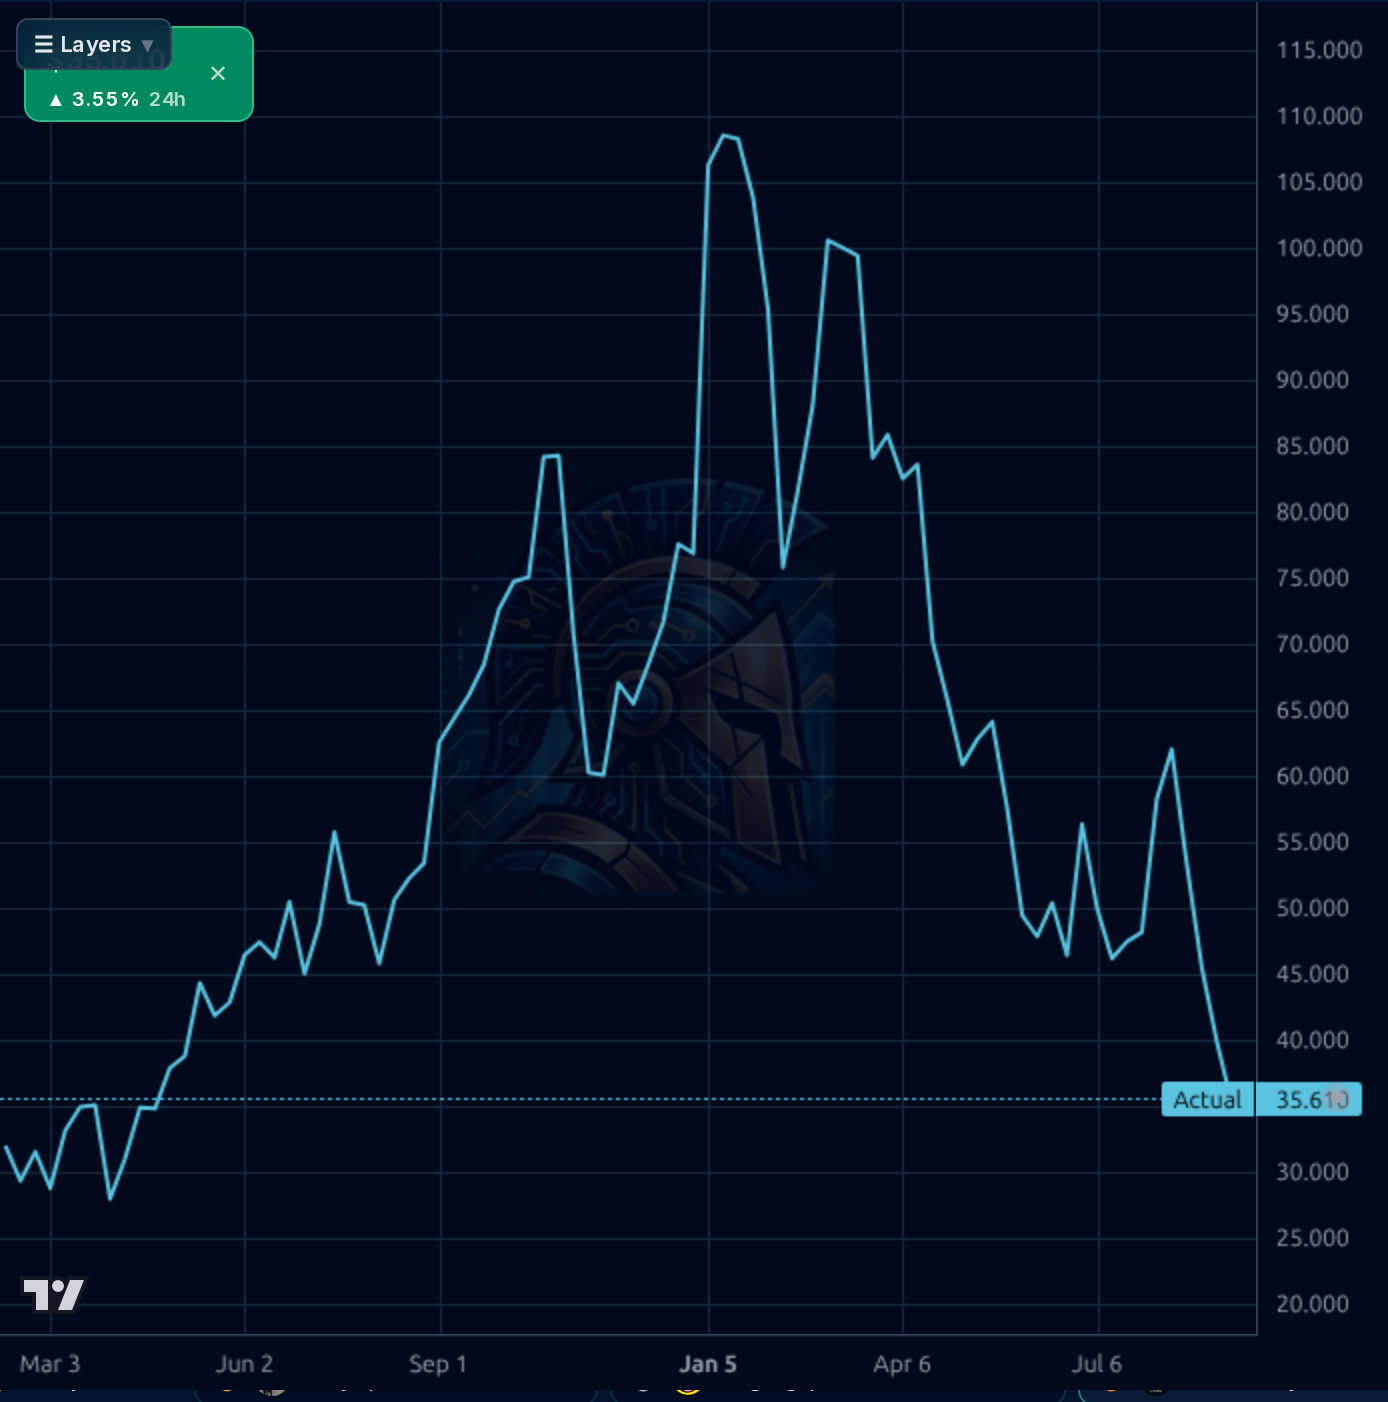
The tape is broken across all timeframes. The 1h chart shows a violent gap-down from ~$50 to ~$35 on the Sep 10 news, with price consolidating $34–36 since — a classic capitulation candle but with no reclaim yet. The 4h and 1d charts confirm a completed distribution top from the $115 January high, with price now -70% from the 52-week high, -50% below the 200-day SMA, -29% below the 50-day, and RSI 23.5 (deeply oversold). The weekly is an unambiguous downtrend with prior structural support at $30 as the next real floor. The Kronos forecast bands project a sharp mean-reversion to $67 (1d) and $100 (4h) — but the model's own realized 1d directional accuracy is 13% vs. a 98% naive baseline, so those upside targets should be heavily discounted. Immediate support: $34 (52-week low, tested); next: $30 psychological. Resistance: $40 (gap fill start), $45 (pre-gap consolidation), then $50 (gap origin).
Two catalysts drove the collapse: (1) an Aug 26 CFO transition announcement, and (2) a Sep 2 J Capital short report titled 'Anyone can pay $10 for a $5 bill,' explicitly attacking valuation. Layered on top is the Sep 1 close of the Walker Precision Engineering (UK/European defense) acquisition, funded by a $100M add-on term loan disclosed in the Aug 28 8-K — a strategic positive (European defense exposure) but a balance-sheet negative in the current tape. Short float rose to 15.1% (from 12.7%) as bears pressed the thesis. The broader market backdrop (SPY late-cycle, breadth deteriorating) is unhelpful for high-beta, high-multiple names. Signal: real deleveraging pressure and an activist short with a documented thesis. Noise: crowd sentiment on Stocktwits is 100% bullish (contrarian caution) and social chatter is thin.
- Walker Precision Engineering acquisition (closed Sep 1) establishes a European defense platform, expanding TAM beyond US-only exposure
- Q2'26 revenue of $182M (+58% Y/Y) with gross margin expansion to 43% suggests operational leverage is real as backlog converts
- $3B pipeline in hypersonics, missile defense, and space launch — non-discretionary US government spending categories
- Analyst consensus PT of $92.67 (recom 1.17) implies 163% upside if the multiple holds through backlog conversion
- Next-year EPS growth estimated at 61%, with 5Y EPS CAGR of 52% supporting a PEG of 0.71 (cheap on growth-adjusted basis)
- J Capital short report (Sep 2) explicitly targets valuation and remains unrebutted — additional installments could pressure further
- $875M total debt vs. $52M cash; D/E of 2.08 with -$57M TTM FCF means growth is debt-funded, not self-funded
- CFO transition announced Aug 26 in the middle of Walker acquisition integration — worst possible timing
- Short float rose to 15.1% (from 12.7%) and short ratio 5.72 — crowded short but also validates bearish thesis
- Sponsor overhang from TCFIII (parent) — prior secondary at $61 established a structural ceiling; further offerings possible if debt pressure builds
- Forecast model directional accuracy 13% (vs. 98% naive baseline) — bullish AI targets should be heavily discounted
- Broader market breadth deteriorating (46% >200dMA) — high-multiple, high-beta names historically underperform in this regime
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord