KVYO — AI Stock Forecast & Price Targets
Published 9/13/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live KVYO price forecast →
Klaviyo pairs a real operational inflection (+26% YoY revenue, $285M TTM FCF, $833M cash) with a broken technical tape that has now flushed to $16.22, breaking the $17 shelf and confirming prior calls' bullish targets were systematically optimistic. With 26% short float, clustered insider selling (>$3.5M in August), and the $19.60 200-day SMA acting as a hard cap, this is an accumulate-on-weakness setup in the $15-16 zone into the Nov 4 print — not a chase, and defensively sized given the tape.
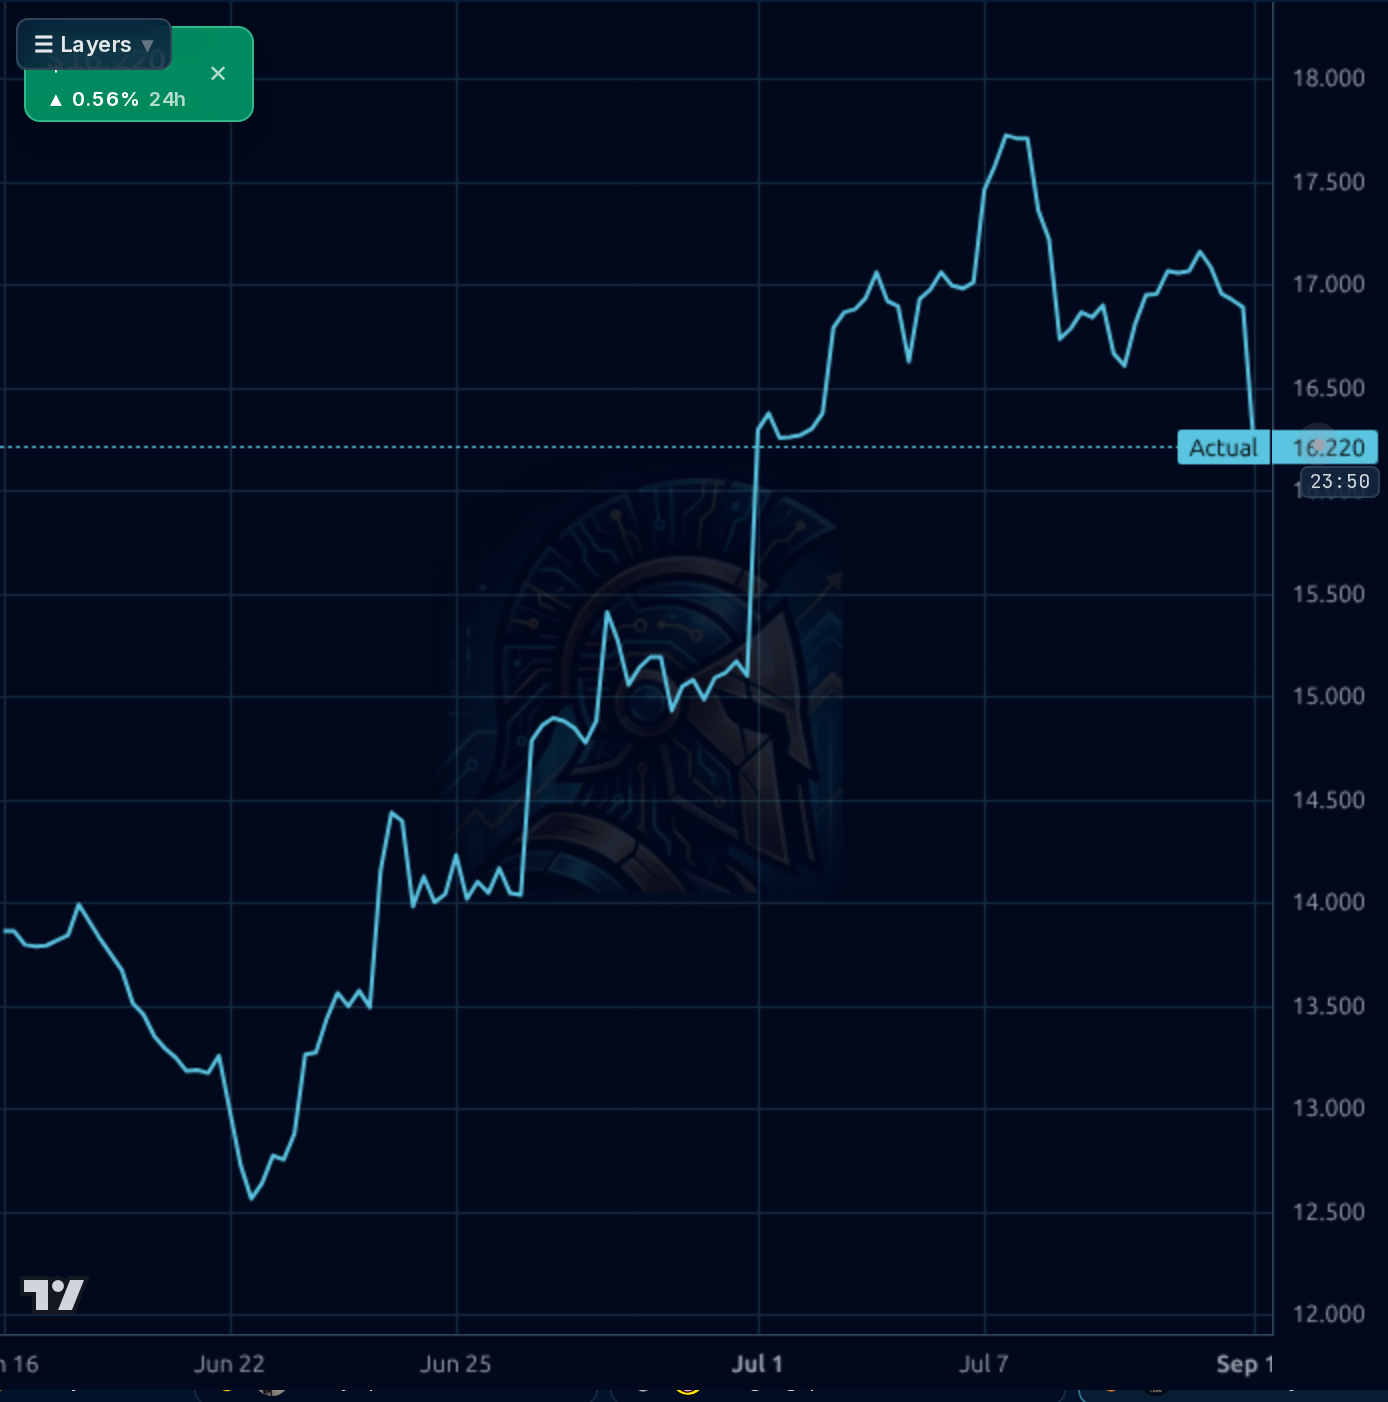
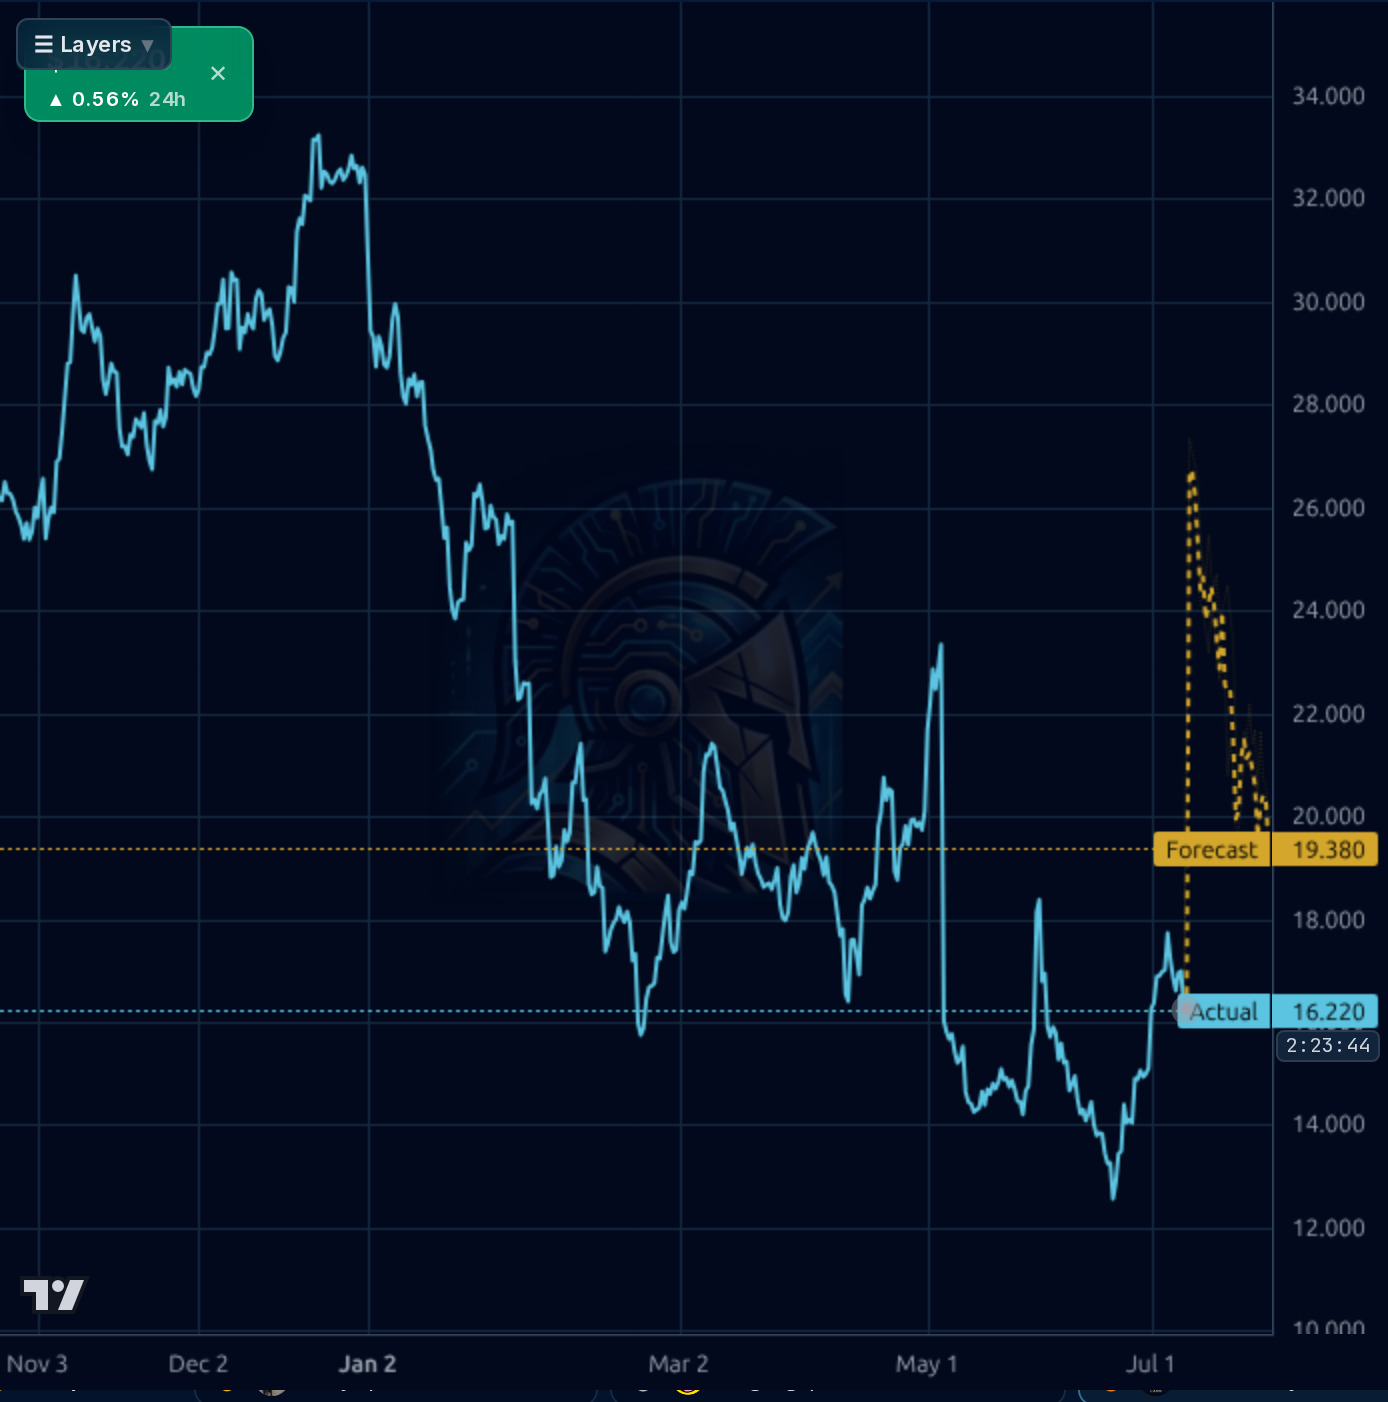
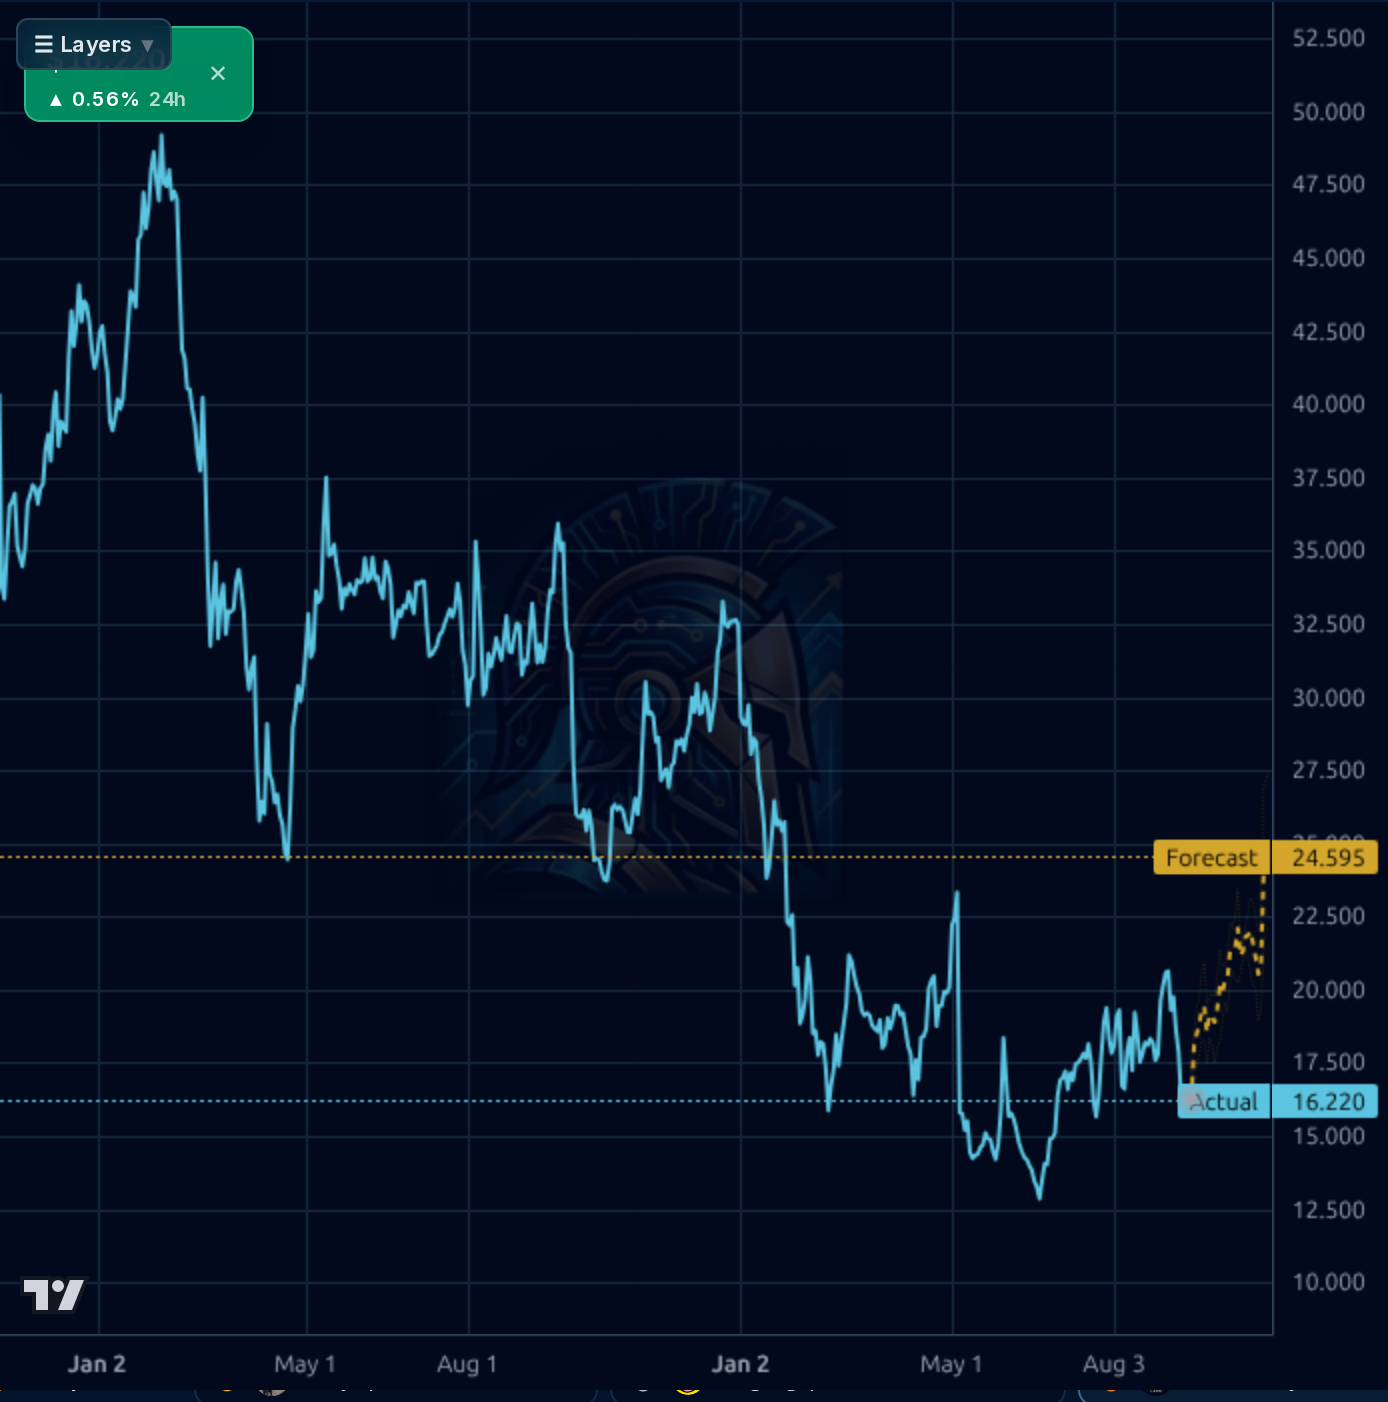
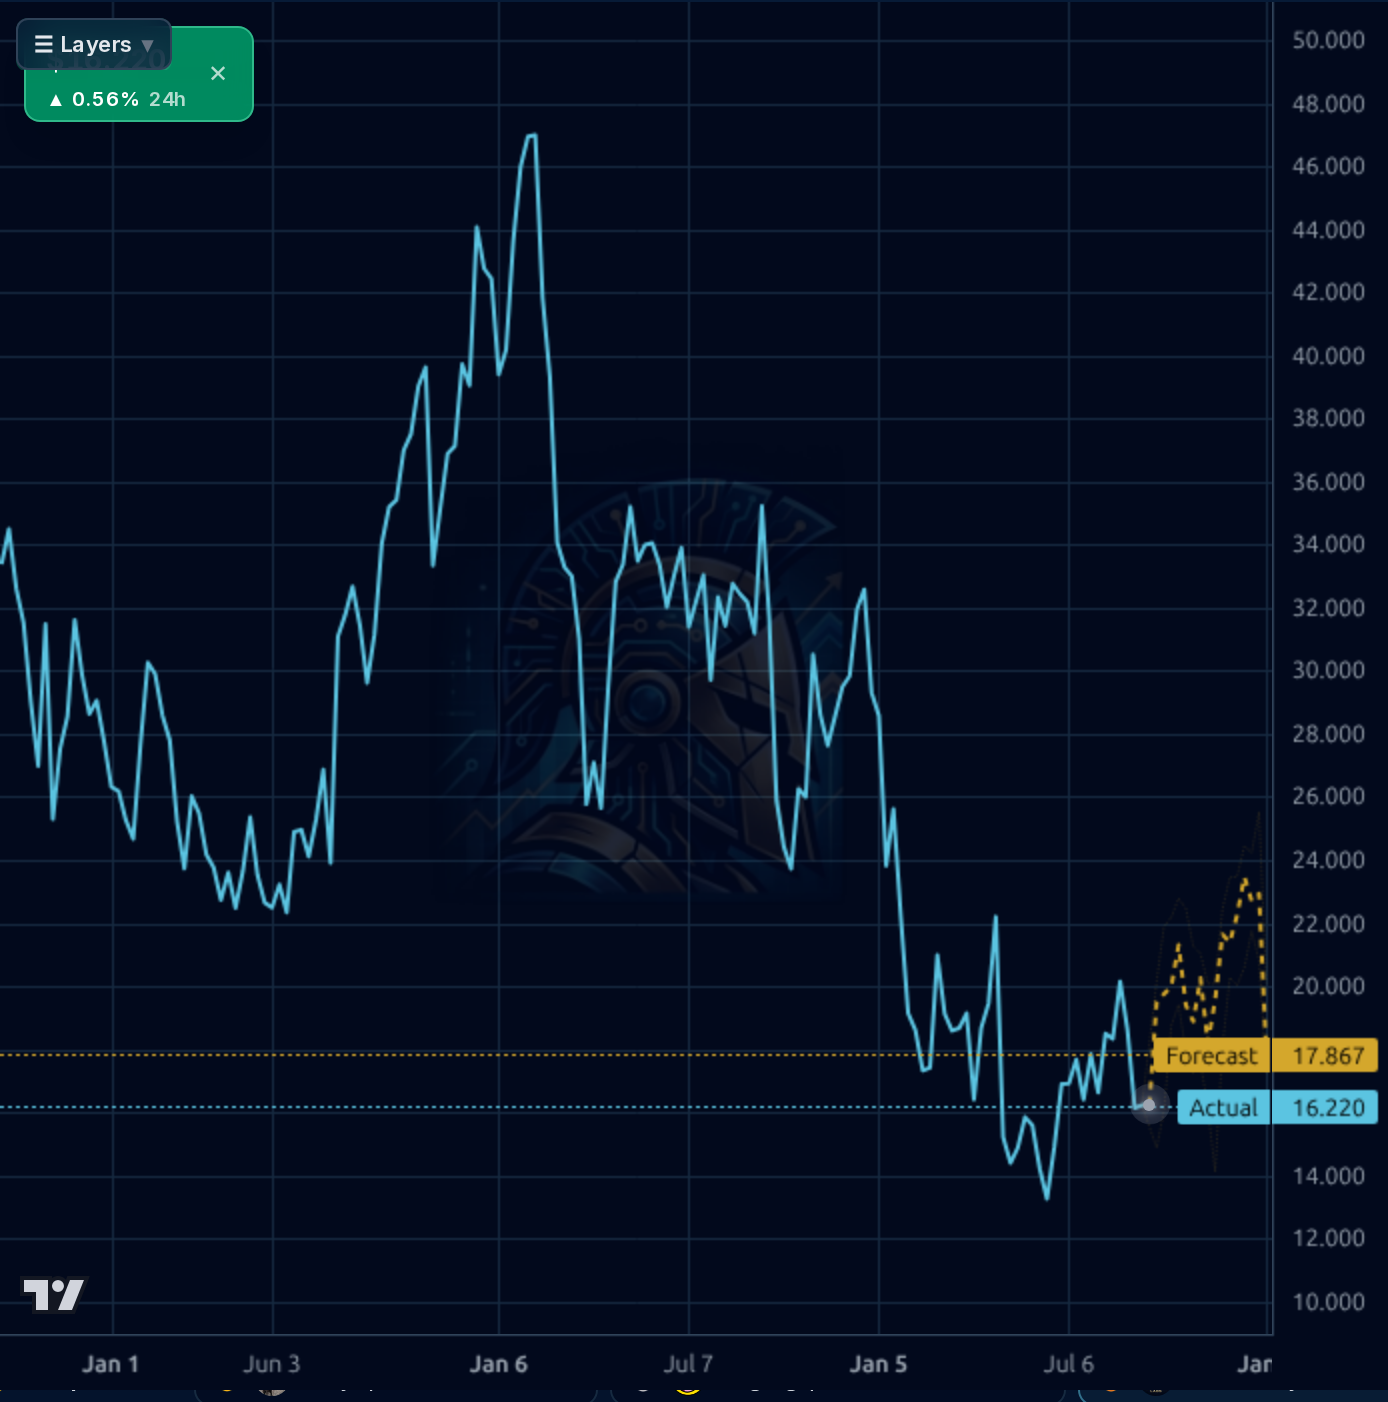
1-4 week view: Accumulate scaled in the $15.50-16.25 zone with 1/3 starter size at $16.22, add 1/3 at $15.50, hold 1/3 dry powder for a $14.00 flush or a confirmed reclaim of $17.50 on volume. Hard invalidation: weekly close below $14.00 (opens $12.53 52-week low retest). Do not chase strength into $18-19.60 — that zone has been a reliable fade. Recognize the model's 1wk forecast is beaten by naive baseline; treat the yellow forecast band as noise. Position size at 1/2 normal given the broken tape and 26% short float.
1-6 month view: The Nov 4 Q3 print is the entire thesis — first paid ARPU data from Composer/Customer Agent is the critical proof point. A beat on revenue + evidence GAAP operating margin has stabilized above breakeven would allow a durable reclaim of $19.60 and open $22-23. A miss on either axis, or continued SMS gross-margin drag toward 72%, likely retests $14. Base case: chop between $15-19 into the print, then binary outcome. Expected return range: -15% to +30% from $16.22 depending on Nov 4 execution. What changes my mind bearish: gross margin drops below 72%, GAAP operating loss widens beyond -$20M, cash breaches $780M. What changes my mind bullish: gross margin stabilizes ≥73%, GAAP operating income positive, Composer ARPU disclosed with real numbers.
1-3 year view: Klaviyo has a credible path to becoming the B2C CRM data layer if the headless/agentic platform pivot lands — the K:BOS announcements suggest management understands the existential threat and is architecting for it. Terminal thesis requires: (a) SMS gross-margin compression bottoms in the low-70s and stops, (b) AI monetization (Composer, Customer Agent, Marketing Agent) adds 300-500bps to organic revenue growth by FY27, (c) GAAP operating margin scales toward 10-15% on Rule-of-40 discipline. At 3.35x P/S and ~15.5x fwd P/E, the equity is priced for that to fail. Biggest structural risk: agentic AI dis-intermediates the marketing automation layer entirely, making Klaviyo a commoditized data pipe rather than the workflow owner — Shopify, HubSpot, or an OpenAI/Anthropic-native competitor could compress the TAM before the pivot compounds.
The fundamental picture is genuinely improving but not clean. Q2'26 revenue of $370.6M (+26% YoY) marks sequential acceleration from Q3'25's +21%, with sales Y/Y TTM at +28.9% and enterprise/international mix driving the mix shift. Cash generation is the anchor: Q2 OCF $93.9M, TTM FCF ~$285M, P/FCF ~19.7x — a reasonable multiple for a scaled SaaS. Balance sheet is fortress-grade: $833M cash vs $114M debt, current ratio 3.13, insider ownership 71.4%, funding a $500M buyback. The cracks: gross margin compressed 75.1% → 72.6% QoQ on structural SMS carrier fees (durable, not cyclical); GAAP operating income re-turned negative in Q2 at -$15.0M after Q1's brief +$1.7M positive, so the operating inflection is unproven; and cash is bleeding at the margin ($1.06B Q4'25 → $833M Q2'26) as buybacks and SBC consume the fortress. Trailing P/E is meaningless at 545x on $0.03 EPS, but forward P/E of 15.5x and PEG 0.61 are attractive IF GAAP margins actually inflect. Bottom line: quality is real, monetization inflection is TBD at Nov 4.
Multi-timeframe tape is unambiguously broken. Weekly chart shows a two-year downtrend from ~$48 (Jan '24) to a $12.53 52-week low, with price now at $16.22, -49.6% YTD, -48.6% YoY, -18.9% below 200-day SMA and -8.7% below 50-day. The 1h chart shows the Jul 1 spike from $15 to ~$18 fully round-tripping — every rally has failed, and the $17 shelf has now decisively broken. Daily forecast band projects $19-24 (target $24.60), but the weekly forecast overlay (17.87) is more realistic given the model's documented 33% weekly directional accuracy (beaten by naive baseline — heavily discount upside overlays). RSI 40.3 is oversold-adjacent but not extreme. The critical structure: $19.60 200-day SMA has rejected every rally in 2026 and remains the hard cap; next support is the $15.00-15.50 zone, then the $12.53 52-week low. Perf Week -17.2% signals capitulation-like flush, which historically on this name has NOT been a bounce trigger without a fundamental catalyst. Short float at 26.2% (down from 30.4% peak, per the L2 bullish signal) is beginning to ease — first faint positive tell.
The signal-to-noise ratio in the news is mixed but net constructive. The most material items: (1) Sept 9 K:BOS conference announced Klaviyo going 'headless' — opening the platform to external AI agents and adding Composer/Customer Agent enhancements, which is a defensive but strategically sensible pivot to remain the data layer as agentic AI reshapes marketing SaaS; (2) options-market activity flagged twice suggesting a spike is being priced in, though direction unspecified; (3) Sept 3 stock trading up 6.8% intraday, quickly given back — consistent with the 'every rally fails' pattern. The overhang: clustered insider selling — Director Hallen dumped $2M (51% of position) Aug 31, CLO Edmond sold $1.3M across late Aug, CFO Whalen $0.5M — all 10b5-1 plans but the size and clustering matter. Broader market backdrop (SPY late markup, breadth deteriorating at 46% >200dMA) argues against paying up for beaten-down high-multiple names. Retail sentiment is 100% bullish (11 tagged messages) — a modest contrarian caution, not a decisive tell.
- K:BOS 2026 headless platform launch (Sept 9) — opening Klaviyo to external AI agents, positioning as the B2C CRM data layer for agentic workflows
- Composer agent enhancements and Customer Service agent improvements announced at K:BOS — first paid ARPU disclosure expected Nov 4 Q3 print
- Deeper personalization workflows and Klaviyo Social bringing social interaction data into unified consumer profiles — TAM expansion beyond email/SMS
- $500M buyback authorization actively executing — 140.9M shares outstanding, meaningful float reduction potential at current $16 handle
- Klaviyo Data Platform (KDP) and Advanced KDP monetization — enterprise/international revenue mix already driving Q2 +26% YoY reacceleration
- Marketing Agent (AI-driven autonomous marketing assistant) and Customer Agent (AI support/selling) — pipeline monetization is the Nov 4 proof point
- Structural SMS carrier-fee gross-margin compression (75.1% → 72.6% QoQ) is durable, not cyclical — direct impact on unit economics
- GAAP operating income re-turned negative in Q2 (-$15.0M) after Q1's brief +$1.7M — the operating inflection is unproven and may reverse further
- Short float 26.2% (peaked 30.4%) has historically preceded downside on this name, not a squeeze setup — treat as leading bear signal
- Clustered insider selling: Director Hallen -$2M/51% of position, CLO Edmond -$1.3M, CFO Whalen -$0.5M all in late Aug — size and clustering matter beyond 10b5-1 optics
- $19.60 200-day SMA has rejected every rally in 2026 — technical damage requires multiple weekly closes above to repair, not a single spike
- Institutional ownership erosion 49.4% → 42.4% signals sponsorship loss ahead of the Nov 4 catalyst
- Agentic AI existential risk — if OpenAI/Anthropic-native or Shopify/HubSpot-integrated competitors own the workflow, Klaviyo becomes a commoditized data pipe
- Cash balance declining $1.06B → $833M in two quarters as buybacks + SBC consume the fortress — pace matters if operating margin does not inflect
- Broader market regime deteriorating (breadth 46% >200dMA) argues against paying up for beaten-down high-multiple SaaS names
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord