LYFT — AI Stock Forecast & Price Targets
Published 9/10/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live LYFT price forecast →
Lyft presents a compelling recovery narrative underpinned by operational inflection (16% Y/Y revenue growth) and strong Free Cash Flow generation ($1.15B TTM), but this potential is severely hampered by structural balance sheet weaknesses, particularly negative working capital and volatile operating margins. The stock's current price action suggests caution, requiring a clear technical breakout above $17-$17.50 to confirm any bullish thesis.
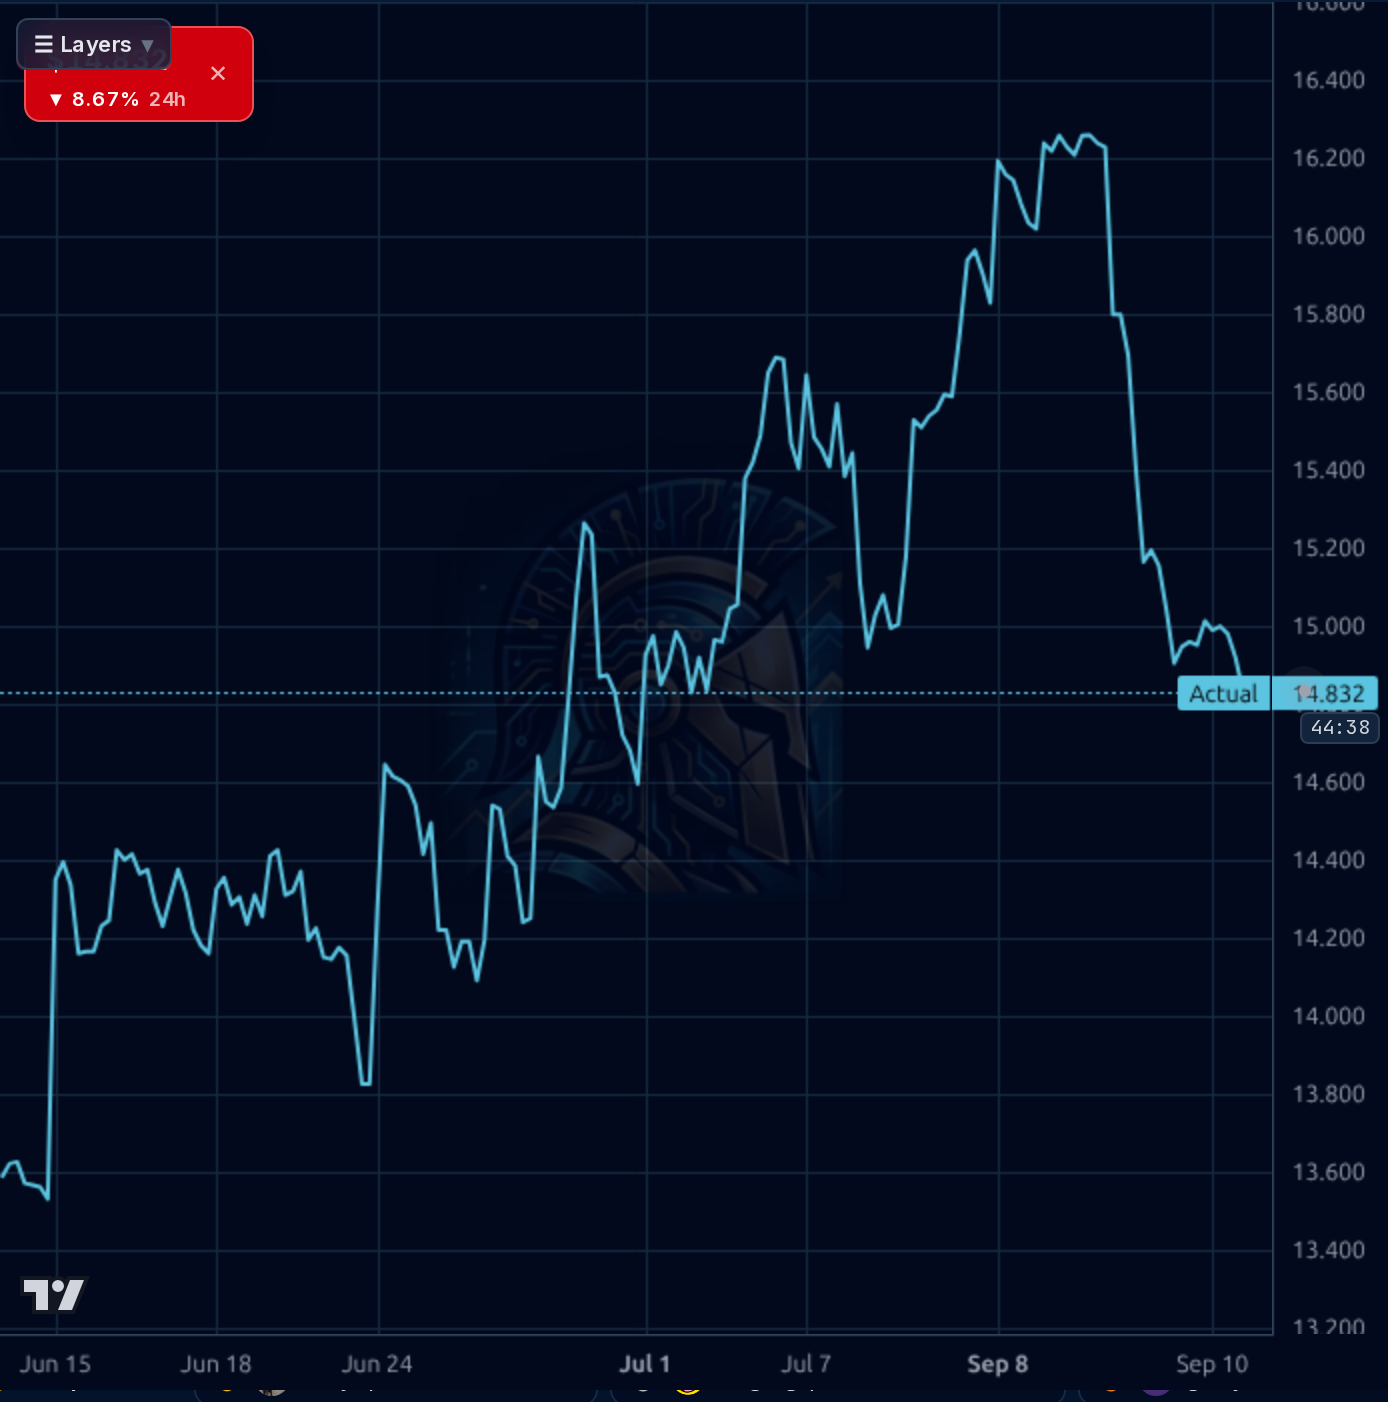
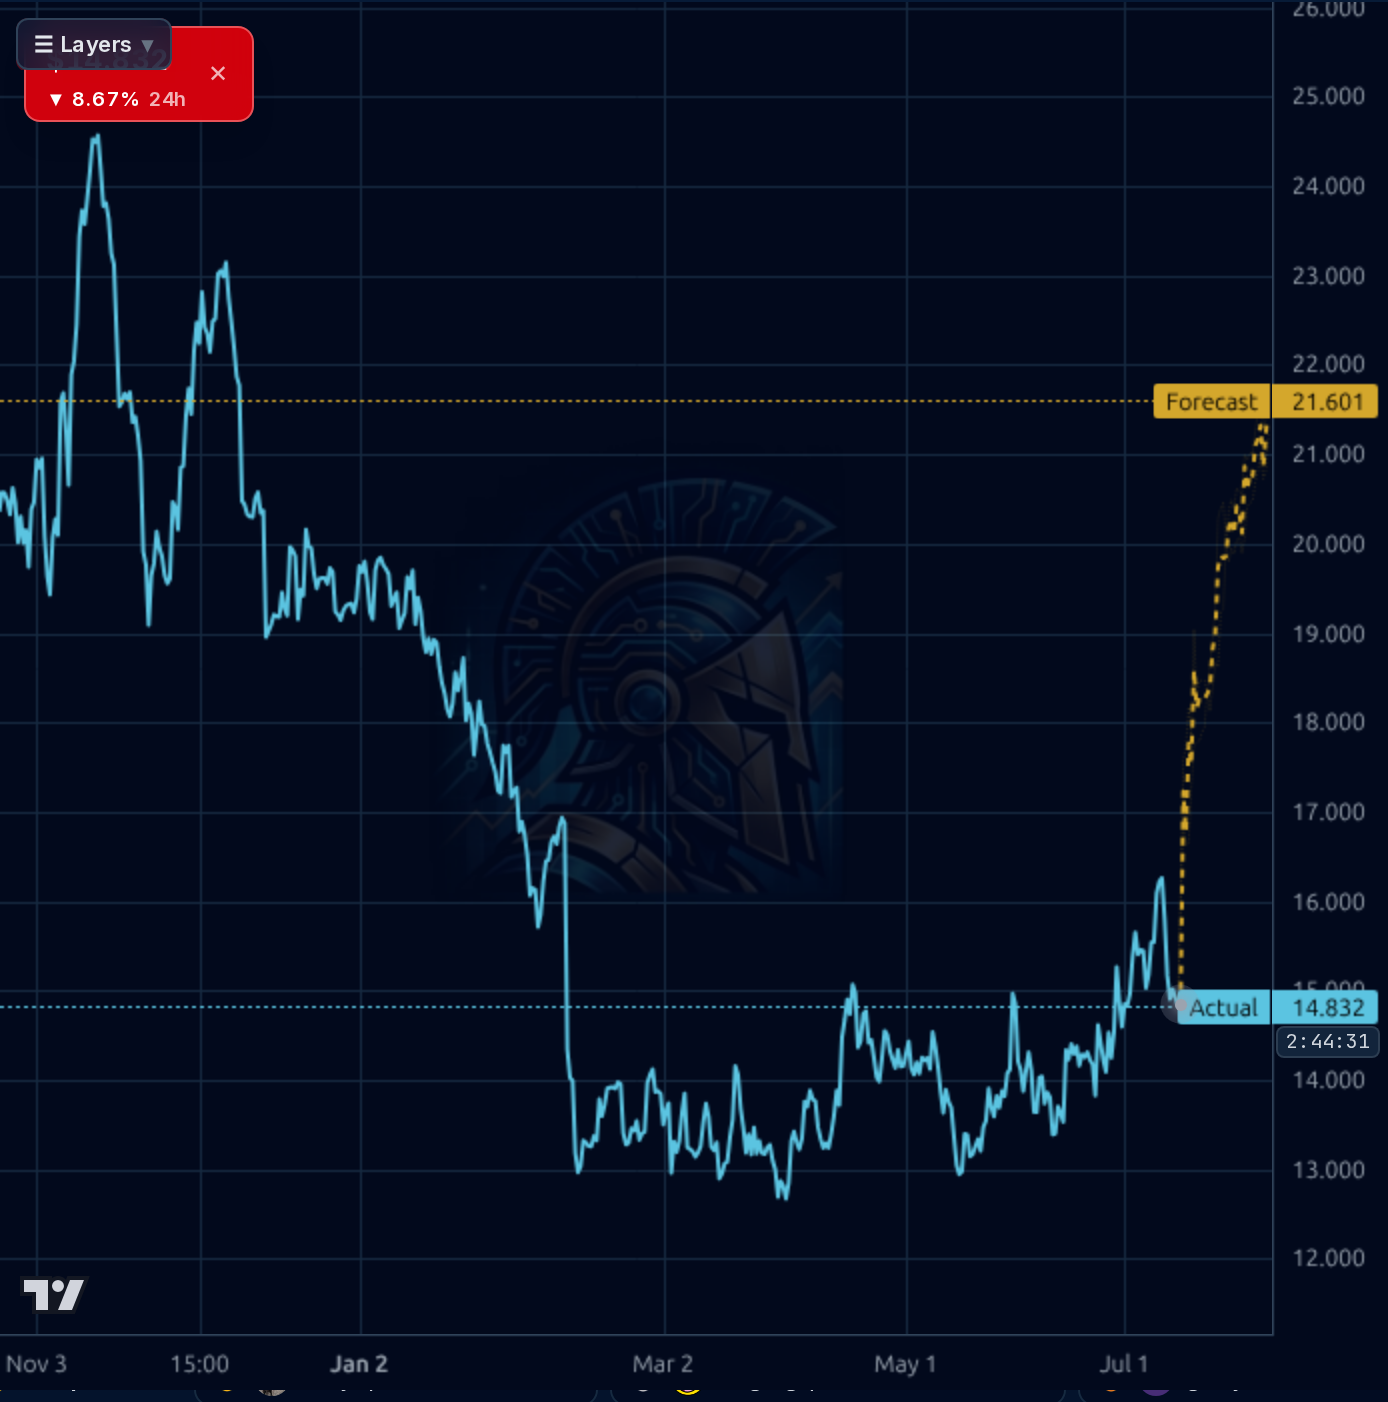
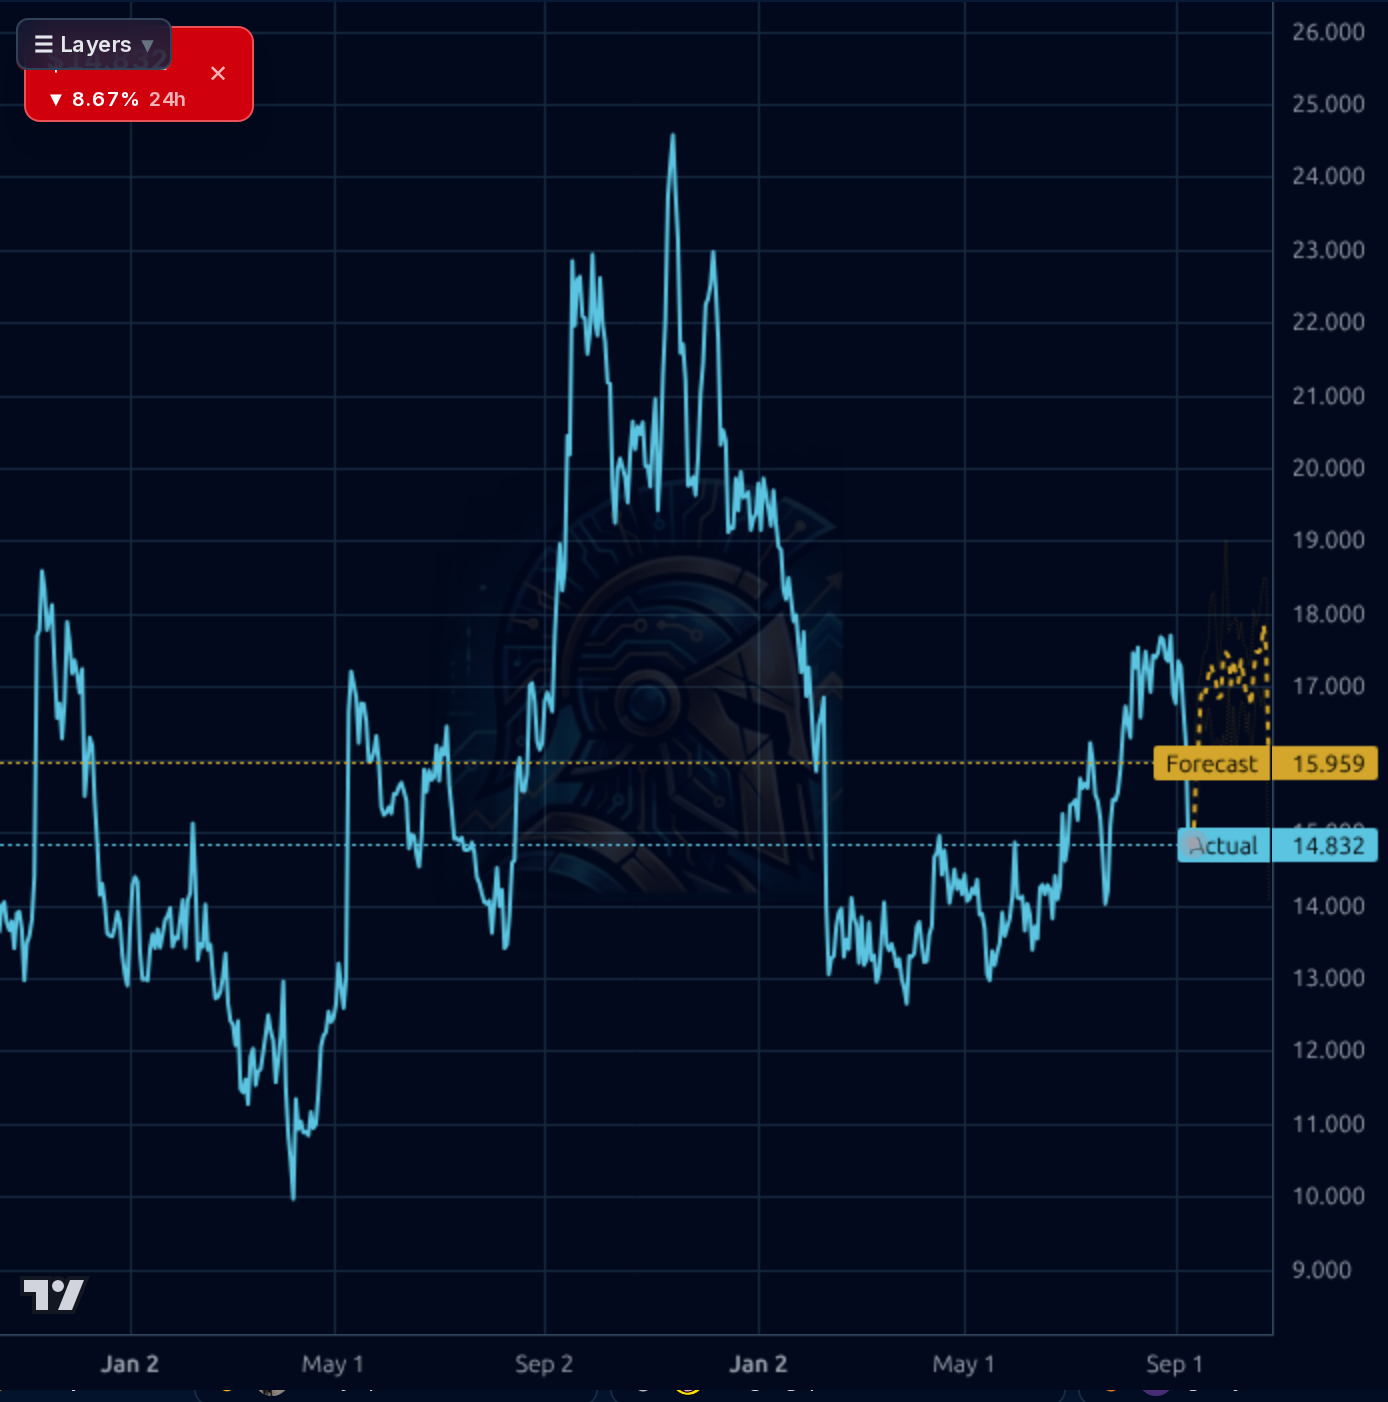
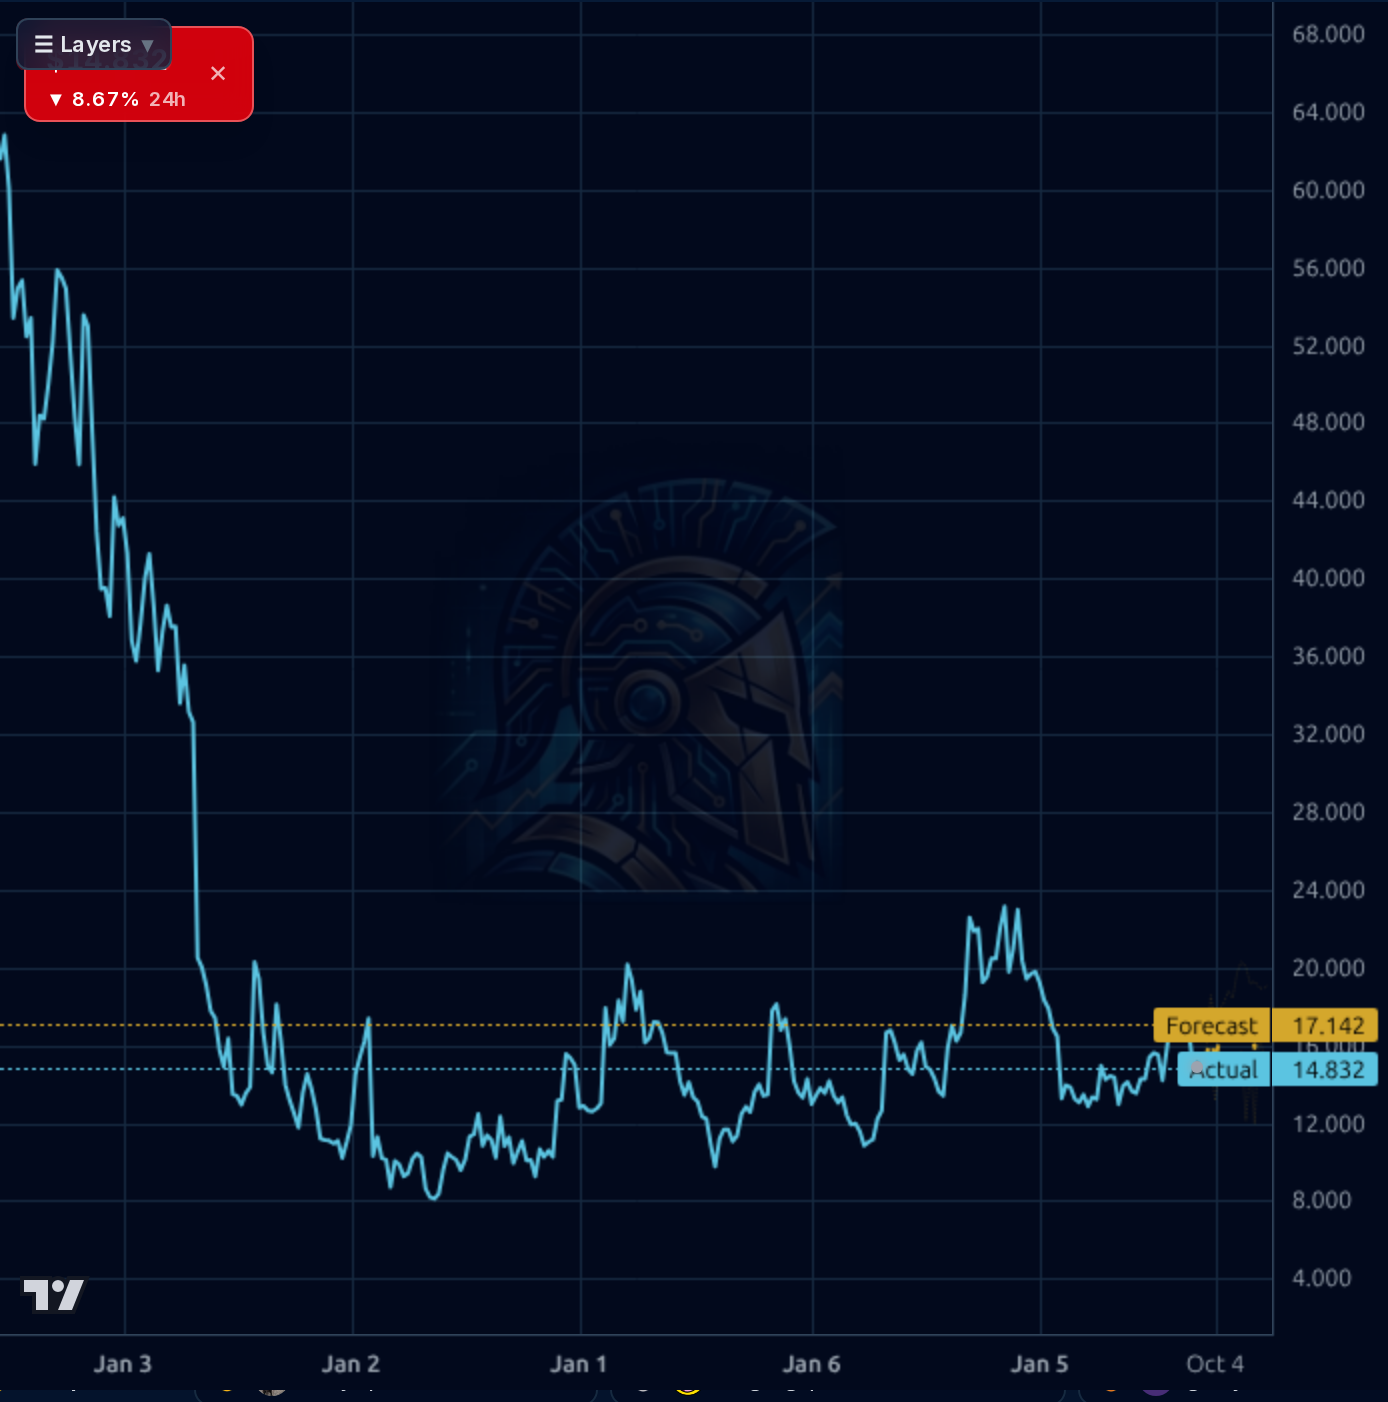
Wait for confirmation of a breakout above $17-$17.50 resistance level on increased volume; otherwise, treat the area near $14.20 (200DMA) as immediate support for accumulation attempts. Size positions cautiously due to high volatility.
The thesis hinges on demonstrating sustained operating margin improvement toward 5%+ and quantifying AV revenue contribution over the next two quarters. If margins remain volatile or negative, the stock will struggle to justify its valuation premium despite FCF generation. A clear capital allocation plan from new CFO Brous is critical.
The long-term viability depends on successfully monetizing media assets and scaling autonomous vehicle services beyond initial markets. The biggest structural risk remains managing working capital liabilities without diluting equity holders.
The company shows positive momentum in revenue growth (16% Y/Y) and improving gross margins (Q2 GM at 49.7%). Free Cash Flow remains robust at $1.15B TTM, suggesting capital generation capability. However, the balance sheet is concerning: a negative working capital of -$2.02B and a Current Ratio of 0.59 indicate significant short-term liquidity risk, potentially due to insurance reserves. While profitability metrics like ROE (152.6%) look strong on paper, they are likely distorted by non-recurring items or accounting treatments, making the sustainability of operating margins (which fluctuated between 2.6% and -0.3% in recent quarters) the primary concern.
The charts show significant volatility with clear historical support/resistance zones around $15-$17. The current price action is below key technical levels, as evidenced by the model's forecast bands on both timeframes. While there are signs of short-term bounce potential (as noted in social sentiment), the overall trend remains choppy and lacks conviction above recent lows. The divergence between the high historical volatility and the relatively low RSI (33.60) suggests caution, as momentum indicators are not strongly confirming a breakout.
The news flow is mixed: on one hand, there's positive operational development with Waymo integration in Nashville, signaling future revenue streams. On the other hand, competitive pressure remains high, highlighted by Scotiabank favoring Uber and DoorDash over Lyft. Management changes, such as the CFO transition to Michael Brous, are routine but require monitoring for strategic shifts. The insider selling cluster is a persistent headwind that must be weighed against positive operational catalysts.
- Waymo/AV integration via Flexdrive, starting in Nashville, represents a scalable new revenue channel that needs quantifiable expansion metrics.
- Lyft Media monetization efforts, such as the United Airlines partnership, must prove they can generate predictable, high-margin revenue streams to offset core ride-hailing margin compression.
- Negative working capital (-$2.02B) and low current ratio (0.59) pose an immediate liquidity risk.
- Operating margin fragility remains the single largest overhang; failure to improve this metric invalidates most bullish valuation models.
- Intense competitive pressure from Uber's scale and ongoing market share battles.
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord