MNDY — AI Stock Forecast & Price Targets
Published 9/11/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live MNDY price forecast →
MNDY is a high-quality SaaS franchise (89% GM, ~21% FCF margin, ~$616M net cash) trading at ~12.7x forward P/E and 0.58 PEG after a -55% one-year drawdown, but Q3 guidance disappointment and a 20% RIF/AI-pivot have left the tape in a downtrend with price ($85.17) sitting below the 20/50/200-day SMAs. The setup favors staged accumulation into the $78-82 zone rather than chasing here — near-term technicals and a heavy 18% short float argue for patience, while long-term unit economics and buyback optionality anchor a constructive multi-year view.
1-4 weeks: HOLD/nibble discipline. Do not chase $85 with the tape below all key MAs and Q3 guide overhang unresolved. Preferred entry zone $78-82 (aligns with base structure and prior support). Invalidation on a daily close below $76 opens $70-72. Upside cap into $88-92 resistance where I'd fade any low-volume rip. Position sizing: no more than 1/3 of a target position here, saving ammo for a retest of $80 or a squeeze-clearing move above $92 on volume.
1-6 months: ACCUMULATE bias. Base case: mean reversion to $95-100 (fwd P/E ~15x, closer to sell-side $106 target) as buybacks retire float and Q3 print (Nov 9) resets the guidance bar. Expected return range from $80 entry: +18-25% base, -10% bear if Q3 disappoints again. Catalysts: AI ARR mix disclosure at Q3, RPO/cRPO re-acceleration, buyback pace, potential short squeeze given 18% short float. Change my mind: NDR falls below 105%, RPO growth decelerates below 20%, or FCF margin compresses below 15% — any would break the quality-at-a-price thesis.
1-3 years: constructive. If MNDY holds 20%+ revenue growth with 20%+ FCF margin and successfully monetizes AI Work Platform to a meaningful ARR mix, this is a $150-180 stock at 4-5x sales on ~$2B revenue. Multi-year drivers: enterprise multi-product attach (NDR >115% in that cohort), international expansion, AI-native workflow layer. Biggest structural risk is AI-induced disruption cutting both ways — LLM-native competitors (or hyperscaler bundling) could commoditize the Work OS layer, and if SEO/search-driven acquisition permanently breaks, CAC economics deteriorate and the buyback-supported floor gives way.
The fundamentals remain best-in-class: Q2 2026 revenue of $364.6M (+22% YoY, +3.8% QoQ) with 88.3% gross margin, and TTM revenue of $1.37B (+24%). Operating margin is modest at 5.5% GAAP, but FCF is robust — $50.5M in Q2 and $101.8M in Q1 for a ~21% TTM FCF margin. The balance sheet is a fortress with $853M cash vs $237M debt (net cash ~$616M, or ~$14/share, ~17% of market cap), current ratio 1.53, and ROIC 14.6%. Capital allocation shifted decisively: aggressive buybacks (~7.27M shares/$553M retired) drove cash down from $1.5B at YE 2025 to $853M by mid-2026, while equity dropped from $1.25B to $618M — accretive at these multiples but reduces the cash cushion buffer. Valuation is genuinely cheap for a Rule-of-40 SaaS name: 12.7x fwd P/E, 2.6x P/S, 2.0x EV/Sales, PEG 0.58. What's broken is the growth deceleration narrative — Q3 guide fell short of expectations, and the AI-pivot restructuring (20% RIF) is an admission that go-to-market economics need reworking amid AI/SEO disruption to top-of-funnel.
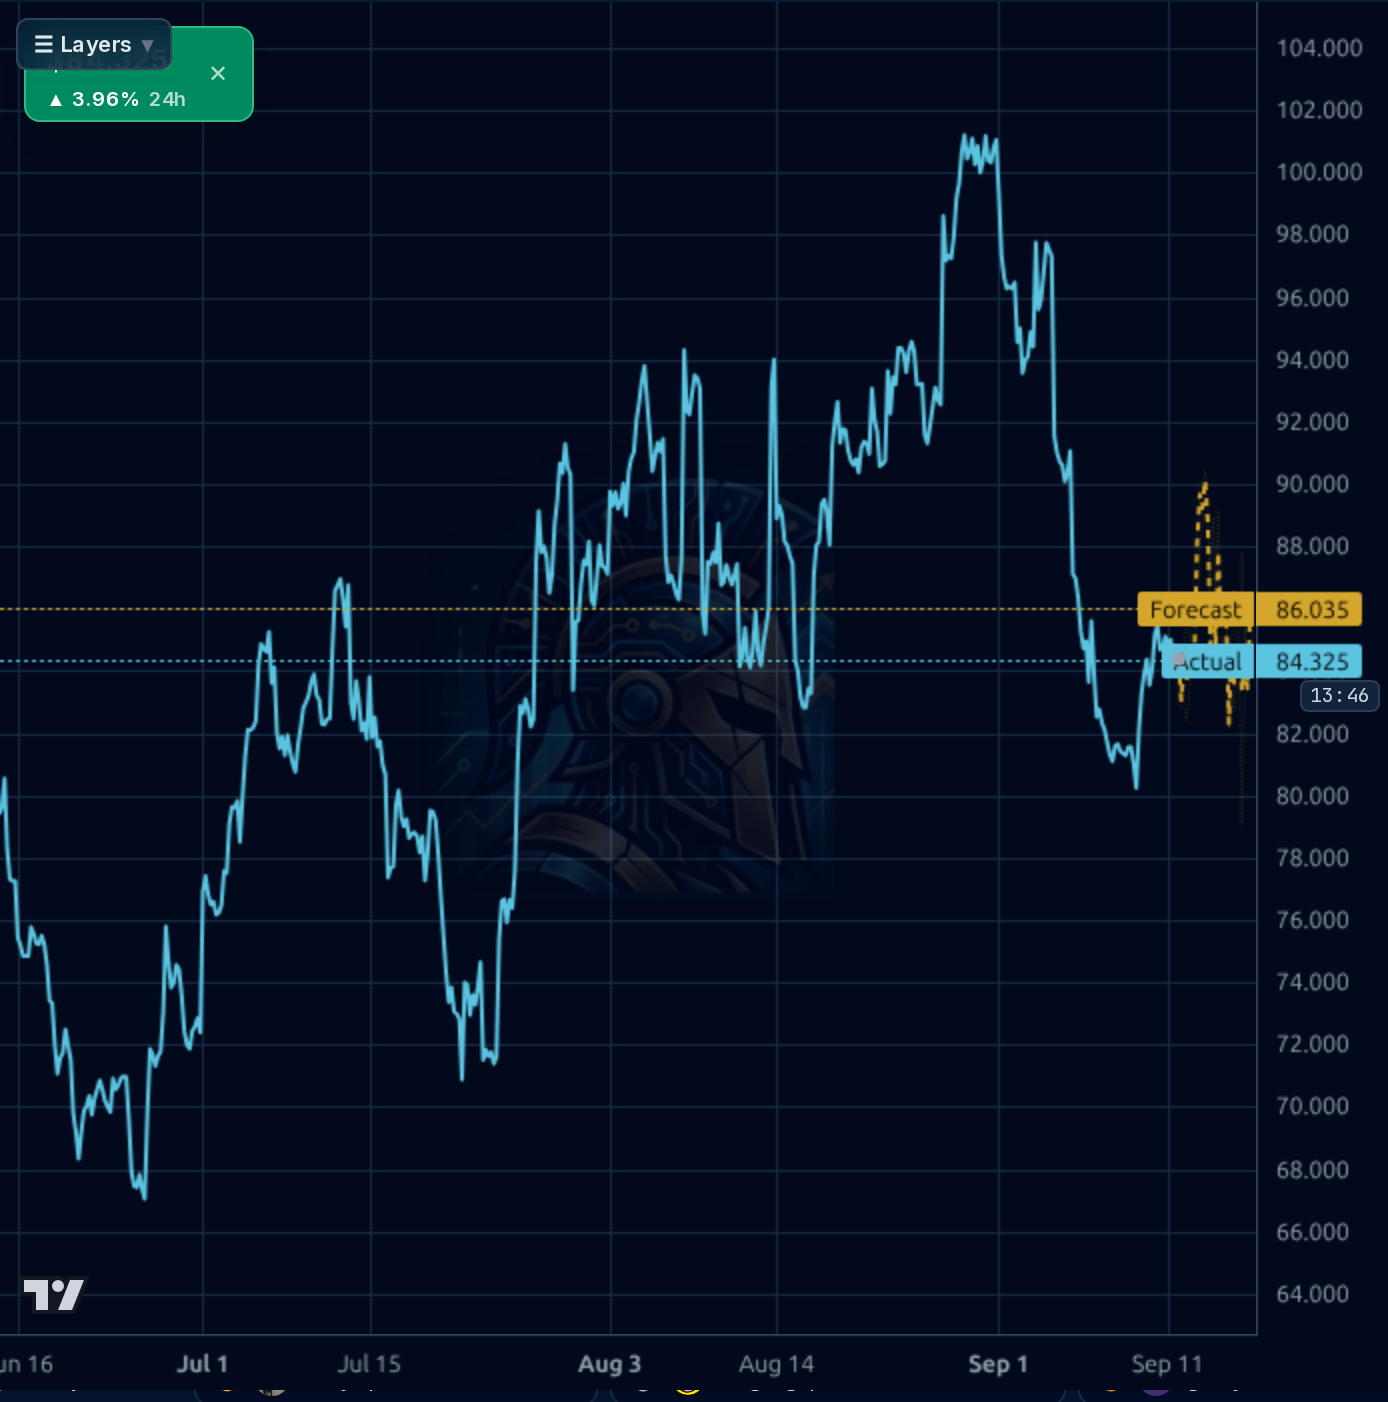
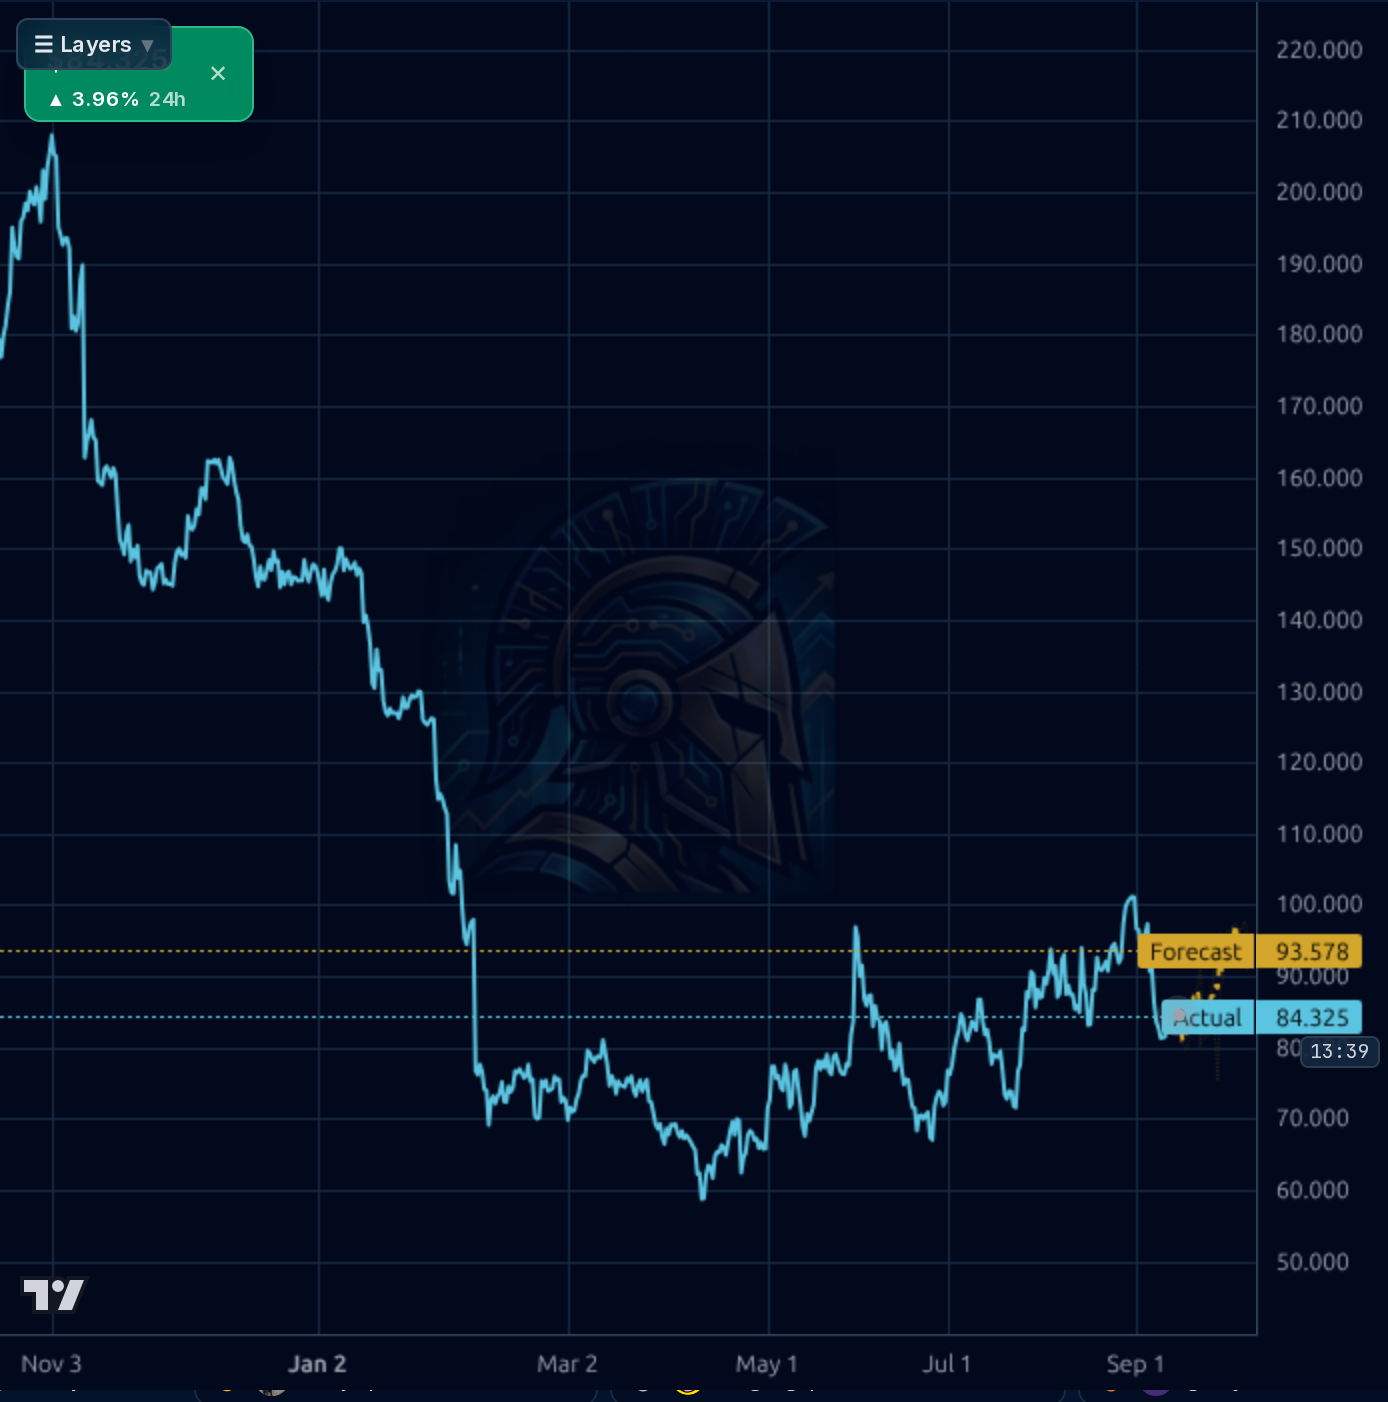
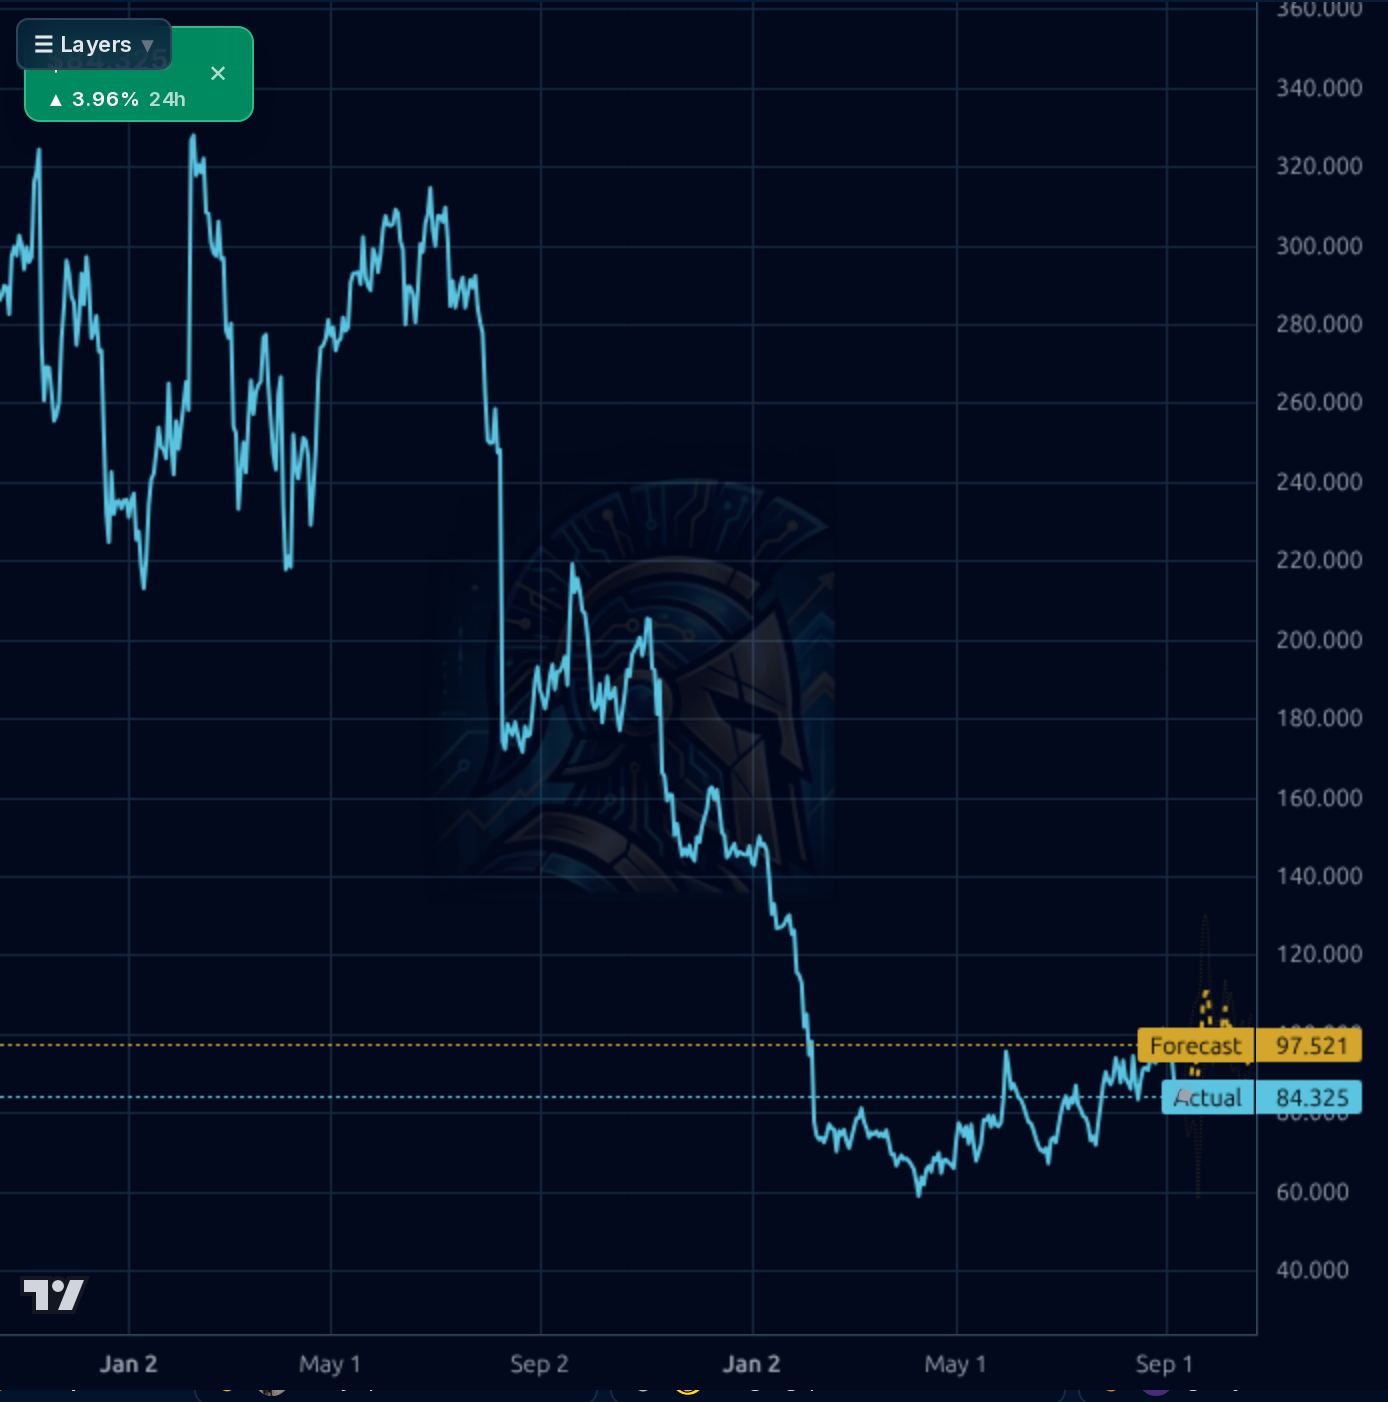
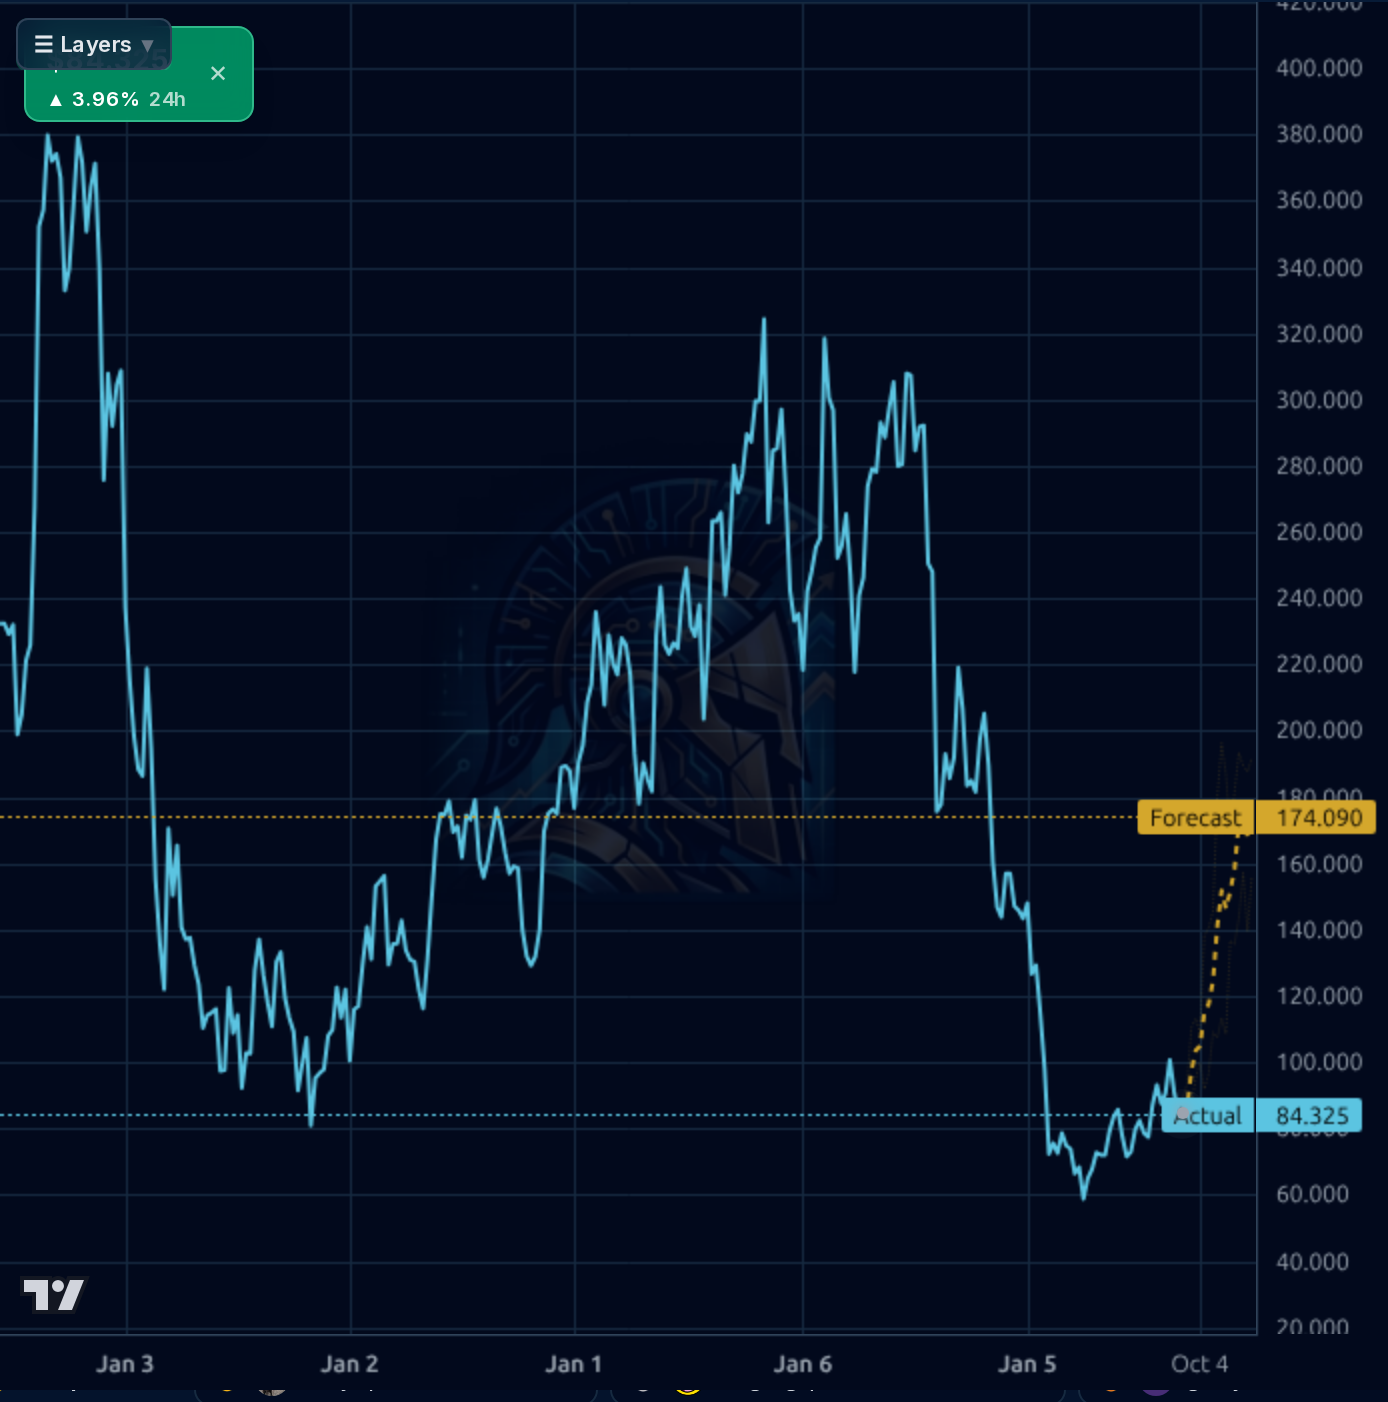
The tape is in a clear downtrend across timeframes. On the daily/weekly, MNDY sits at $85.17, deep below the 52-wk high of $220.80 (-61%) with SMA200 -9.4%, SMA50 -1.8%, SMA20 -7.3% — all below price except a marginal bounce off the $80 low. The 1h chart shows a violent September gap-down from ~$100 to a $80 low, with a modest reclaim to $85 but the forecast band pointing to a wide $82-89 range (Kronos 1h forecast $86, but 1d forecast $97 and 1wk forecast $174 look increasingly optimistic and detached — MAPE at longer horizons blows out to 30%+). RSI 44.7 is neutral, not oversold. Key support: $80 (recent low, must hold), then $76-78 (multi-month base zone visible on daily). Key resistance: $88-92 (prior consolidation), then the $100 gap-fill and SMA50. The 1wk directional accuracy of the model (67%) doesn't exceed the naive baseline (67%), so the aggressive $174 1wk forecast should be heavily discounted. Short float at 17.97% (short ratio 4.18) is a coiled-spring risk in either direction — a squeeze catalyst above $92 is real, but shorts are pressing for a reason.
Signal: Q2 2026 reported strong ($364.6M revenue +22%, record non-GAAP OI, return to net profitability) but Q3 guidance came in below Street, triggering the recent sell-off; the AI Work Platform launched in May and OneAI acquisition point to a real product/monetization pivot, while the ~$553M buyback is meaningful capital return. Sell-side is constructive on average (Recom 1.88, target $106.45 implying +25%) — Wall Street has not capitulated. Recent Zacks/analyst attention flow suggests ongoing narrative reset rather than a stabilized view. Noise: legacy $282 price targets in some databases are stale; conflicting reports of the post-earnings move magnitude; social sentiment is bifurcated between value-hunters and short-sellers. Insider activity is a small CRO sale ($62k) — not material. Fundamental-change flags show short float has swung between 13.8% and 20.2% — the crowd cannot agree on this name, which is itself a signal that the setup is contested and event-sensitive into the Nov 9 earnings print.
- AI Work Platform (launched May 2026) monetization ramp — targeting 15-20% of net-new bookings by year-end per prior guide
- OneAI acquisition integration expanding AI-native product surface area
- RPO $937M (+34%) and cRPO $750M (+27%) growing well ahead of reported revenue — implies bookings-led re-acceleration potential
- Multi-product attach (Work Management, CRM, Dev, Service) driving >115% NDR in large enterprise cohort
- $553M+ buyback already executed, retiring ~15%+ of float — EPS accretive with $853M cash still on hand
- International expansion runway (EMEA, APAC) against modest 3,155-employee base
- Q3 2026 guidance shortfall confirms deceleration to 16-17% — Nov 9 earnings is the next binary event
- 20% workforce reduction signals go-to-market economics are under pressure; execution risk on AI-pivot restructuring
- SEO/AI search disruption to top-of-funnel acquisition could permanently raise CAC
- NDR reportedly normalizing toward ~108% — the SaaS quality premium erodes if this continues
- 18% short float and technical downtrend (below all key MAs) create ongoing overhead supply
- Legacy sell-side price targets ($282 in some databases) are stale — real consensus target is $106, and further downward revisions possible
- Cash position dropped from $1.5B to $853M in two quarters due to buybacks — less optionality if macro/execution worsens
- Israeli-domiciled foreign private issuer — geopolitical risk premium can flare unpredictably
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord