OWL — AI Stock Forecast & Price Targets
Published 9/10/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live OWL price forecast →
Blue Owl Capital has sold off hard (-44% YoY, -30% YTD) as private credit sentiment weakened and the market questions the 828% payout ratio and 132x trailing P/E. However, forward P/E of 10.6, a 6.5% yield, oversold RSI of 36.9, and a credible new data-center REIT catalyst ($6.5B seed) create an asymmetric setup near $10.43 — attractive for accumulation despite lingering cycle risk.
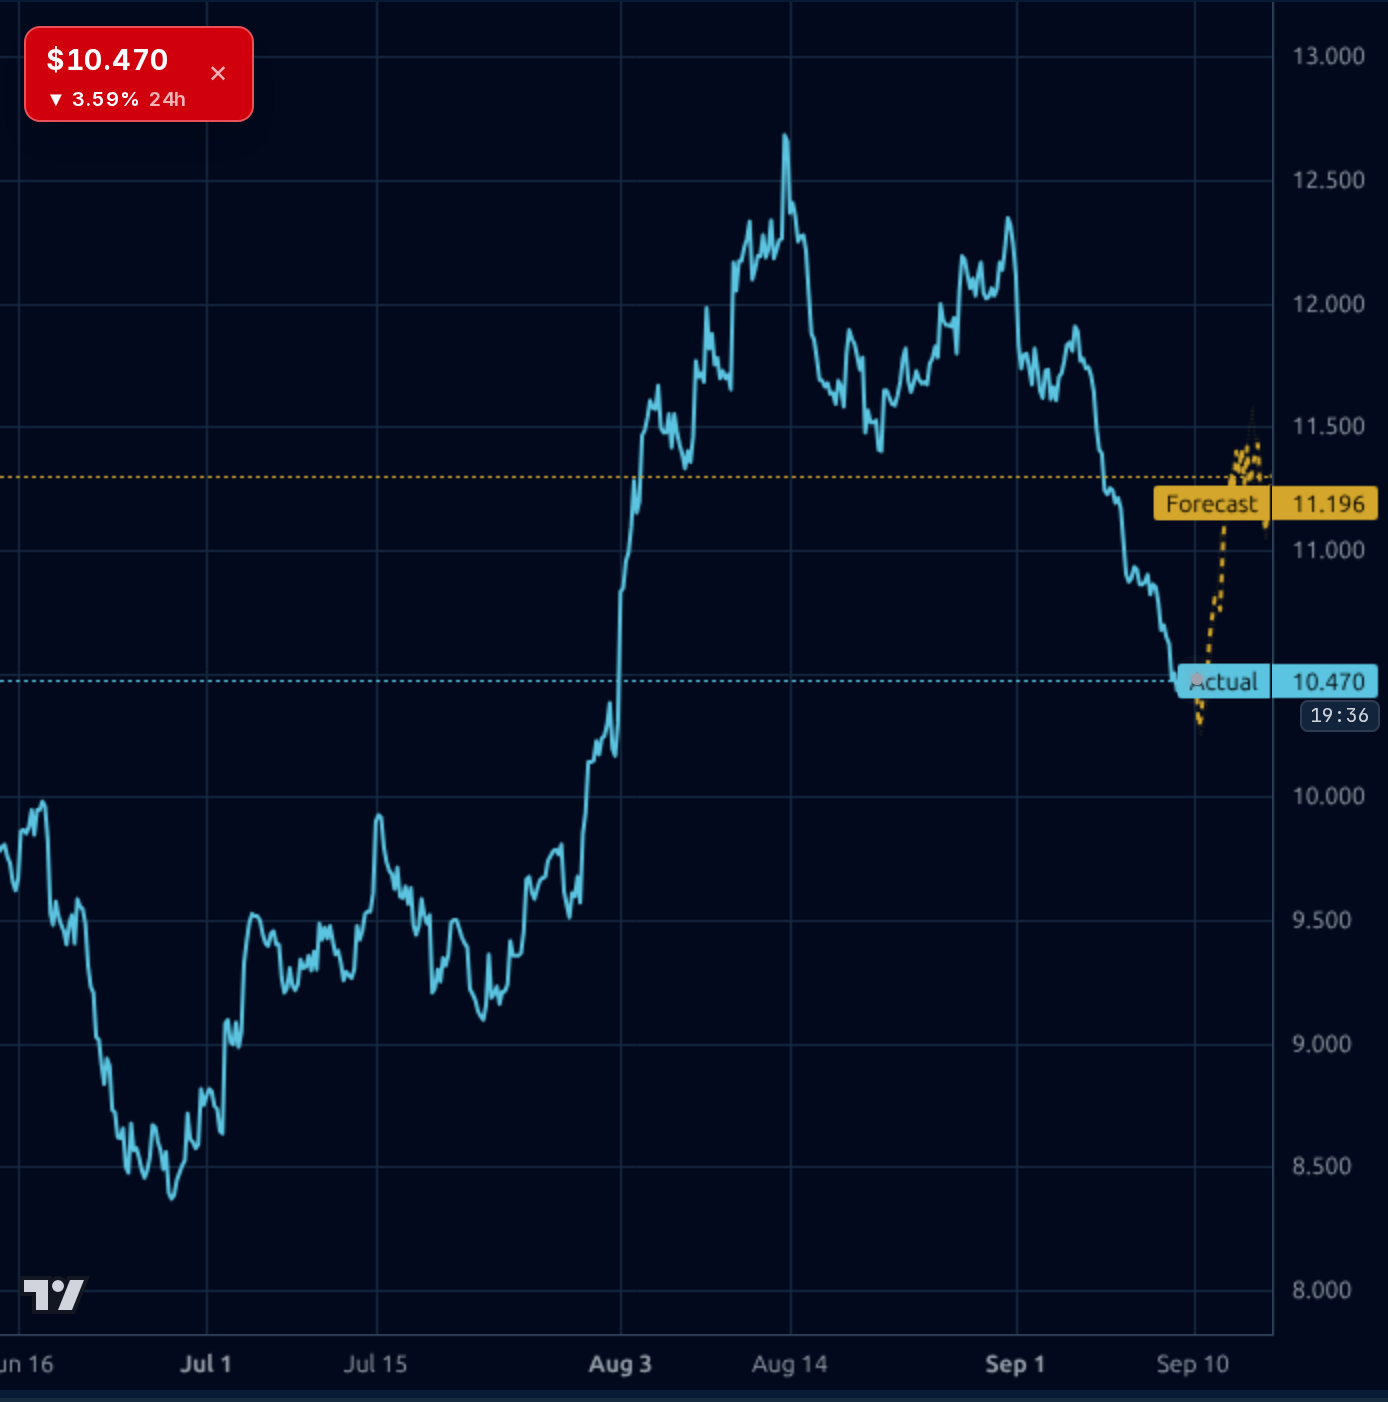
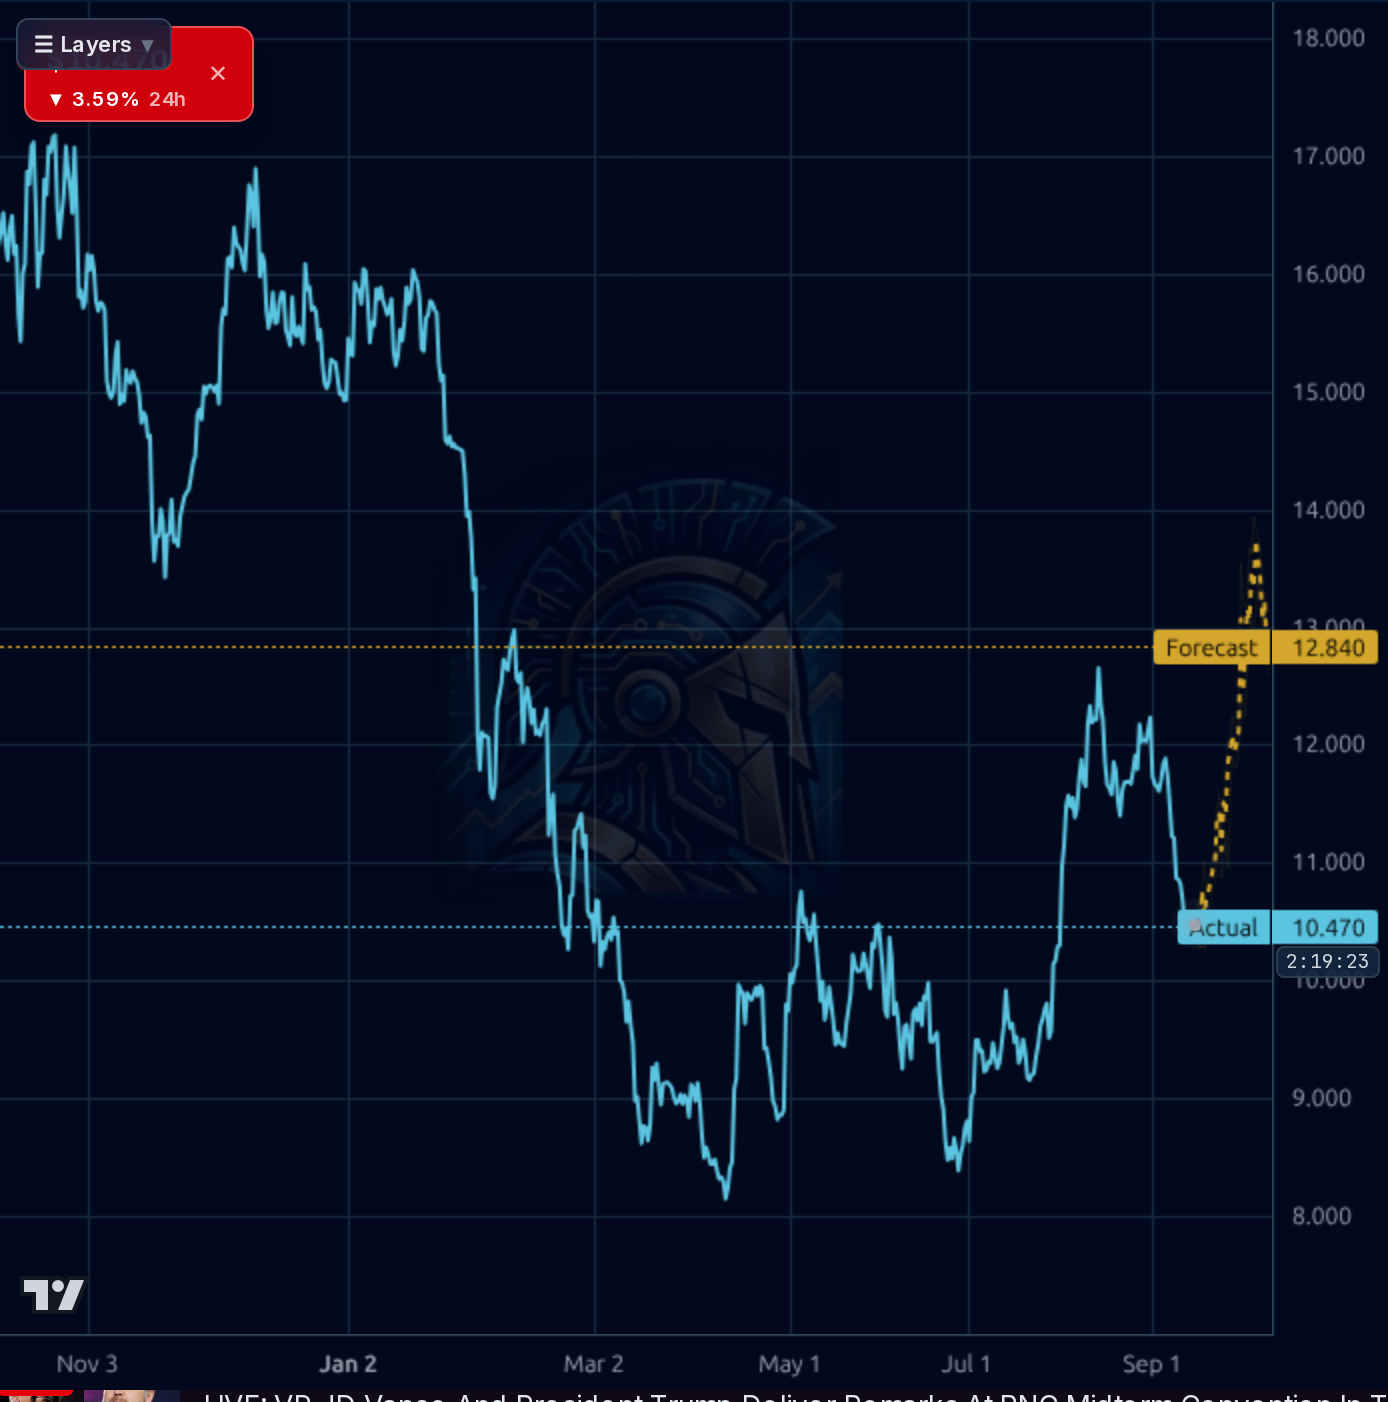
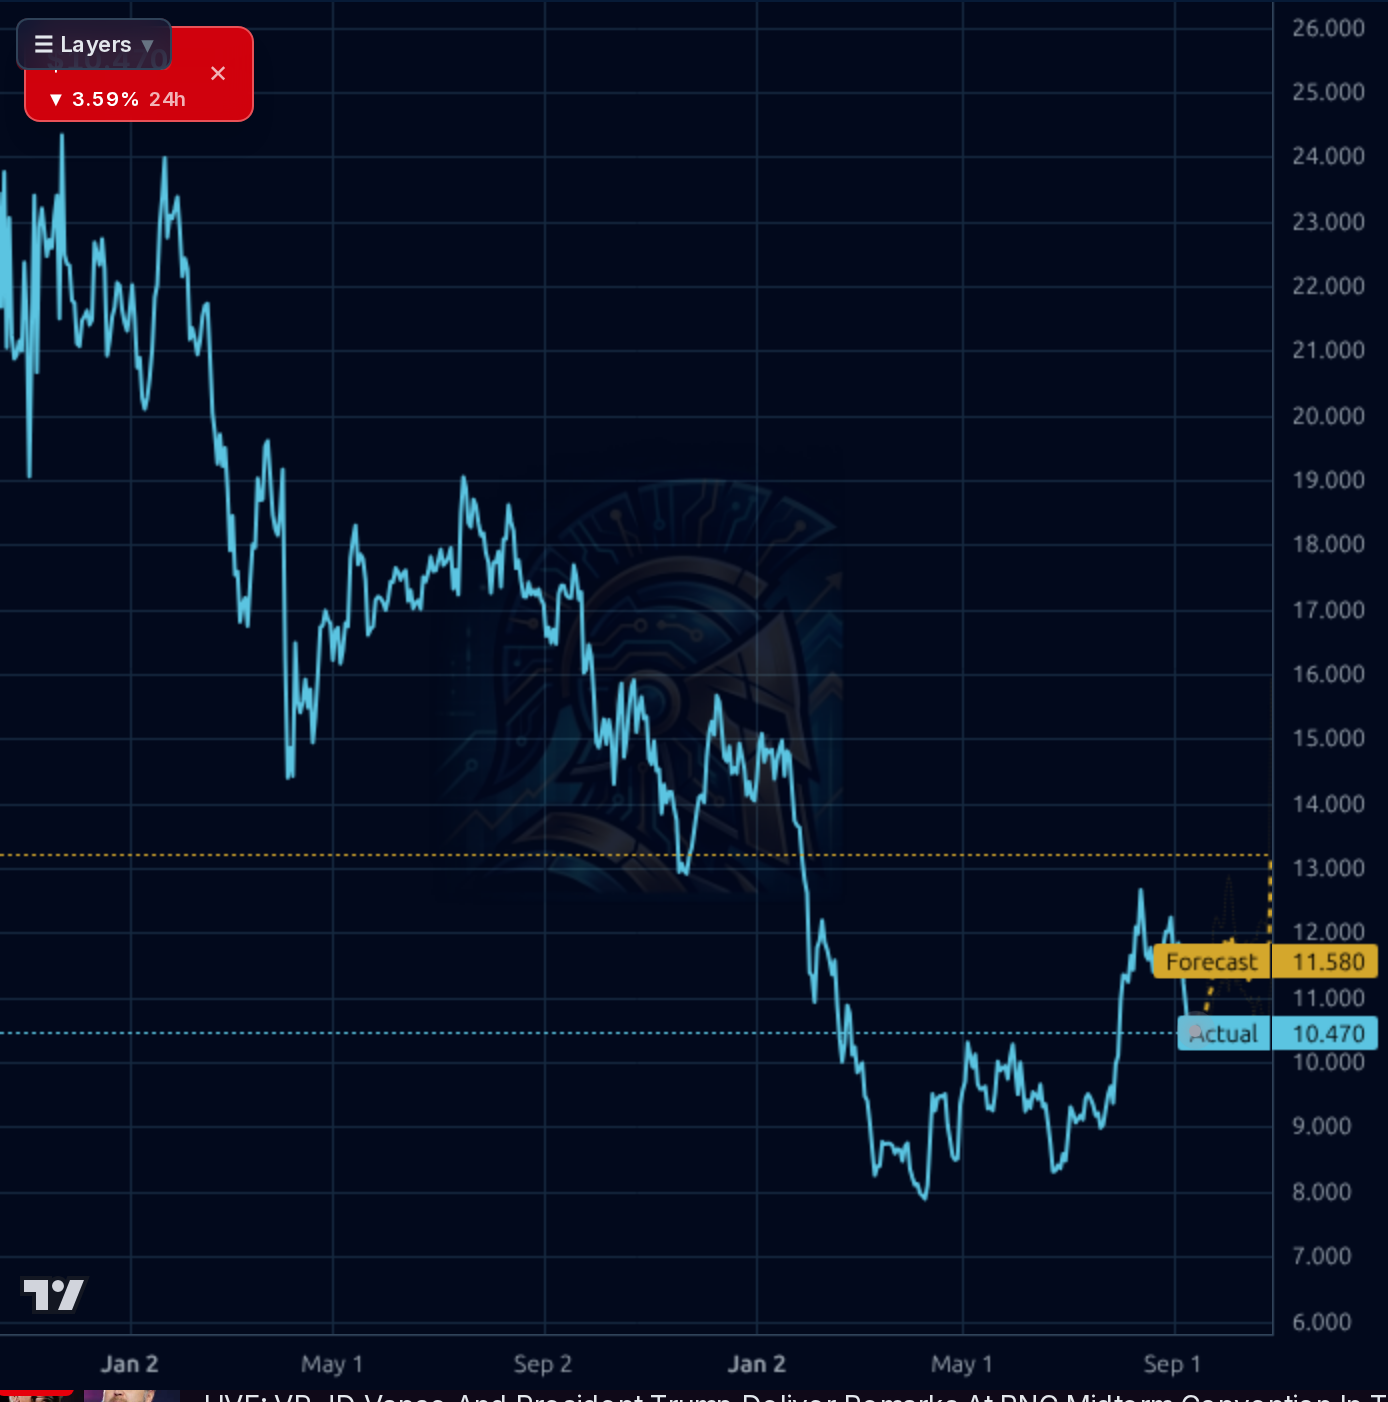
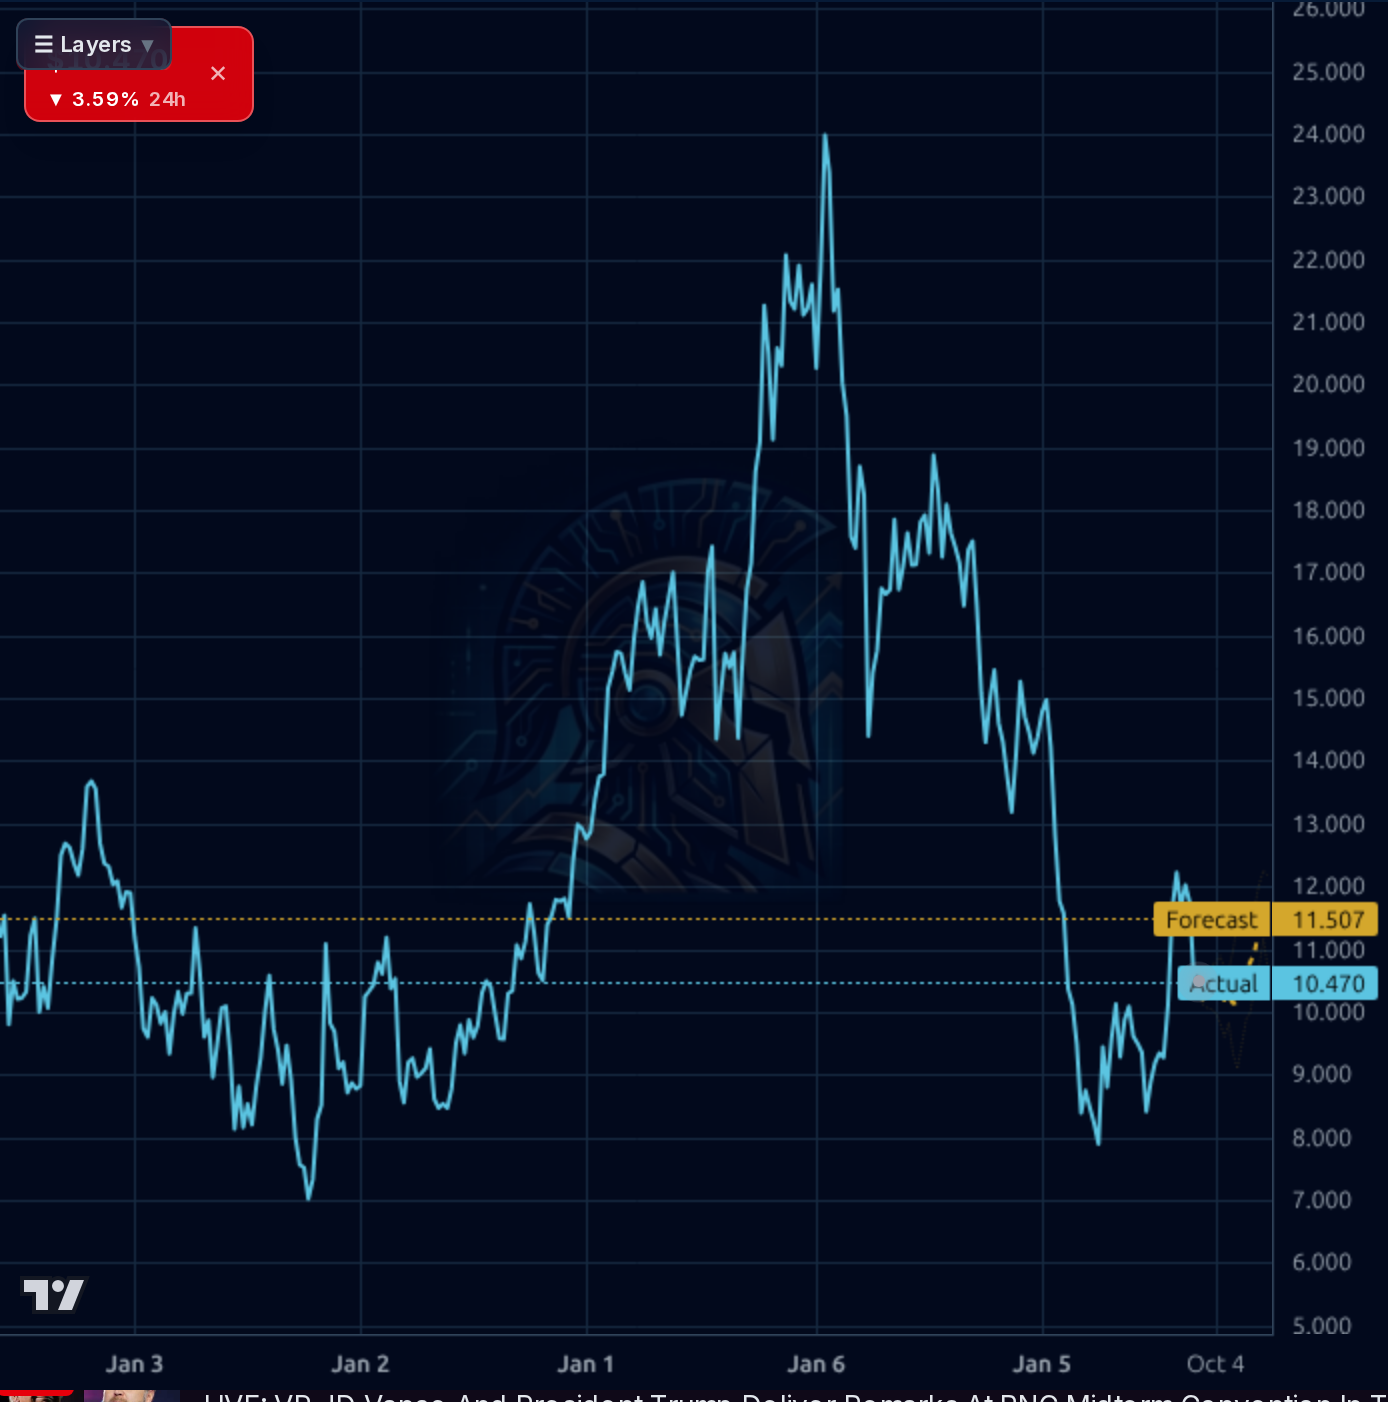
Stock is oversold (RSI 36.9) at prior support ($10.47) with a 5.39 short ratio and 16.9% short float — set-up for a mean-reversion bounce toward $11.00-$11.50. Starter long only, size 1/3 of intended position. Invalidation: daily close below $9.90 (breakdown from June-July base). Don't chase above $11.50 without volume confirmation.
Over 1-6 months, the data-center REIT launch and Q3 earnings on 10/29 are the two binary catalysts. If FRE growth and inflows re-accelerate and the REIT spinout is well-received, re-rating to 12-13x forward EPS puts fair value at $11.80-$12.80. Expected return range: -15% to +25%. Change my mind: a dividend cut announcement, another quarter of margin compression below 14% operating, or a spike in short interest above 20%.
1-3 year thesis rests on Blue Owl's ability to compound AUM in permanent-capital vehicles (GP stakes, net lease, direct lending) while pivoting a meaningful portion into AI infrastructure via the data-center REIT. If successful, this is a mid-teens EPS grower deserving 15-18x, implying $15-$20. Biggest structural risk: a private credit default cycle that impairs NAVs across the direct-lending book and triggers redemption spirals — the 2.18 D/E and 828% payout leave no buffer for that scenario.
Revenue is stable but no longer accelerating — the last four quarters printed $728M, $756M, $754M, $753M, so sequential growth has flattened, and the sales-growth estimate was just cut from 19.3% to 14.1%. Margins compressed sharply Q/Q: gross margin fell from 58.5% in Q4'25 to 52.3% in Q2'26, operating margin from 22.1% to 15.5%, and net income collapsed to just $11.4M on $753M revenue (1.5% net margin). Trailing EPS of $0.11 against a $0.91 TTM dividend produces the flagged 828% payout ratio — this is only sustainable if the forward EPS of ~$0.99 (implied by 10.6x fwd P/E) actually materializes. Balance sheet is levered (D/E 2.18, $4.34B debt vs $2.0B equity) and the recent 8-Ks confirm $750M of new 2036 notes issued August 18 — refinancing, not deleveraging. Free cash flow is genuinely strong ($1.55B TTM, $453M in Q2 alone) and covers the dividend on a cash basis, which is the key reason the payout hasn't been cut yet. Institutional ownership dropped 6pp to 93.8% — a real distribution signal.
All timeframes show a decisively broken uptrend. On the daily/weekly, OWL is 45.9% below its 52-week high of $19.29 and has retraced almost the entire 2024-2025 rally. The 1h chart shows a clean rejection from ~$12.70 in mid-August and a fast descent to $10.47, closing right on prior June-July support. RSI at 36.9 and price -10.8% below the 20-SMA / -8.5% below the 200-SMA signal an oversold but downtrending tape. The Kronos forecast band points modestly higher across 1h/4h/1d/1wk ($11.20-$12.84), but the reliability data is damning: 1d directional accuracy 53% vs 62% naive baseline, 1wk 33% vs 67% — the model is beaten by naive in this regime, so the forecast should be discounted heavily. Key support: $10.00 psychological, then $8.00 (weekly swing low). Resistance: $11.00, then $12.00-$12.30, then the $13 declining trendline.
The dominant catalyst is Blue Owl's plan to seed a public data-center REIT with ~$6.5B of assets (multiple 9/5-9/8 headlines) — this is a legitimate structural pivot into AI infrastructure and directly aligns with a thematic secular tailwind. Q2'26 adjusted EPS of $0.34 beat, share buybacks continue, and Blue Owl Technology Finance expanded debt capacity. However, one Simply Wall St piece (9/6) explicitly argues the stock is 'still fully priced' after the drawdown, and Zacks (9/9) rates it neutral citing rate sensitivity and NAV pressure. Signal: the data-center REIT is a real re-rating catalyst; noise: retail social sentiment is 100% bullish (contrarian caution), and Morningstar's PT cut to $10 was flagged by retail as a capitulation moment.
- Data-center REIT seeded with ~$6.5B assets targeting AI infrastructure demand (announced Sept 2026)
- Blue Owl Technology Finance expanded via new $750M 2036 note issuance (8-K, 8/18/26)
- European net lease fund closing (~€1.6B) supporting fee-related earnings
- Q2'26 adjusted EPS of $0.34 beat with continued share repurchase authorization
- Forward EPS estimate of ~$0.99 implies 9x growth off $0.11 trailing — significant operating leverage if realized
- 828% dividend payout ratio on GAAP EPS — cash-covered today but any FCF slippage triggers cut risk
- Debt/Equity of 2.18 with $4.34B total debt; new 2036 notes add covenants that limit flexibility
- Short float 16.9% and institutional ownership just fell 6pp to 93.8% — real distribution occurring
- Sales growth estimate cut from 19.3% to 14.1% signals decelerating fundamentals
- Private credit cycle risk — NAV markdowns at OBDC (reportedly ~20% below NAV) could cascade
- Model directional accuracy (53% 1d, 33% 1wk) is below naive baseline — forecast band is unreliable in this regime
- Q4 2026 broader breadth deteriorating (46.7% >200dMA) — asset managers underperform in risk-off tapes
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord