PATH — AI Stock Forecast & Price Targets
Published 9/16/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live PATH price forecast →
UiPath sits at $13.63 after round-tripping from an $18+ pre-earnings extreme, punished by a Q3 FY27 guide miss even as fundamentals (83% gross margin, $474M TTM FCF, $1.28B net cash, GAAP profitable) remain intact. With RSI at 40, short float still elevated at 26%, and Citi/Gartner tailwinds emerging into a Dec 2 print, this is a classic PATH setup: oversold enough to accumulate cautiously, but the sub-$13 break risk is real given a risk-off tape and the CEO's well-timed $22.5M August sale at $18.
Accumulate in tranches between $13.00–13.70 with a hard invalidation on a daily close below $12.80 (which would open $12.00 and then $10.20). Starter size ~1/3 position here, add 1/3 on a tag of $12.50 if it comes with RSI <32, keep 1/3 dry for either a squeeze reclaim of $14.65 (add-on breakout) or a capitulation into $11. Do not chase strength above $15 — the CEO sold at $16 and the model's near-term forecast points lower. Expect chop; the ~30% short float and 5.8% daily volatility make ±5% days routine.
1–6 month base case is a range trade between $12 and $16 with the Dec 2 earnings print as the binary catalyst. Bull path: new CFO resets guidance conservatively (bar lowered), Maestro ACV gets disclosed, buyback authorization is announced, and the stock squeezes back to $17–19 as shorts cover; that setup is a legitimate 25–40% upside from here. Bear path: guide-down cascade, growth deceleration confirmed below mid-teens, macro risk-off (breadth 42.7% >200dMA and deteriorating) drags the stock to $10–11 retest. I'd change my mind on a break-and-hold below $12 on volume (thesis break) or, conversely, on a formal buyback announcement (thesis accelerator).
1–3 year thesis rests on whether Maestro/agentic AI can re-accelerate top-line growth from mid-teens to 20%+ while defending against Microsoft Copilot Studio, ServiceNow AI Agents, and Salesforce Agentforce bundling the orchestration layer. If UiPath can convert its ~97% Fortune 500 install base into meaningful agentic ACV, the stock is worth $22–28 on a 6x revenue / 25x FCF frame. If hyperscalers commoditize orchestration, PATH becomes a $9–12 profitable-but-shrinking cash cow whose value is capped by capital return. Biggest structural risk is not execution — it's category compression: RPA as a standalone SKU is fading, and UiPath must sell an AI platform against companies that give the AI away.
The financial machine is genuinely strong: TTM revenue $1.72B growing 15% Y/Y, 82.6% gross margin, 21% net margin, ROE 20%, ROIC 17.9%, and a fortress balance sheet with $1.28B cash against $80M debt (Debt/Eq 0.04). TTM free cash flow of $474M supports a P/FCF of ~19.6 and forward P/E of 14.8 — reasonable for a GAAP-profitable software franchise. However, the quarter-over-quarter cadence exposes real lumpiness: Q2 FY27 revenue of $410M was down sequentially from Q4 FY26's $481M, operating margin compressed to 7.7% from 16.7% in Q4, and Q2 FCF of just $29M vs Q4's $179M is a stark reminder that the annual FCF headline masks quarterly volatility. EPS Q/Q of +2,279% is optically loud but flatters off a suppressed base. The new CFO transition disclosed in the Sept 3 8-K adds guidance-framework uncertainty into the December print, and no formal buyback authorization has been announced despite the cash pile and 23.8% insider ownership — a missed capital-return catalyst that would materially derisk the stock.
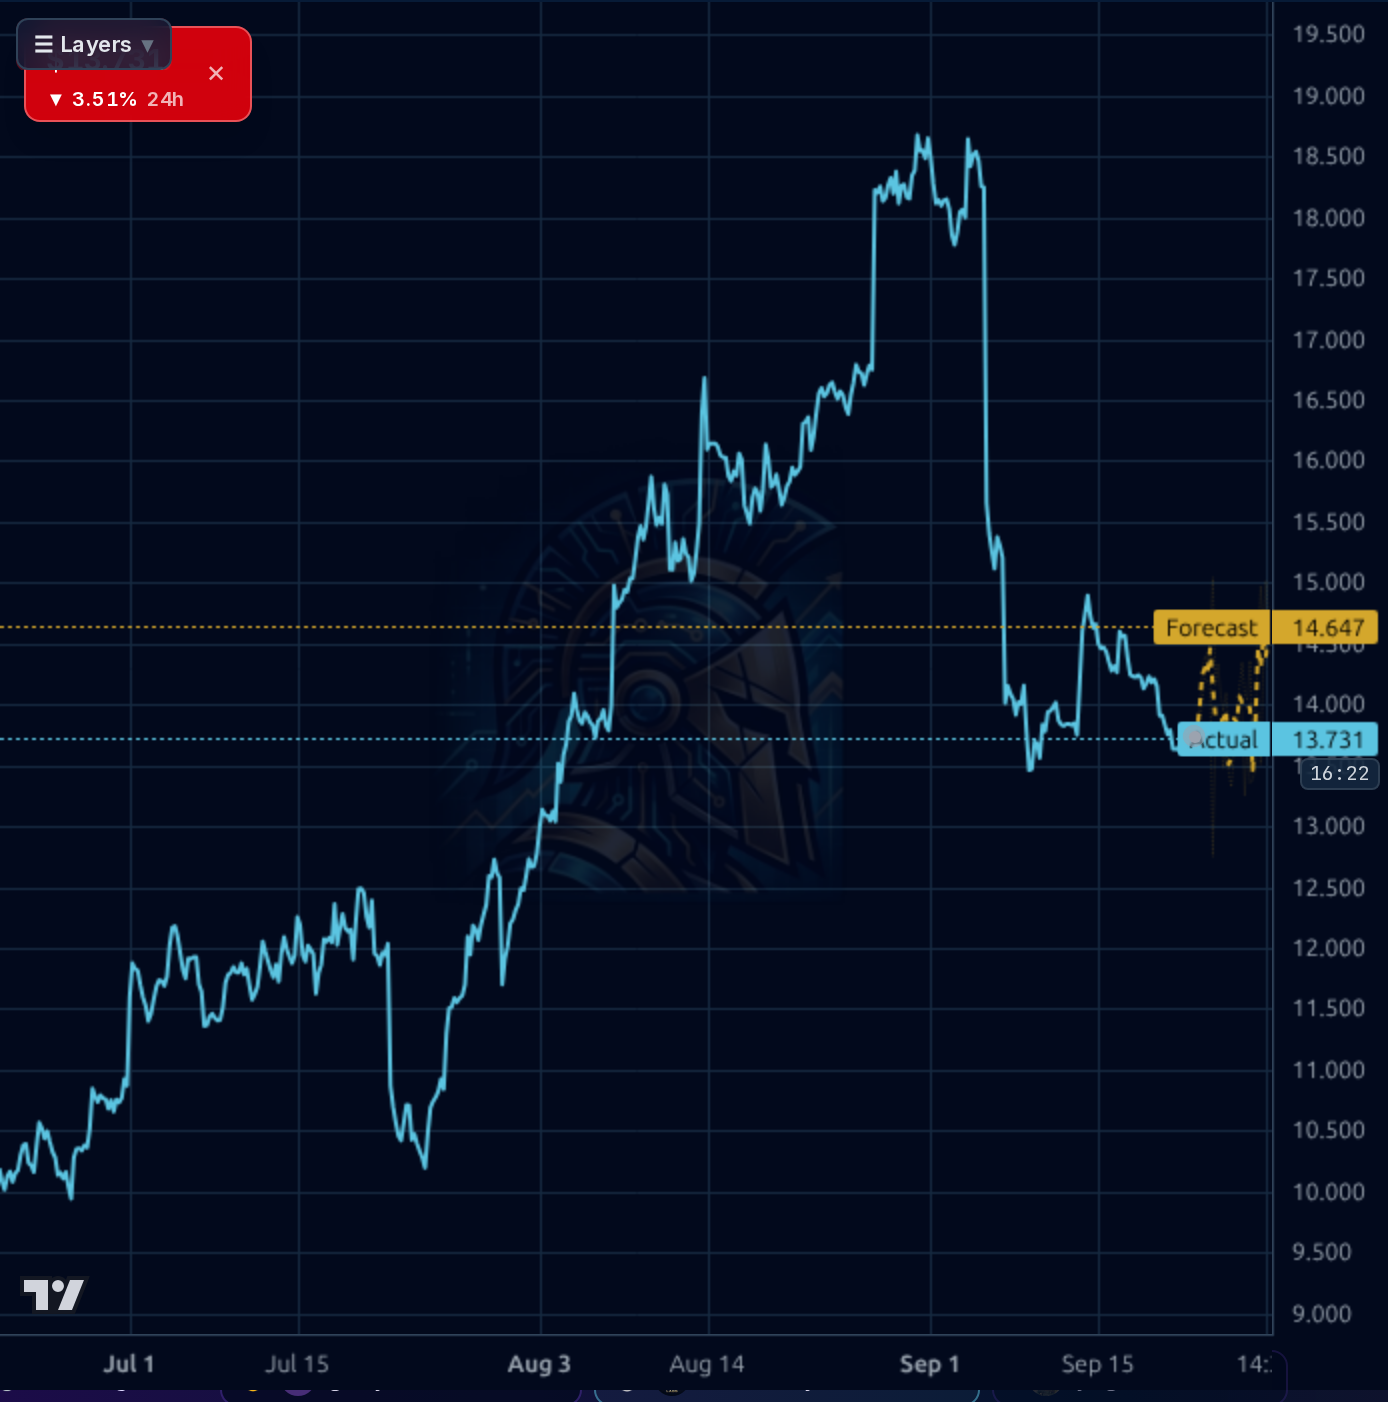
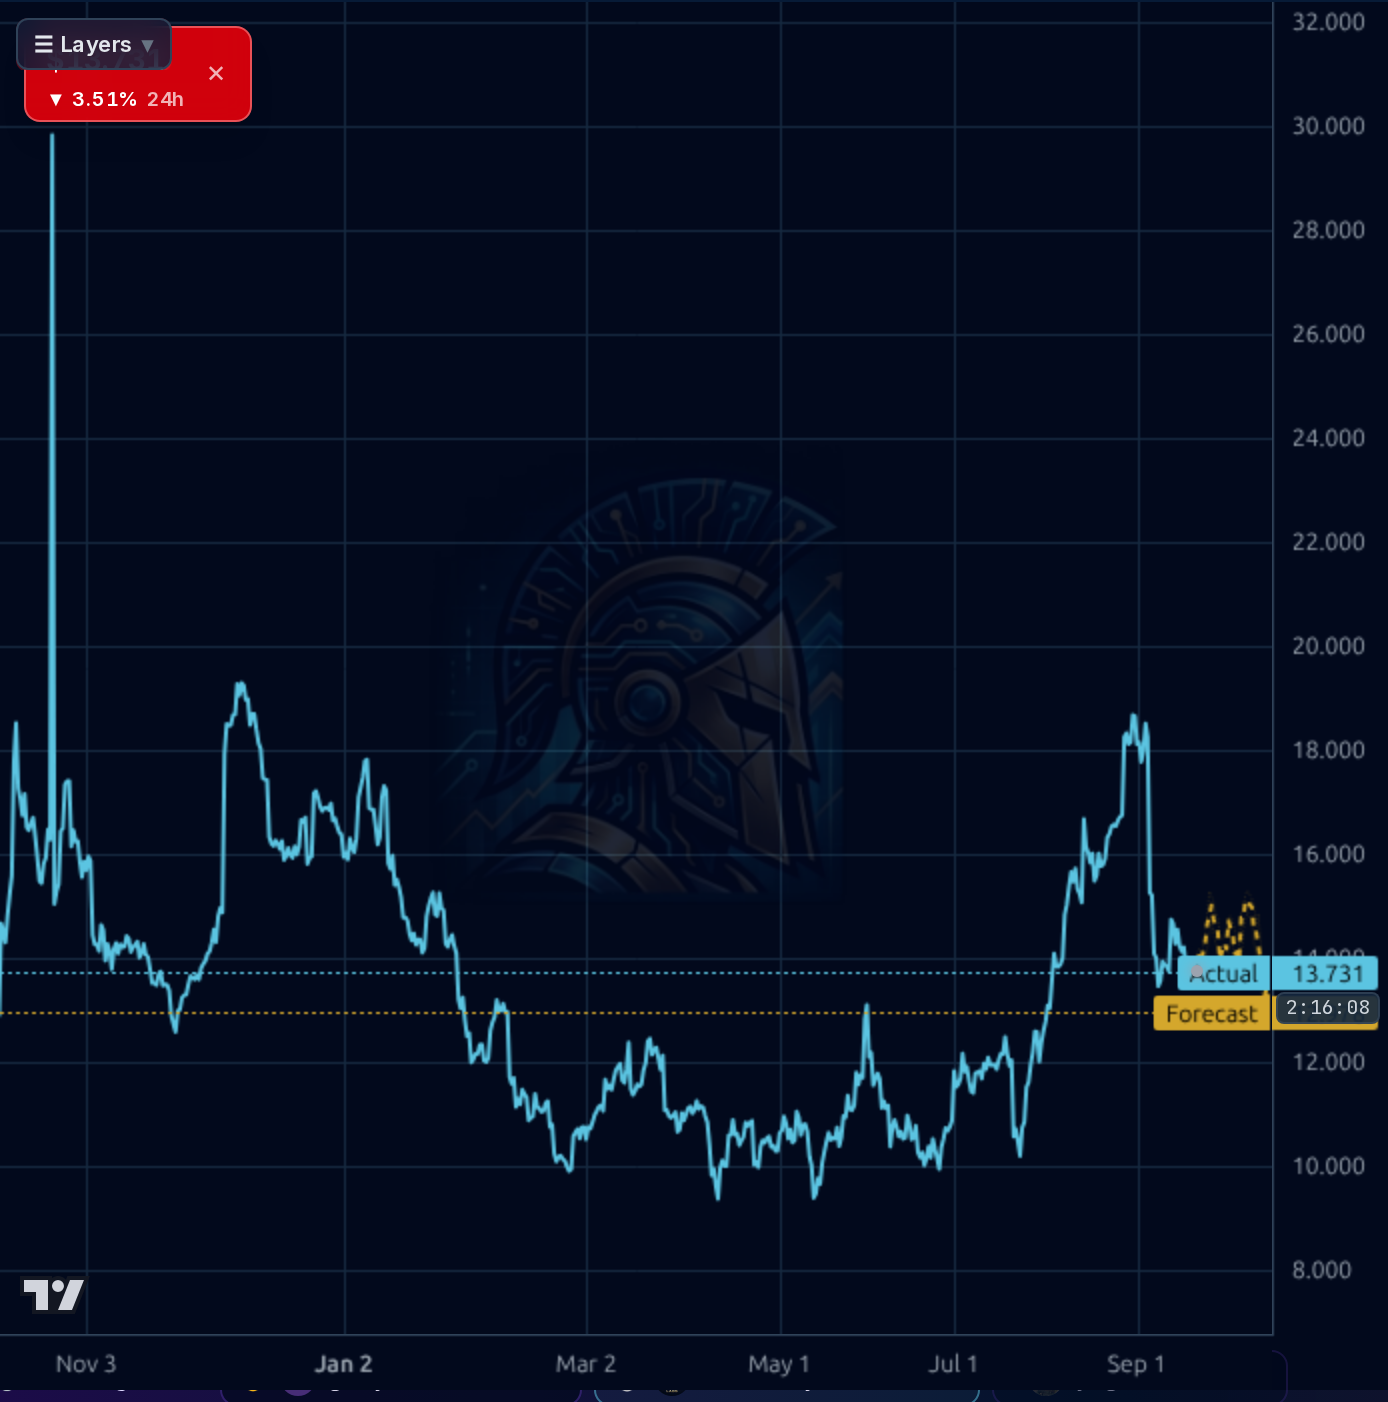
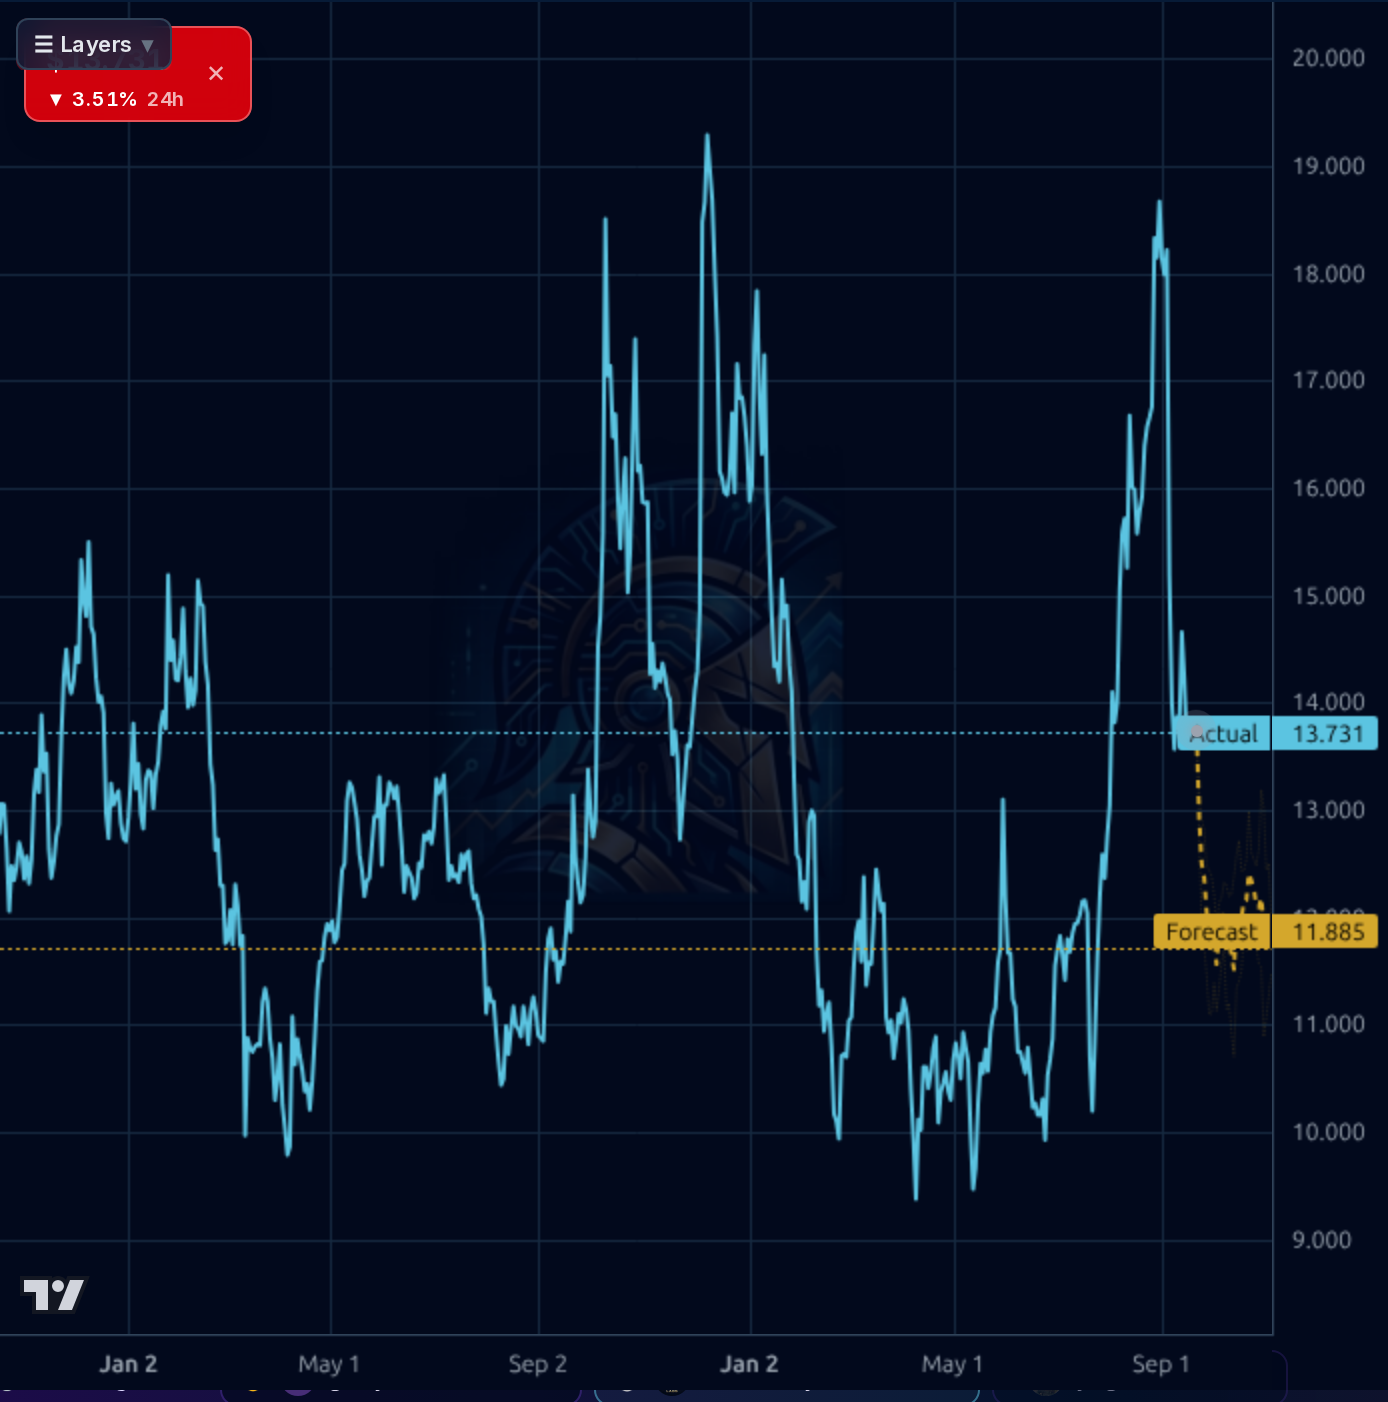
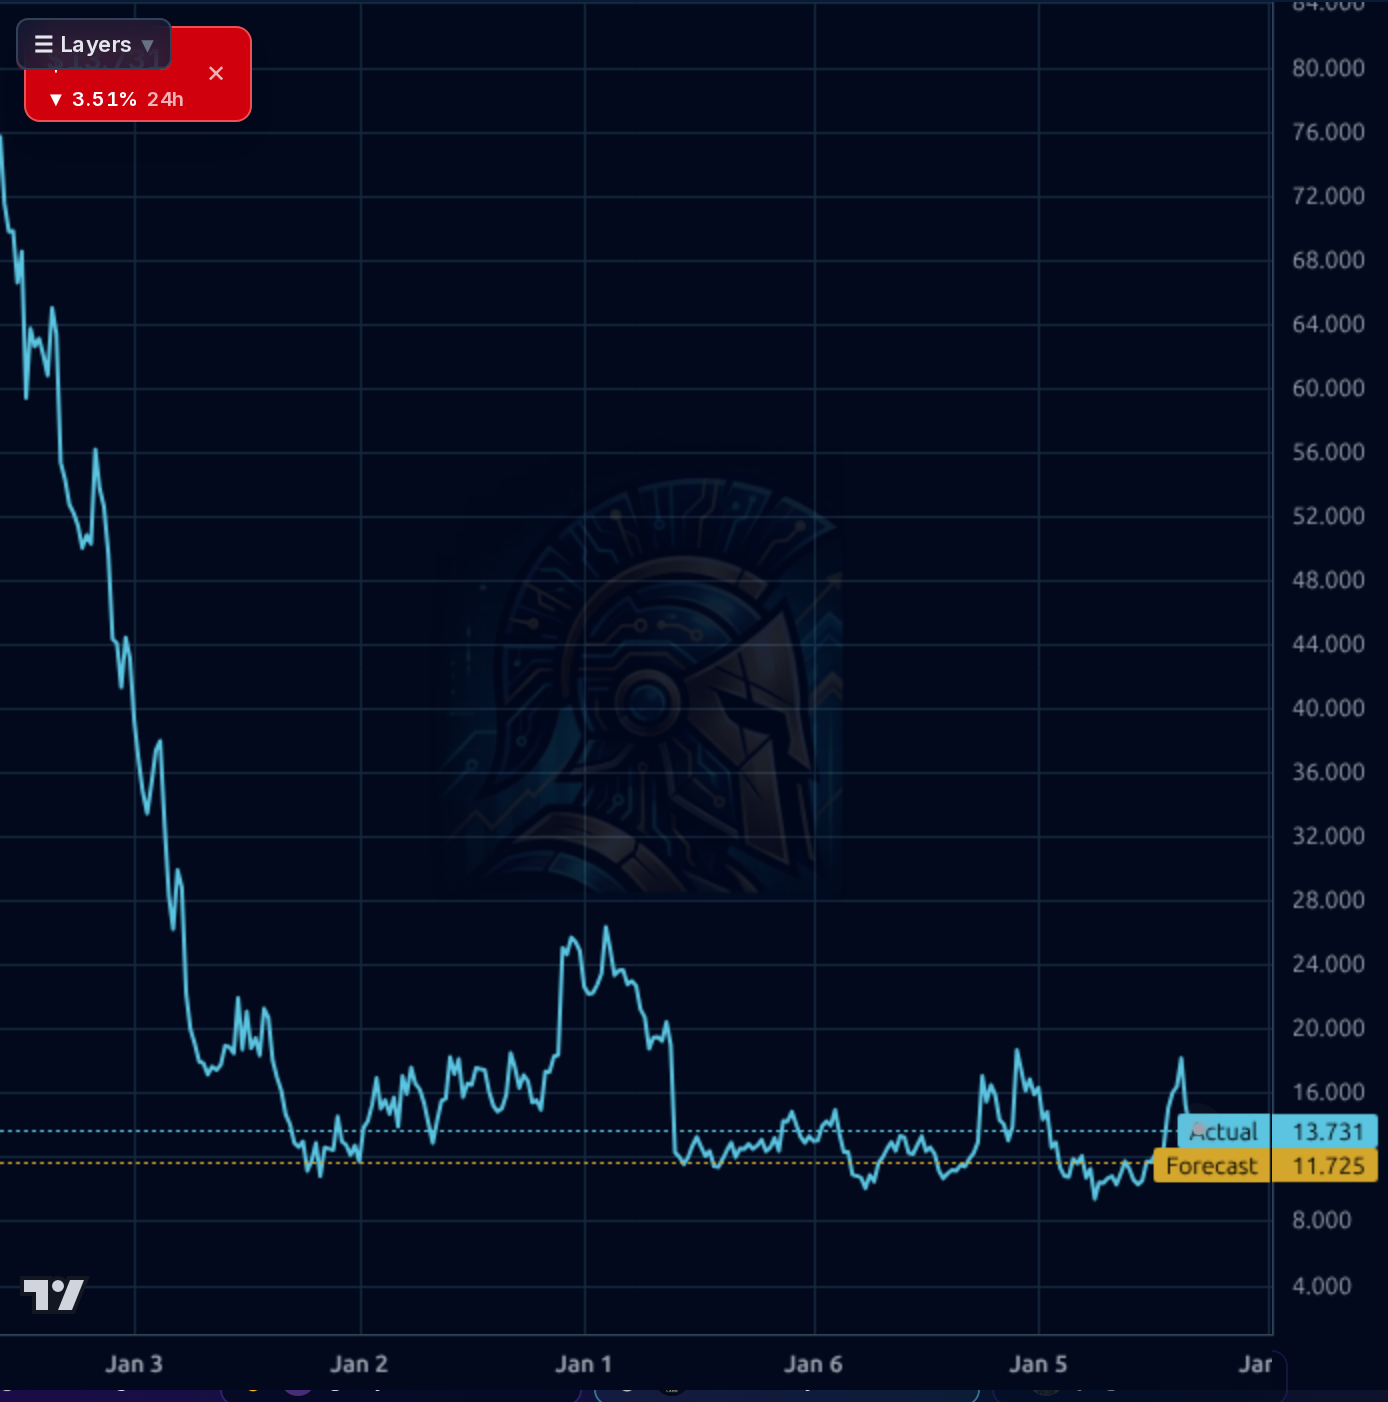
Across timeframes the picture is deteriorating momentum inside a longer-term basing structure. The 1h chart shows a broken uptrend: price rolled from $18.50+ in early September to $13.73, with the model's forecast band clustering just above at $14.65 (mild mean-reversion bias). The 4h view frames it as a full retest of the pre-rally consolidation zone around $13–14, with the forecast now pointing lower into $13. On the 1d chart, price sits mid-range of the multi-year $10–19 band, and the model's forecast at $11.88 explicitly targets a retest of the summer lows. The weekly context is constructive longer-term — a broad base since early 2023 near $10–14 — but the current bar is a sharp rejection off $19. RSI at 40 is not yet oversold; price is -14.9% below the 20SMA, -4.5% below the 50SMA, but still +5.5% above the 200SMA, so the intermediate uptrend is not yet broken. Key levels: $13.00 is immediate support (must hold), then $12.00 and $10.20 (July low); resistance stacks at $14.65 (forecast/gap fill), $16.00 (50SMA reclaim), and $18.50 (pre-earnings high). The 1wk forecast track record is strong (100% directional, 5% MAPE) and it points down — take that seriously.
Signal: (1) Gartner named UiPath a Leader in Intelligent Document Processing for the second consecutive year (Sept 14–15) — a genuine product-competitive endorsement that undercuts the hyperscaler-bundling bear case. (2) A software/SaaS rotation lifted PATH +8% on Sept 14 as capital rotated out of AI-hardware — this is a fragile tailwind tied to an ephemeral macro narrative, not a rerating. (3) The Sept 3 8-K formalized both Q2 FY27 results and a new CFO appointment, which explains part of the post-print selling pressure — new CFOs typically reset guidance conservatively. (4) Positioning shifted mildly bullish: short float compressed from 29.5% to 25.7%, price target ticked up to $15.40, institutional ownership rose 4.5pp to 70% — quiet accumulation into weakness. Noise: the daily analyst-target and 'stocks to watch' pieces add little. The single most important recent insider action remains the CEO's $22.5M sale at $16.07 on Aug 19, which called the top almost perfectly and remains a warning against chasing rips.
- Maestro process orchestration platform ramp with Banco Azteca (8,800+ processes) as anchor reference — needs formal ACV disclosure on Dec 2 to move the multiple
- Agent Builder cross-sell into ~97% Fortune 500 install base (agentic AI TAM expansion)
- Gartner Magic Quadrant Leader designation (2nd consecutive year, Sept 14) for Intelligent Document Processing supports enterprise deal wins
- $500M buyback capacity remains from prior program plus $1.28B cash — formal expansion/re-authorization would be a re-rating catalyst
- New CFO onboarding creates opportunity for a reset guidance framework that lowers the bar for future beats
- Q3 FY27 guide already missed at last print; Dec 2 earnings could deliver another cut under new CFO's conservative framework
- Hyperscaler bundling (Microsoft Copilot Studio, ServiceNow AI Agents, Salesforce Agentforce) compressing the standalone orchestration moat
- CEO's $22.5M sale at $16.07 on Aug 19 called the local top — insider signal against chasing strength
- Operating margin volatility: 7.7% Q2 vs 16.7% Q4 — market may re-rate lower if the lumpy cadence persists
- Risk-off macro backdrop (breadth 42.7% >200dMA and deteriorating, defensive leadership) pressures high-beta small-mid cap software
- ~26% short float cuts both ways: enables squeezes on good news but amplifies gap-downs on any negative print
- 1d forecast model shows bullish_prob 0.00 and points to $11.88 on the 1d horizon (which has 100% realized accuracy) — meaningful downside probability
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord