PCRX — AI Stock Forecast & Price Targets
Published 9/16/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live PCRX price forecast →
PCRX is a reimbursement-driven EXPAREL story with a genuine forward-EPS inflection ($3.43 fwd vs. $0.36 trailing) that keeps forward P/E at 7.2x, but the stock remains trapped between the multi-year $27.66 ceiling and $23.70 support with 19% short interest signaling active skepticism. Q2 op income of $11.9M (vs. -$10.9M in Q4'25) and $56M FCF validate operating leverage; however, the near-term forecast band skews modestly bearish and the risk-off macro backdrop argues against chasing. Accumulate on weakness toward $23.50-24.00, don't pay up into resistance.
Range-trade posture. Don't chase into $25.50-26.00; wait for a pullback to $23.70-24.00 to add. Invalidation on a daily close below $22.30 (breaks the multi-quarter base). Upside cap for a swing trade is $26.50; the $27.66 ceiling has rejected the stock repeatedly and Leerink's $28 target reinforces that overhead. Size modestly — 19% short interest and risk-off macro backdrop mean sudden shakeouts are likely. The near-term forecast leans slightly bearish so avoid initiating a full position at the top of the range.
Thesis is the operating leverage story continuing to print: Q3 (Nov 5) needs to sustain positive op income and validate progress toward the $3.43 forward EPS. Expected return range: -8% to +20% depending on the print. A clean beat plus reaffirmed guidance likely takes the stock into the $27-29 zone and finally tests the ceiling; a miss or soft guide re-tests $22 and unwinds the multiple compression trade. What changes my mind: (1) op income slipping back toward flat/negative, (2) EXPAREL revenue growth decelerating below mid-single digits, (3) PCRX-201 Phase 2 setback. Cash build toward $250M+ and any debt paydown announcement would be incrementally positive.
Terminal thesis: PCRX becomes a mid-teens operating margin specialty pharma with EXPAREL as the reimbursement-expanded cash-cow anchor and PCRX-201 gene therapy as call option. If forward EPS of ~$3.40 is genuinely achievable and stable, even a 10-12x multiple prints $34-41 — but that requires multi-quarter proof, not a single beat. Multi-year drivers: EXPAREL payer expansion beyond UnitedHealthcare, PCRX-201 Phase 2 readout and pathway to Phase 3, disciplined use of the $250M+ cash build. Biggest structural risk: EXPAREL is 80%+ of revenue and is a mature product — any pricing/rebate pressure, generic/biosimilar competition, or reimbursement rollback collapses the entire thesis. Secondary risk: PCRX-201 is unproven and gene therapy Phase 2 setbacks are common.
Revenue has stabilized in a $177-197M quarterly band with Q2'26 at $192.4M (+6.2% Y/Y per news and snapshot), and gross margin remains best-in-class at 77-79%. The real story is operating leverage: operating income went from -$10.9M (Q4'25) to +$4.6M (Q1'26) to +$11.9M (Q2'26), and TTM EPS has swung to +$0.36 with Q2 EPS up 209% Y/Y. Cash flow quality is excellent — Q2 OCF $57.5M / FCF $56.1M, TTM FCF $98M against a $993M market cap yields a very cheap P/FCF of 5.5x. Balance sheet is workable: $206M cash, $412M debt (D/E 0.61), current ratio 5.0, EBITDA TTM ~$124M gives ~3.3x leverage — manageable but not trivial given only $14.6M net income. Capital allocation has been disciplined: iovera divested to Zimmer to refocus on the drug franchise, capex minimal ($1.3M Q2), cash building from $148M to $206M over three quarters — sets up debt paydown or tuck-in M&A. The core break is that net margin is still only ~2% and ROE 2%, so the entire investment case rests on the forward EPS ramp actually printing.
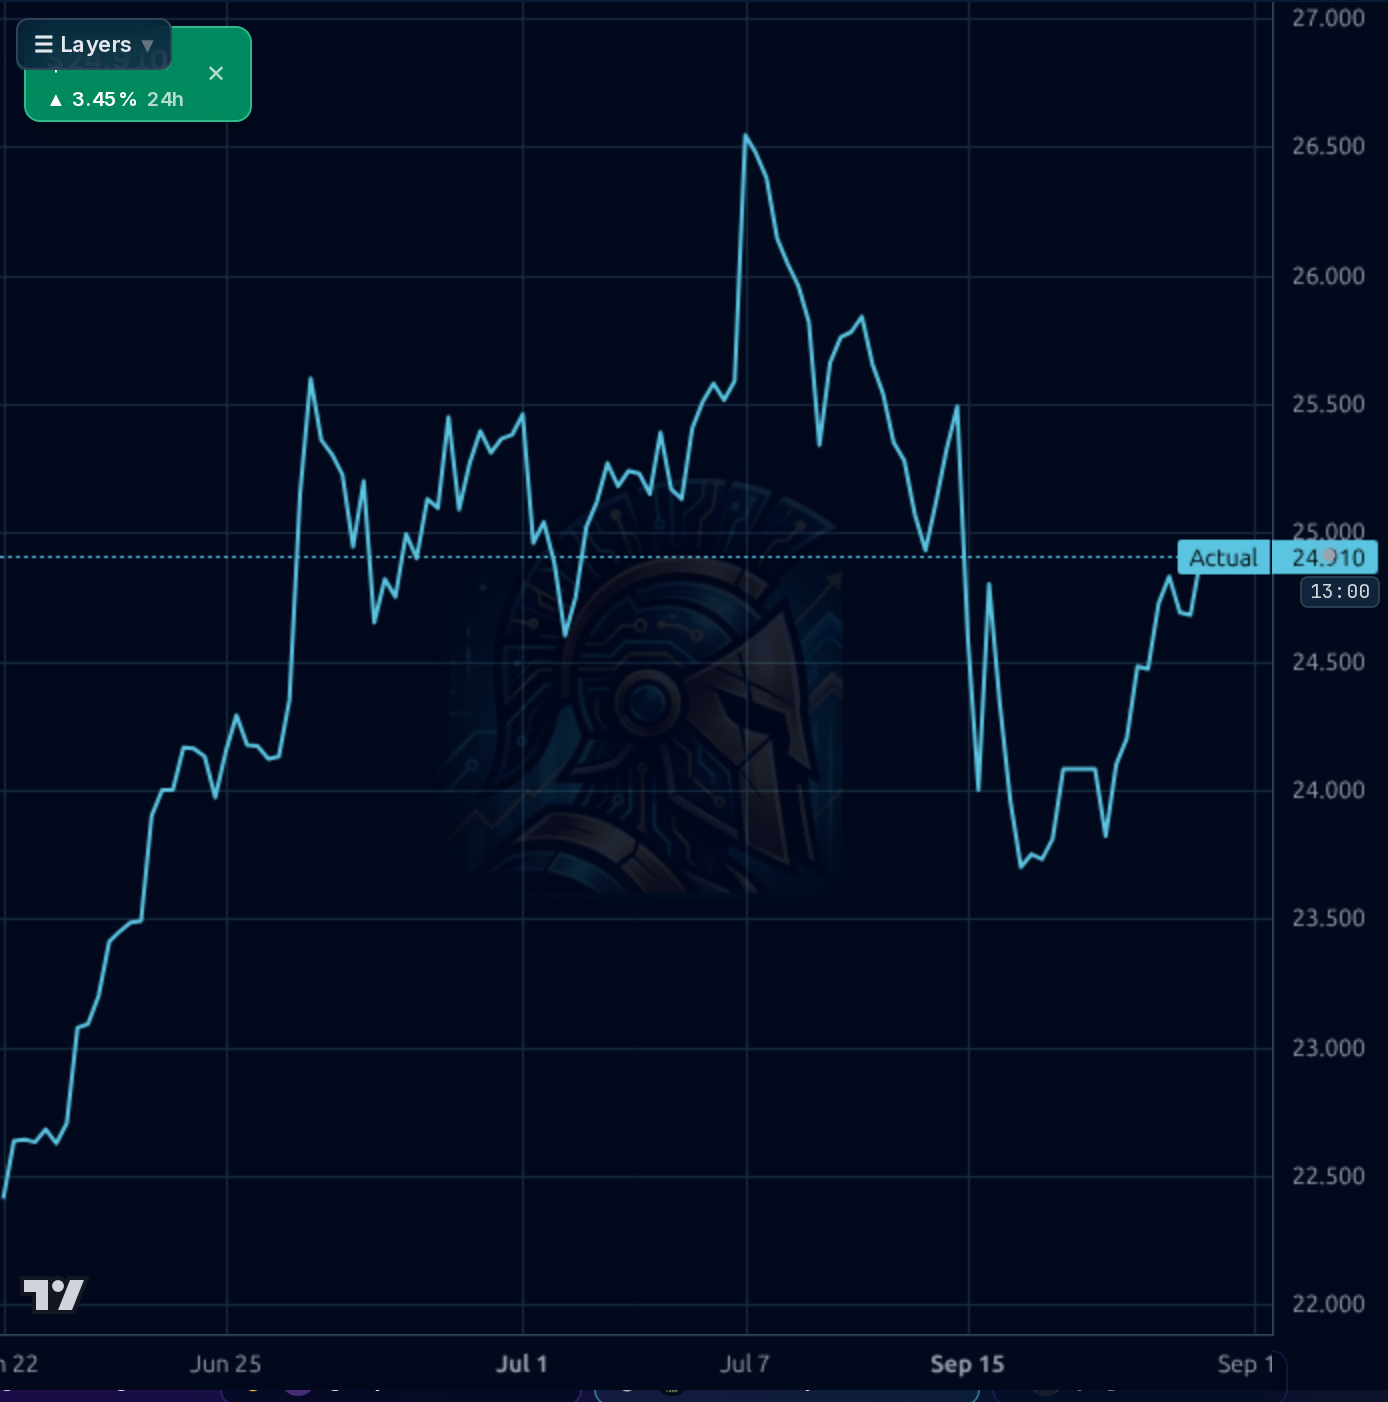
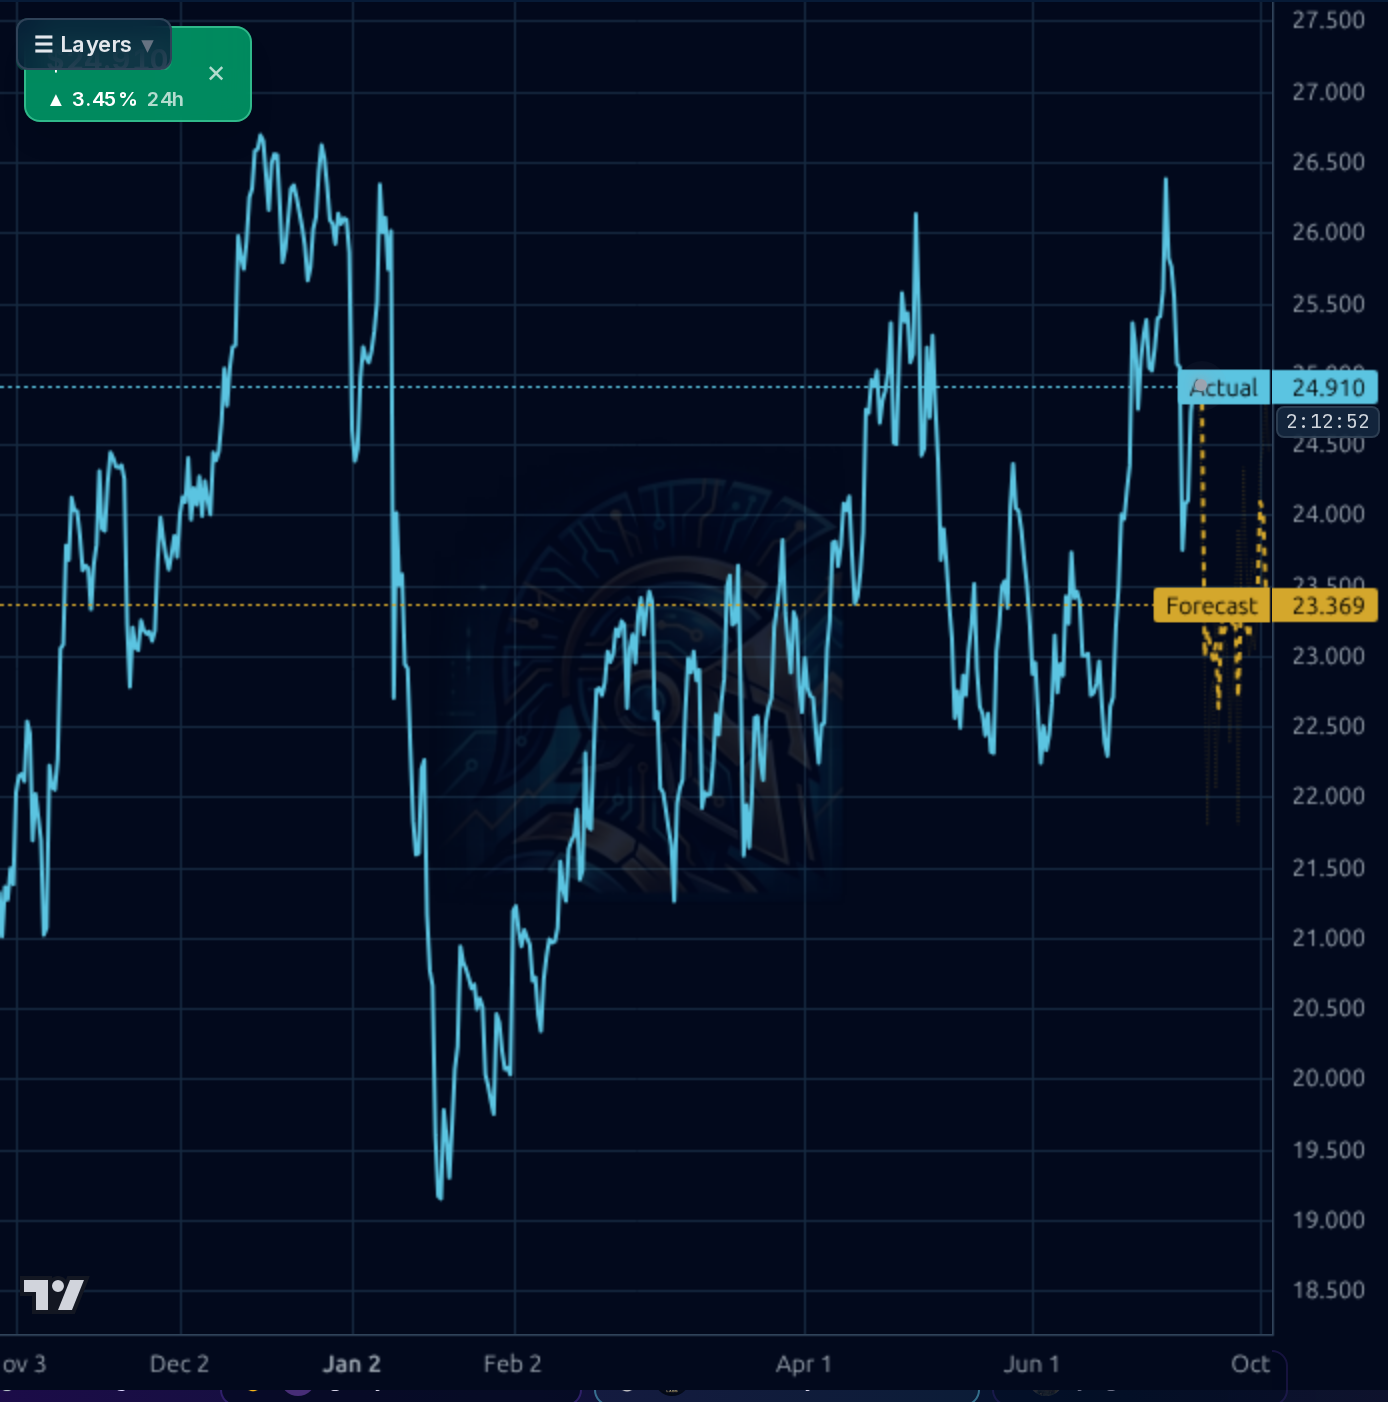
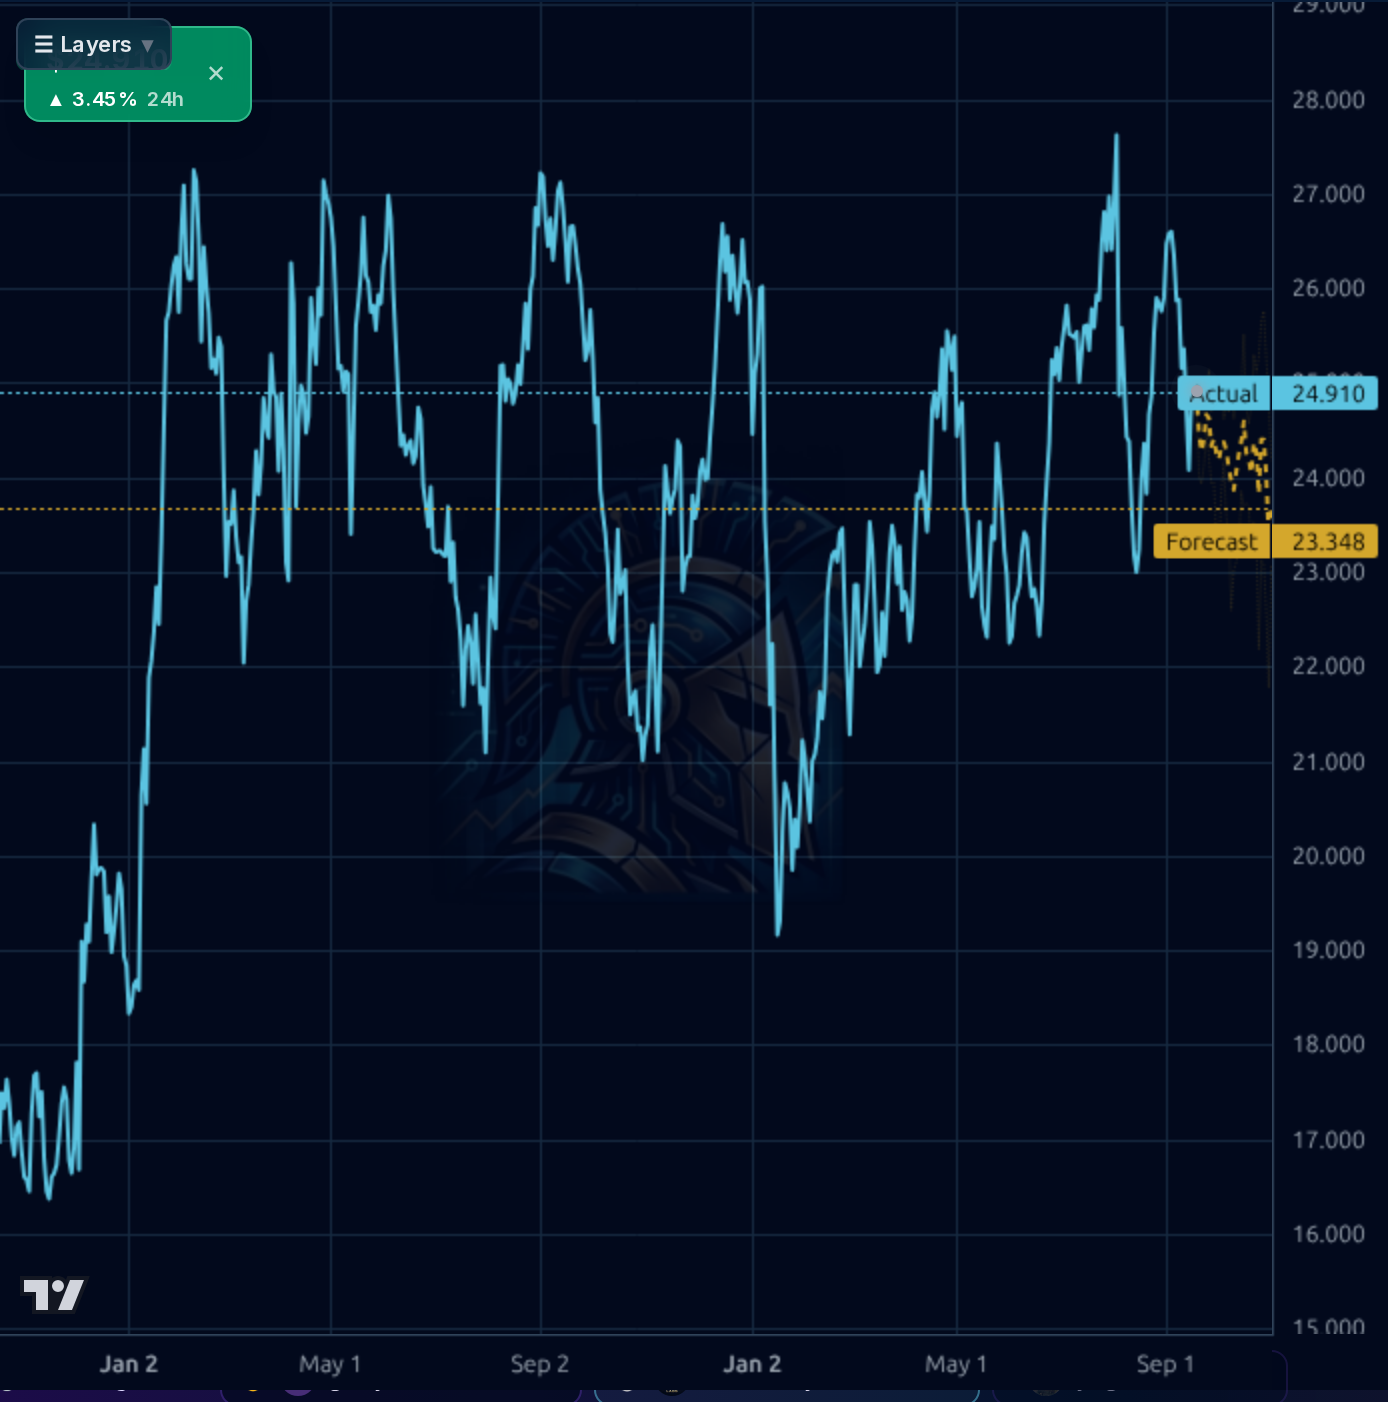
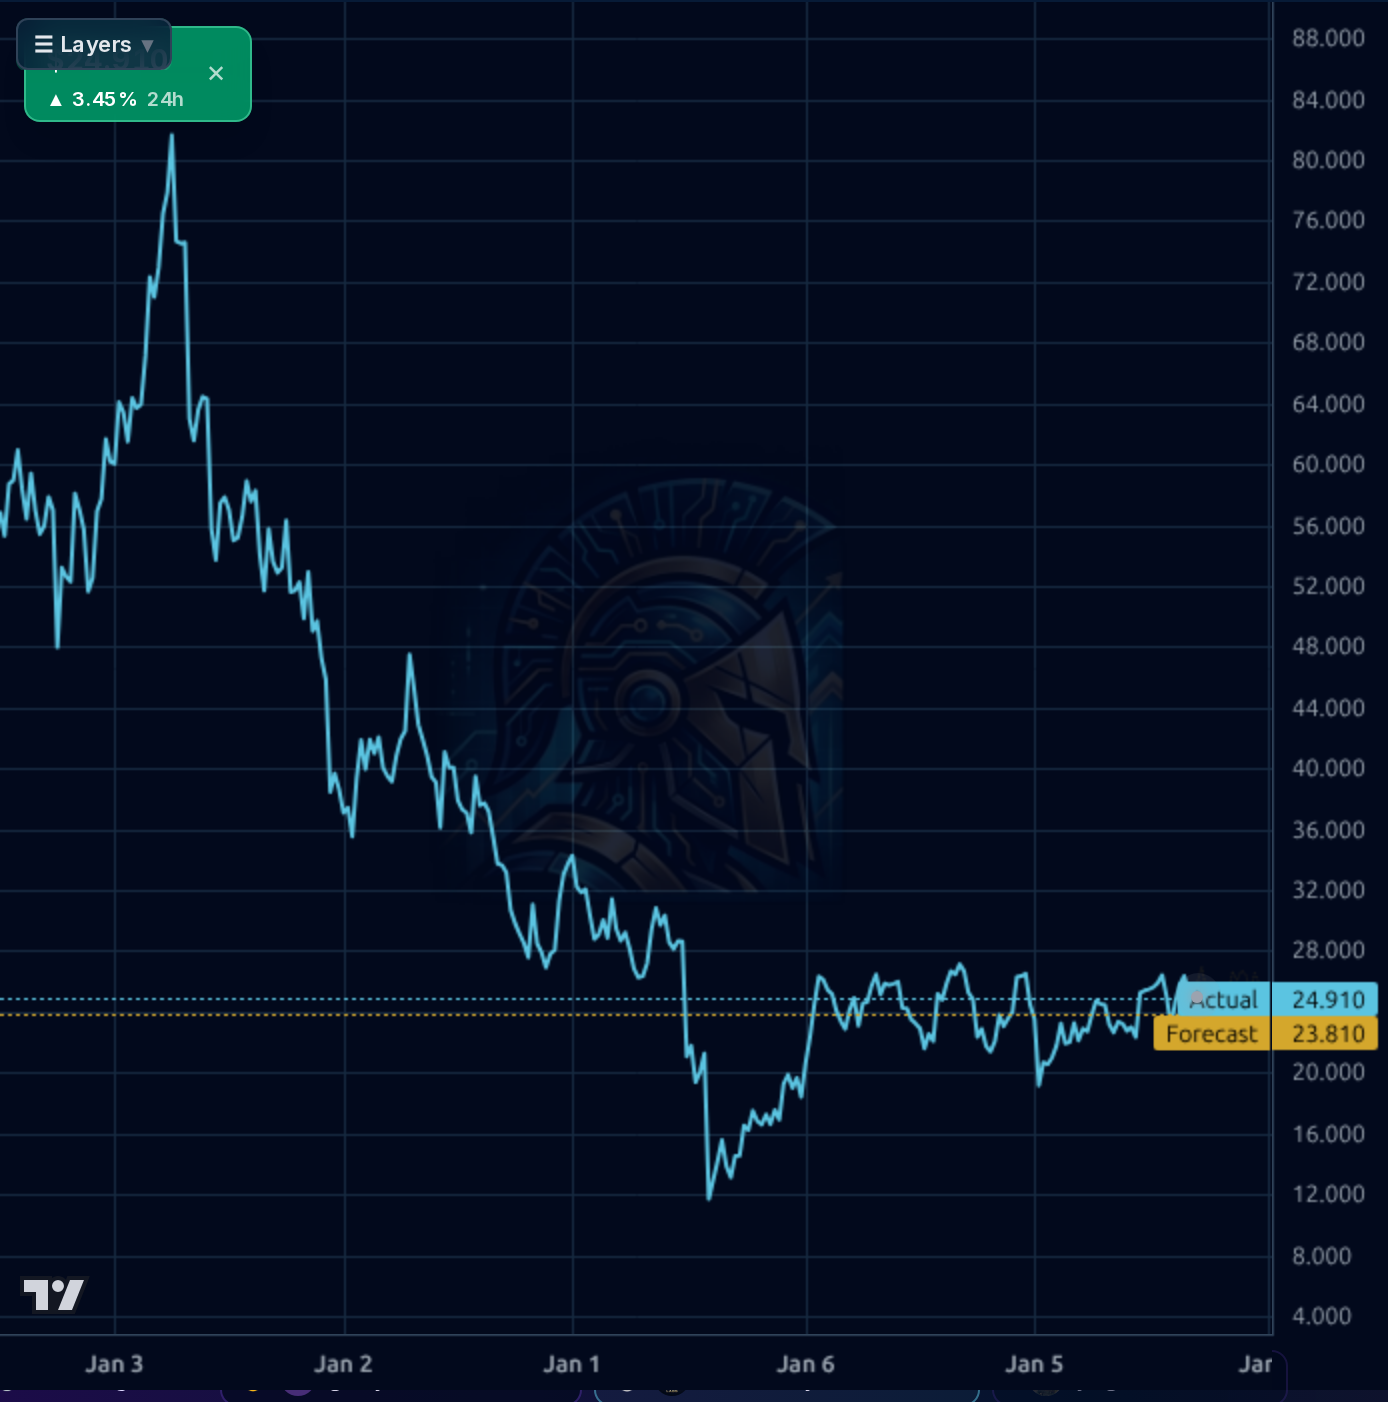
The 1h/4h chart shows a rejection from the $26.60 area in early July followed by a swift drop to $23.70, then a base and reclaim back to $24.91 — constructive short-term recovery but still well below the July high. On the daily, price is oscillating in a $22.30-$27.66 range that has capped the stock since Jan 2025; SMA20/50 are close (-2.0%/-1.9%) with SMA200 +4.3%, RSI 46.7 — neutral, no momentum edge either way. Weekly view shows the multi-year downtrend from ~$80 has flattened into a $19-28 range with a slight upward tilt. The model's forecast band sits at $23.35-23.37 with a low projection near $23 — modestly bearish, but the 1wk model has been beaten by naive baseline (67% vs 83%), so I discount that signal materially. Key levels: support $23.70 (recent low) then $22.30; resistance $25.50 (recent congestion), then the critical $27.63-$27.66 multi-year ceiling. No divergence worth flagging; this is a range name until proven otherwise.
The signal-rich items: Leerink initiating with Market Perform and a $28 price target on Sep 9 essentially caps near-term sell-side enthusiasm right at the multi-year resistance — that's a mild headwind for a breakout narrative. ChartMill's Sep 11 note flags PCRX as an undervalued value stock backed by cash flow and balance sheet strength, which aligns with the P/FCF 5.5x and forward P/E 7.2x setup. The Q2'26 recap confirms +6.2% revenue growth and 2026 guidance was updated (details not disclosed here but management is standing behind the numbers). Inducement grants to five new hires suggest continued hiring/scaling. The Sarepta comparisons and inducement-grant items are noise. Net-net: news flow is mildly constructive on the value case but doesn't provide a catalyst to break the range — the next real event is the Nov 5 earnings print.
- EXPAREL reimbursement expansion — UnitedHealthcare outpatient coverage is driving ~6% Y/Y revenue growth in Q2'26; incremental payer wins compound
- Operating leverage inflection: op income moved from -$10.9M (Q4'25) → +$4.6M (Q1'26) → +$11.9M (Q2'26), with Q2 EPS +209% Y/Y
- PCRX-201 Phase 2 gene therapy for knee OA — commercial-ready manufacturing already scaled, providing significant optionality if data is clean
- Cash generation runway: TTM FCF $98M (P/FCF 5.5x) and cash growing from $148M to $206M over three quarters enables debt paydown or tuck-in M&A
- iovera divestiture to Zimmer Biomet refocuses capital on higher-margin drug franchise and removes device drag
- NOCITA veterinary partnership with Aratana adds small but incremental royalty stream
- Trailing 69x P/E vs. forward 7.2x P/E — any Q3 (Nov 5) or Q4 EPS miss unwinds the entire multiple compression trade
- Multi-year $27.63-$27.66 ceiling has rejected the stock since Jan 2025; Leerink's $28 PT caps near-term sell-side enthusiasm at that same level
- $412M debt against just $14.6M TTM net income — leverage is 3.3x EBITDA and manageable only if the EPS ramp is real
- 19% short interest with 12.6-day cover suggests sophisticated shorts anticipate a specific catalyst or believe the ramp doesn't stick
- EXPAREL is the vast majority of revenue — any reimbursement rollback, pricing pressure, or competitive entry breaks the thesis
- PCRX-201 Phase 2 safety or efficacy setback destroys gene therapy optionality — gene therapy Phase 2 failure rates are historically high
- Risk-off macro backdrop (SPY distribution, breadth deteriorating, defensive leadership) argues against paying up for a small-cap specialty pharma at range highs
- Net margin ~2% and ROE ~2% — profitability is still subscale and the operating leverage story needs multiple quarters of confirmation
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord