RDDT — AI Stock Forecast & Price Targets
Published 9/11/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live RDDT price forecast →
Reddit continues to combine pristine unit economics (91% gross, 31% net margin, $1.49B cash, near-zero debt) with 61% YoY revenue growth, but the tape is dominated by structural overhang from Google AI Overviews and a heavy insider selling cluster in mid-August. At $155 the stock sits mid-range between the $135-140 support and $175-185 supply zone, offering a reasonable accumulation setup but not a chase — position for a grind toward the mid-$170s into the Oct 29 print, with tight risk below $140.
1-4 week view: Accumulate on weakness, don't chase. Preferred entry $148-152; add on a decisive close above $160 (base confirmation per the dossier). Near-term upside target $172-178 into positioning ahead of Oct 29 earnings. Invalidation: daily close below $142 breaks the higher-low structure and re-opens $135. Size at half-normal given 14.3% short float, elevated ATR of $8.99 (5.8% daily), and the insider selling cluster. Hedge or trim into $178+ resistance rather than holding through the print naked.
1-6 month view: Base case is the app-first pivot and AI licensing renewals (2027 cycle per [DOC-4]) start being priced back in as Google referral fears prove less severe than headlines suggest. The Piper audience data showing 8% MoM user growth is exactly the kind of leading indicator that could reset the narrative. Expected range $140-195 over 6 months with base $175. Catalysts: Oct 29 Q3 print (guide already flagged as strong per [DOC-1]), any explicit AI-licensing revenue disclosure as a separate line item, and buyback execution against the $1B authorization. Change my mind: sequential U.S. DAU decline, Google Overviews impact quantified as >5% of ad revenue, or another insider selling cluster of similar magnitude.
1-3 year view: Reddit is a scarce, high-margin content asset with a defensible position as an LLM training corpus and a durable ad platform with international ARPU runway ([DOC-6]). If they successfully de-risk the search-referral dependency and scale AI licensing from ~$60M to $200M+ by 2027-28, the stock re-rates back toward $250+ on a 25-30x fwd P/E on ~$12-15 EPS. Biggest structural risk is genuine — Google AI Overviews is not a passing headline, it is a permanent shift in how information queries route, and Reddit's terminal DAU trajectory depends on the app becoming a direct destination rather than a search endpoint. If that pivot fails, terminal margins compress and the stock stays range-bound in the $120-180 zone indefinitely.
Reddit's Q2 2026 print was operationally excellent: revenue $805M (+61% YoY), gross margin 91.3%, operating margin 28.8%, net income $253M (net margin 31.4%), and free cash flow $261M — with EPS of $1.25 vs $0.97 consensus (a 29% beat). The quarterly trajectory is clean: revenue accelerated from $585M (Q3'25) → $726M → $663M → $805M, and TTM sales growth is 66.6%. The balance sheet is a fortress: $1.49B cash vs only $21M debt, current ratio 10.5, stockholders' equity $3.29B; this gives management optionality for buybacks (the $1B authorization referenced in [DOC-4]) without dilution risk. ROE of 30.7% and ROIC of 26.4% are top-tier for the sector. What's broken is not the P&L — it's the narrative: management's Q2 commentary on 'choppy' Google referral traffic reignited fears about the top of the funnel, and forward P/E of 22 with PEG 0.43 already discounts real deceleration. Fwd EPS of $9.69 implies the market is paying ~16x forward earnings for a business growing revenue 60%+ — cheap on paper, but only if the app-first pivot and AI licensing scale as advertised.
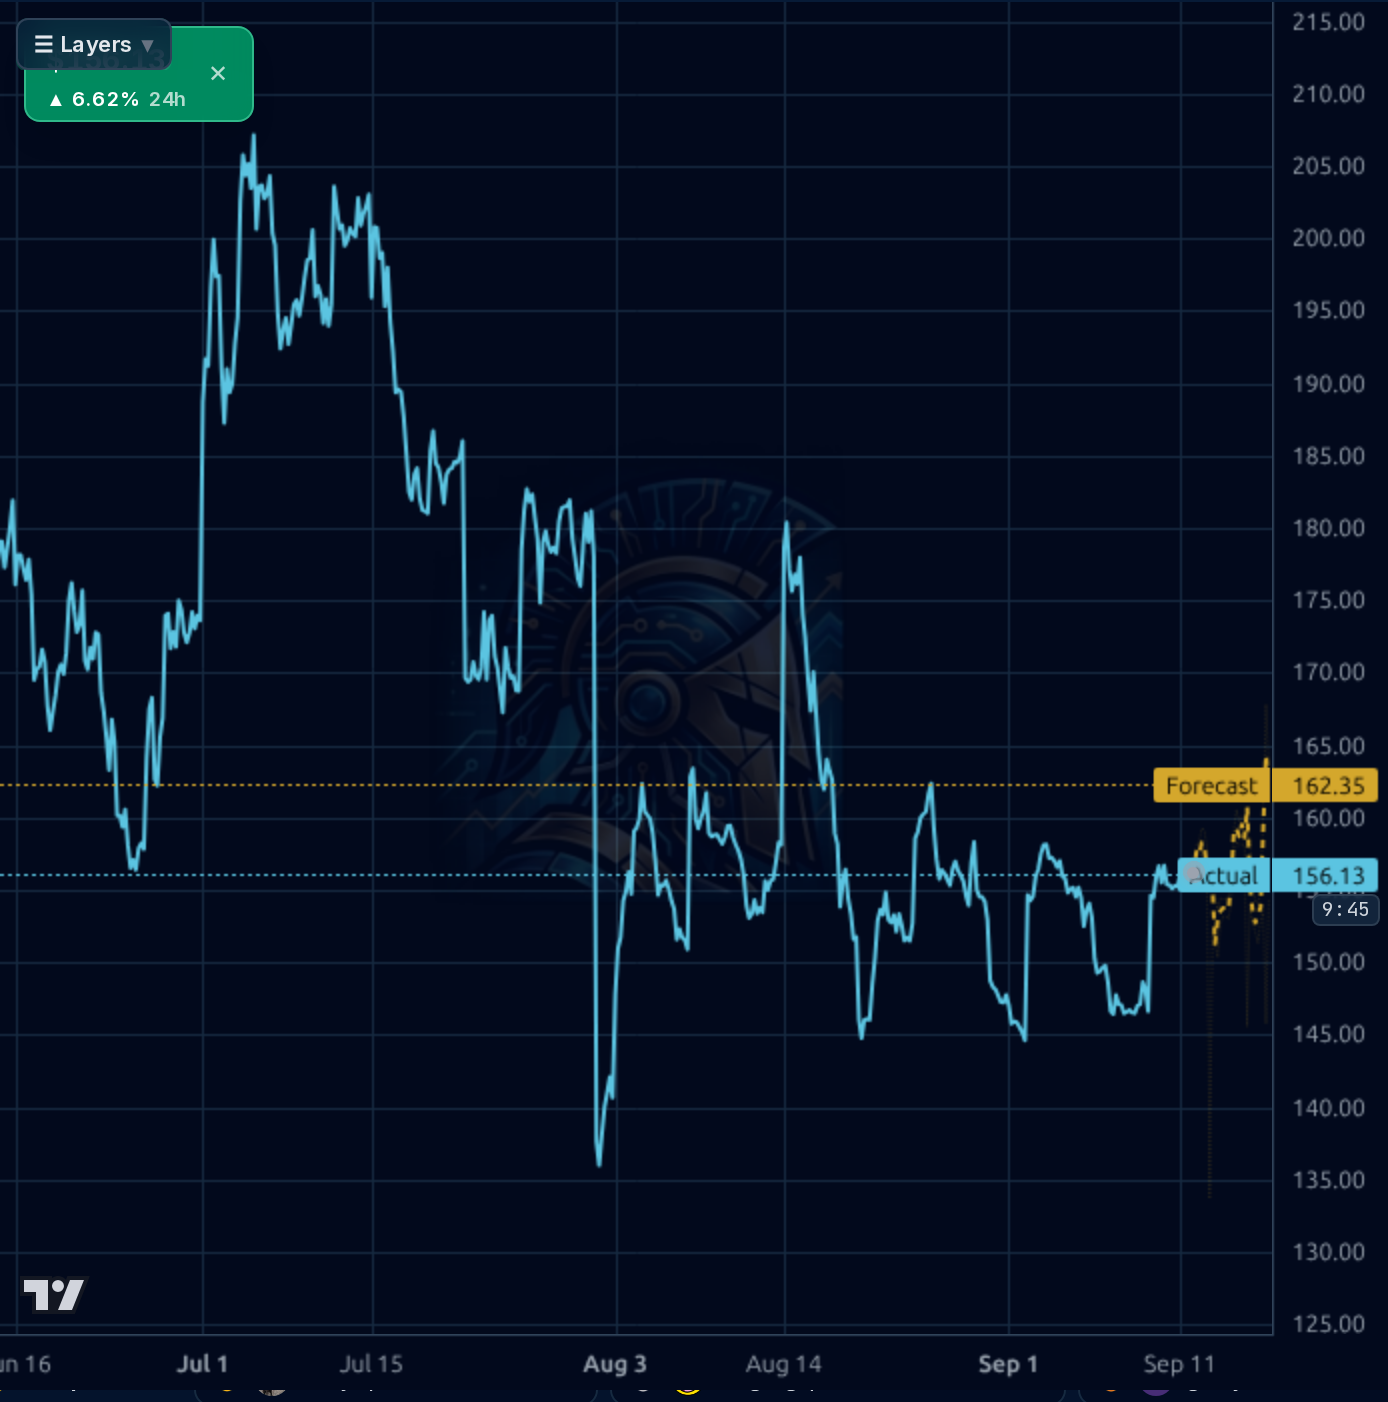
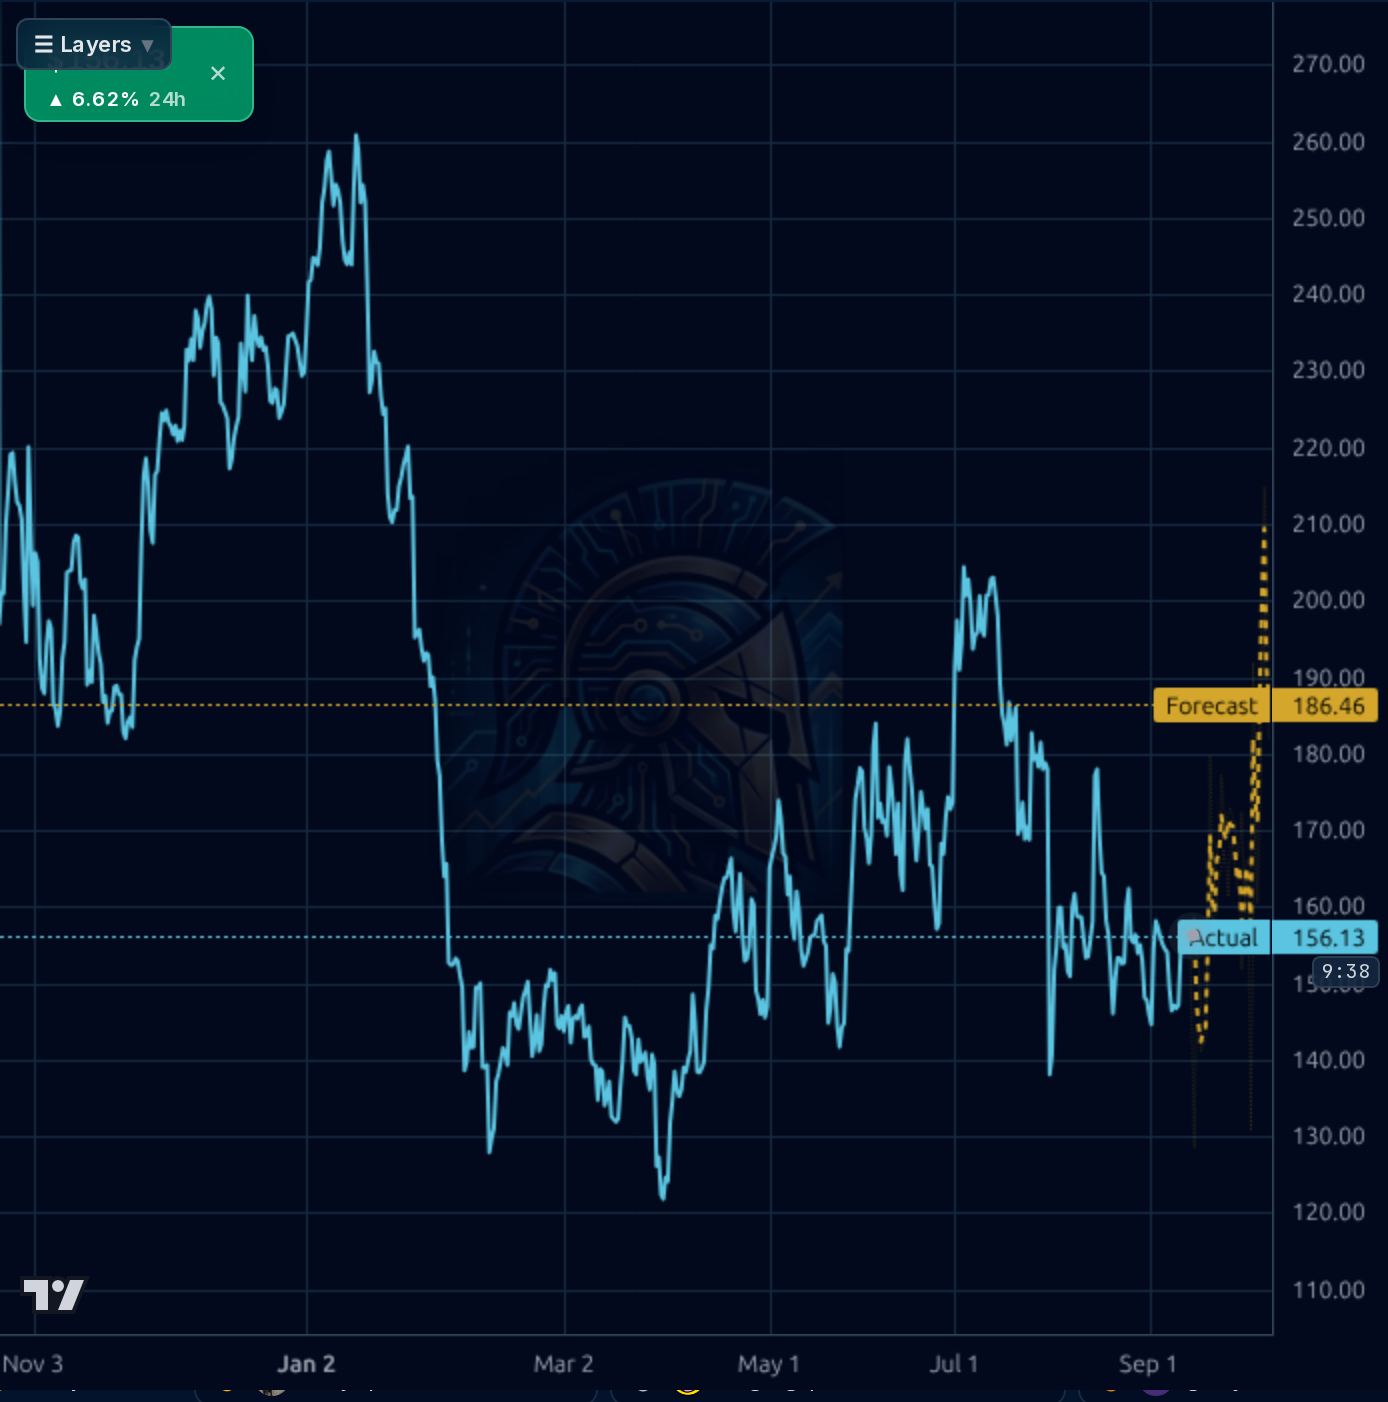
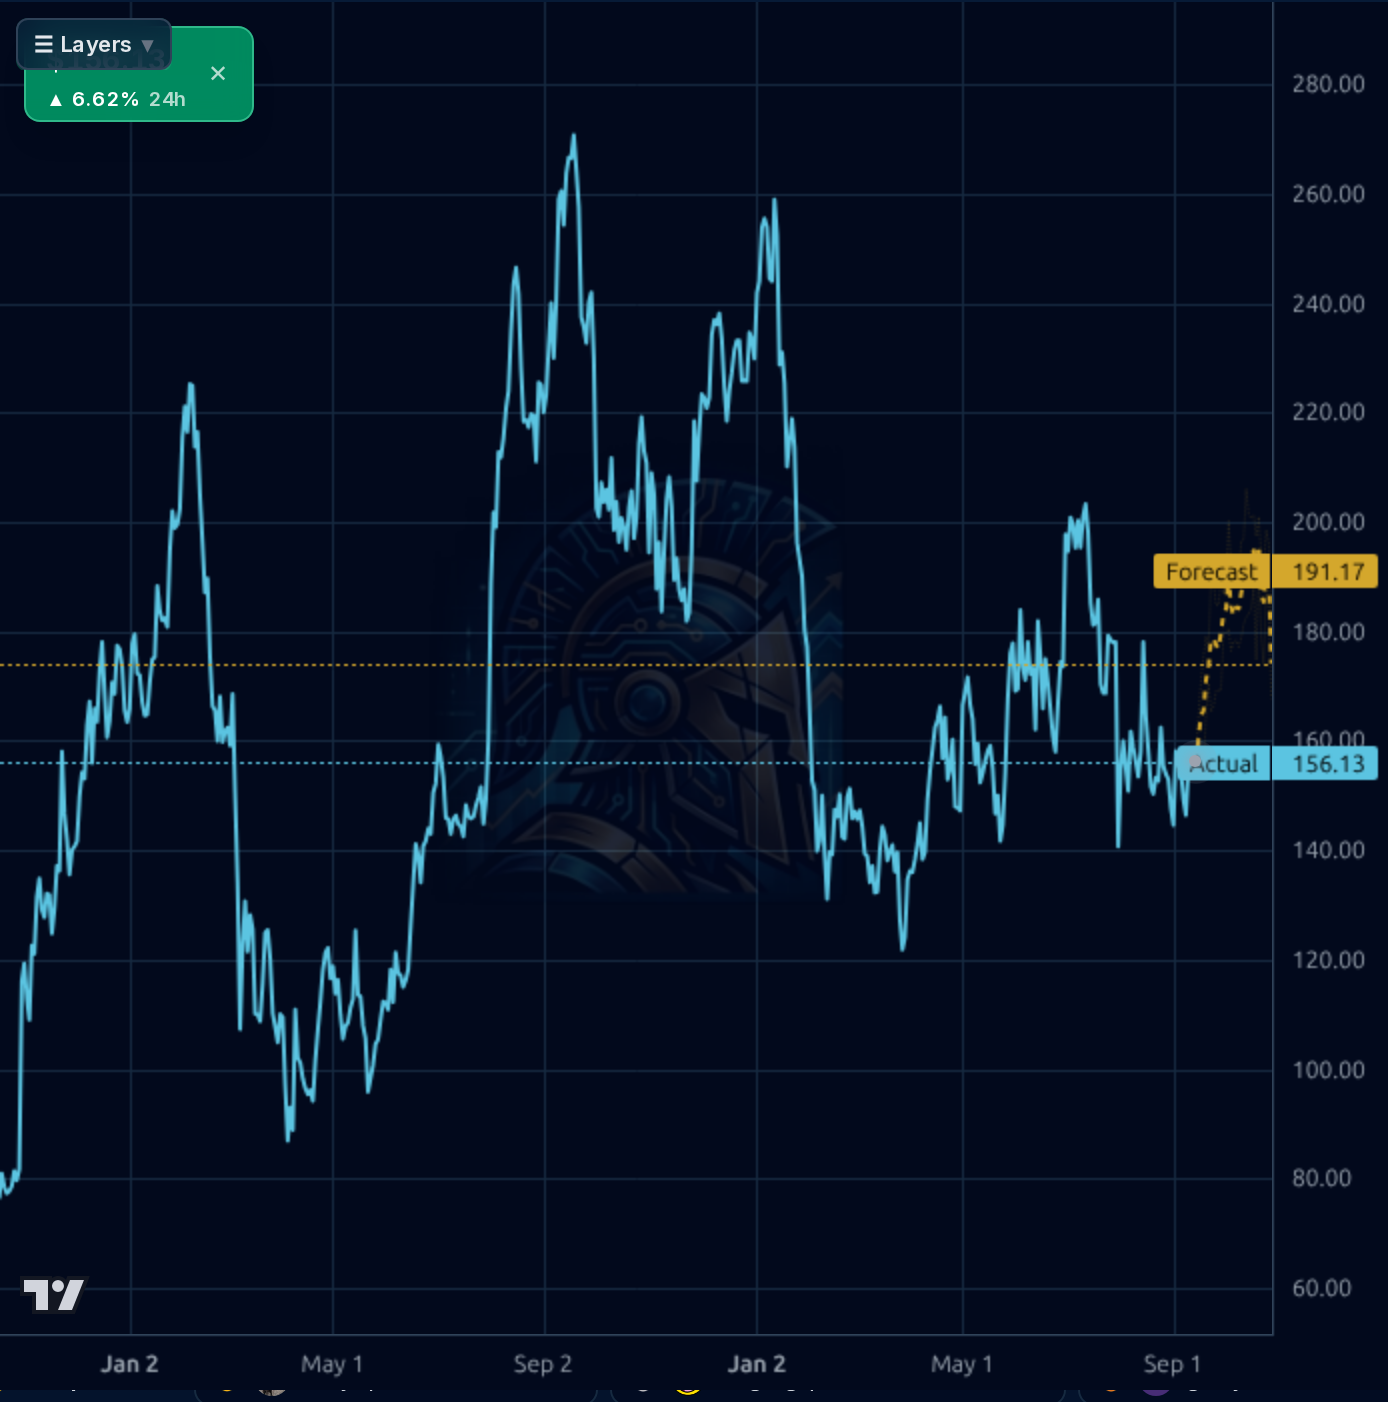
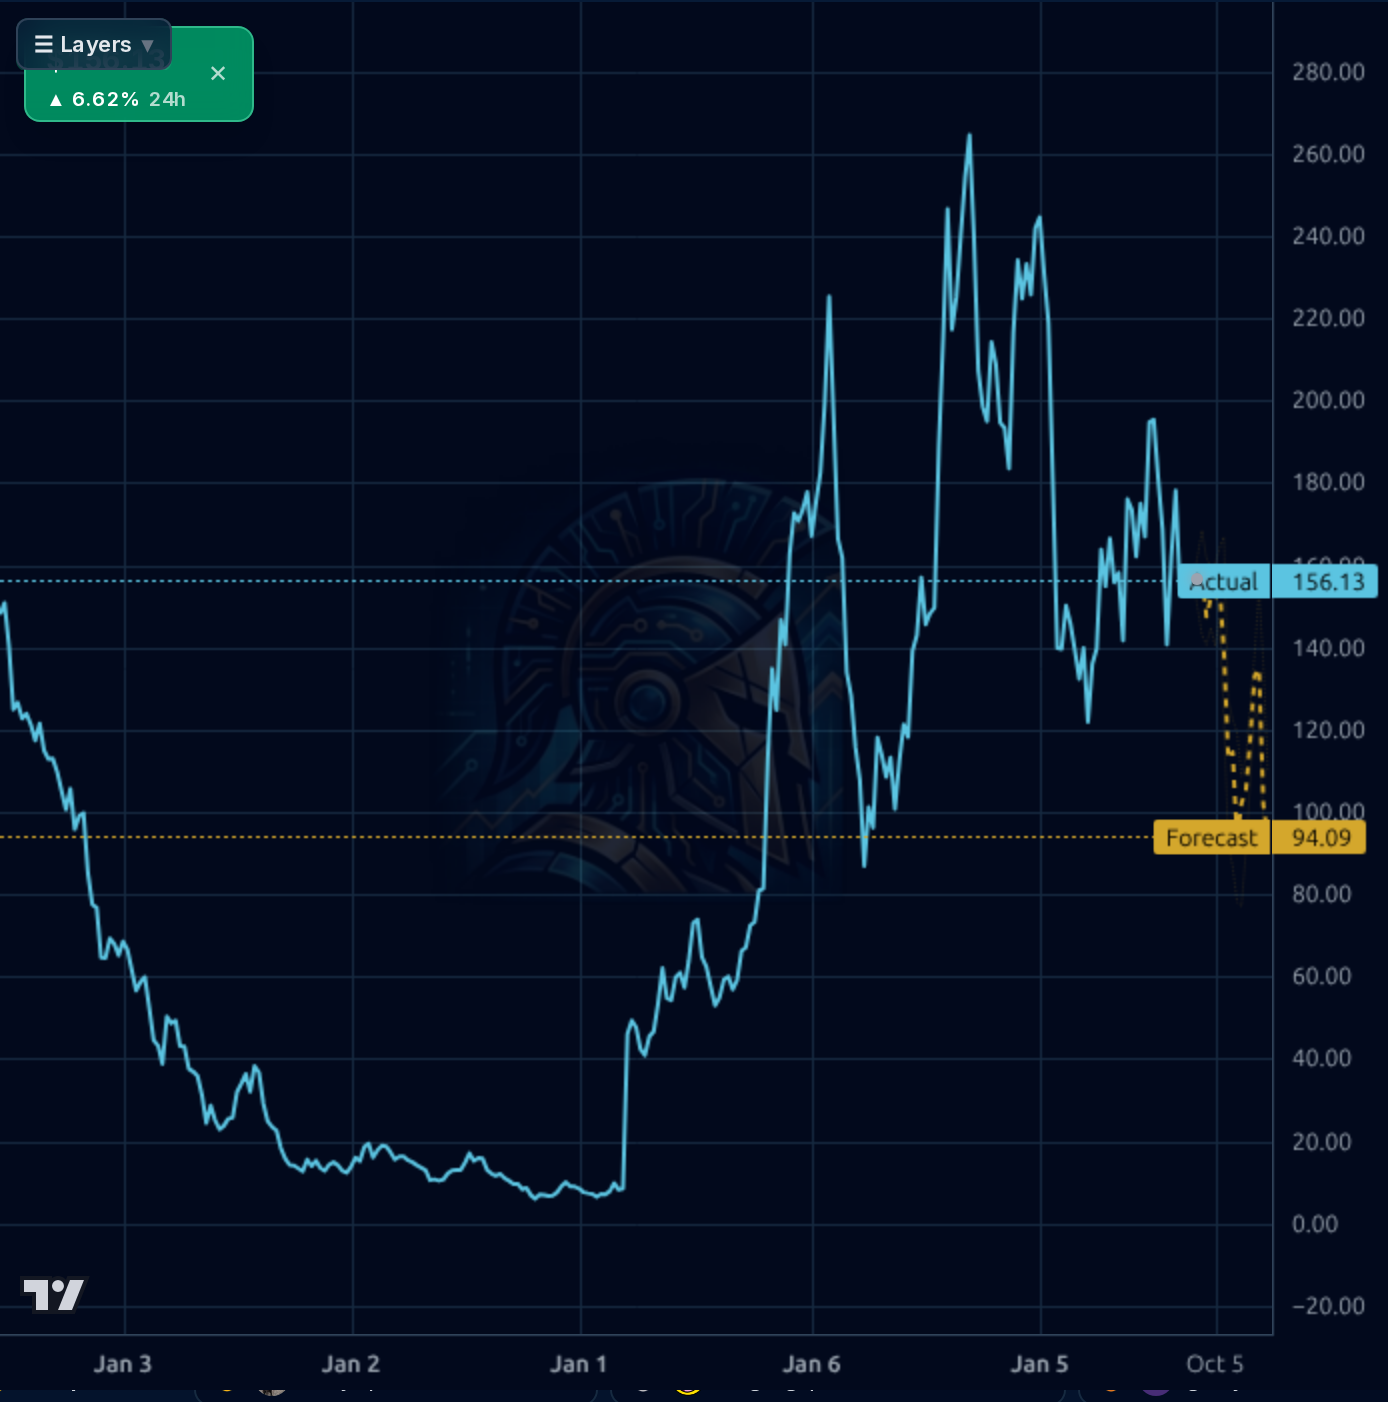
The multi-timeframe picture is a base-building attempt after a violent drawdown. Weekly chart shows RDDT is -45% from its 52-week high ($282.95) and has retraced most of the 2025 rally, with the forecast band pointing sharply lower to $94 — a warning that the long-cycle model sees more mean reversion. Daily chart shows price consolidating in a $140-$180 range with the 174 forecast overhead — RSI at 48.9 is neutral, SMA20 flat (+0.09%), SMA50 -7.9%, SMA200 -10.7%, so the stock is below all major moving averages but no longer collapsing. The 1h and 4h charts show a clean bounce off $146-148 into $156 with the near-term model forecast reaching for $164 (1h) and $191 (4h). Key levels: support $145-148 then hard support $135-140; resistance $160 (must reclaim to confirm base per prior dossier), then $175-185 supply. Notable: the 1d model forecast accuracy is 34% vs 66% naive baseline — the near-term bullish signal should be heavily discounted. Short float has ticked up from 12% to 14.3% (2.6-day cover), which sets up a squeeze mechanic if $160 breaks.
Signal: Piper Sandler audience data flagged RDDT's user base growing 8% MoM in August, the fastest monthly pace of 2026, which drove today's +6.6% pop — this directly speaks to the app-first engagement thesis and partially rebuts the Google-referral bear case. However, [DOC-3] notes Piper trimmed its target to $195 citing weaker U.S. DAU trends, and DA Davidson explicitly quantified the Google deal at <2% of 2026 revenue while flagging real search-traffic risk. Wedbush keeps RDDT on Best Ideas List betting AI licensing offsets Google volatility. Noise: comparisons to AppLovin, generic S&P 500 screening pieces, and unrelated 9/11 travel/Bitcoin macro chatter. Most material: the 8-K disclosing Chief Legal Officer transition (Aug 12) is a governance flag but not thesis-changing. Insider action is the loudest bearish tell — Huffman and Wong sold a combined ~$16M+ in mid-August after the Q2 print, with Huffman adding another $2.6M in end-August sales. That's a persistent, actionable cluster consistent with the prior dossier's warning, and it caps how aggressive one should be sizing here.
- Piper Sandler audience data: 8% MoM user growth in Aug 2026, the fastest monthly pace of the year — direct evidence app-first pivot is working
- AI data licensing 2027 contract renewal cycle with Google/OpenAI, currently ~$50-60M annualized run-rate, potential move to dynamic pricing ([DOC-4])
- $1B buyback authorization referenced in [DOC-4] gives capital return support with $1.49B cash on the balance sheet
- International ARPU expansion — [DOC-6] flags significant upside as international user monetization catches up to U.S. levels
- Q3 2026 guide from management implies continued high growth off the $805M Q2 base
- Google AI Overviews structural erosion of search referral traffic — remains the largest unquantified overhang
- Insider selling cluster: Huffman (CEO) and Wong (COO) sold ~$16M+ in mid-August plus additional $2.6M end-August — persistent leading caution signal
- Short float increased 2.4pp to 14.3% — crowded short can cut either way but signals institutional skepticism
- Forward P/E of 22 requires sustained 50%+ growth; any deceleration in Q3 guide triggers sharp multiple compression
- Chief Legal Officer transition (Aug 12 8-K) is minor governance noise but adds to executive turnover watchlist
- 1d model forecast is unreliable (34% directional accuracy vs 66% naive baseline) — near-term bullish signal should be discounted
- Weekly forecast band pointing to $94 suggests longer-cycle mean reversion risk if base fails
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord