RLX — AI Stock Forecast & Price Targets
Published 9/17/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live RLX price forecast →
RLX presents a compelling asymmetric risk/reward profile: it possesses a fortress balance sheet and clear international growth vectors (70% of revenue), but its current valuation discount is heavily counterbalanced by deteriorating cash flow quality and persistent regulatory overhangs. The stock remains technically weak, suggesting patience is required until the operational narrative translates into sustained capital appreciation.
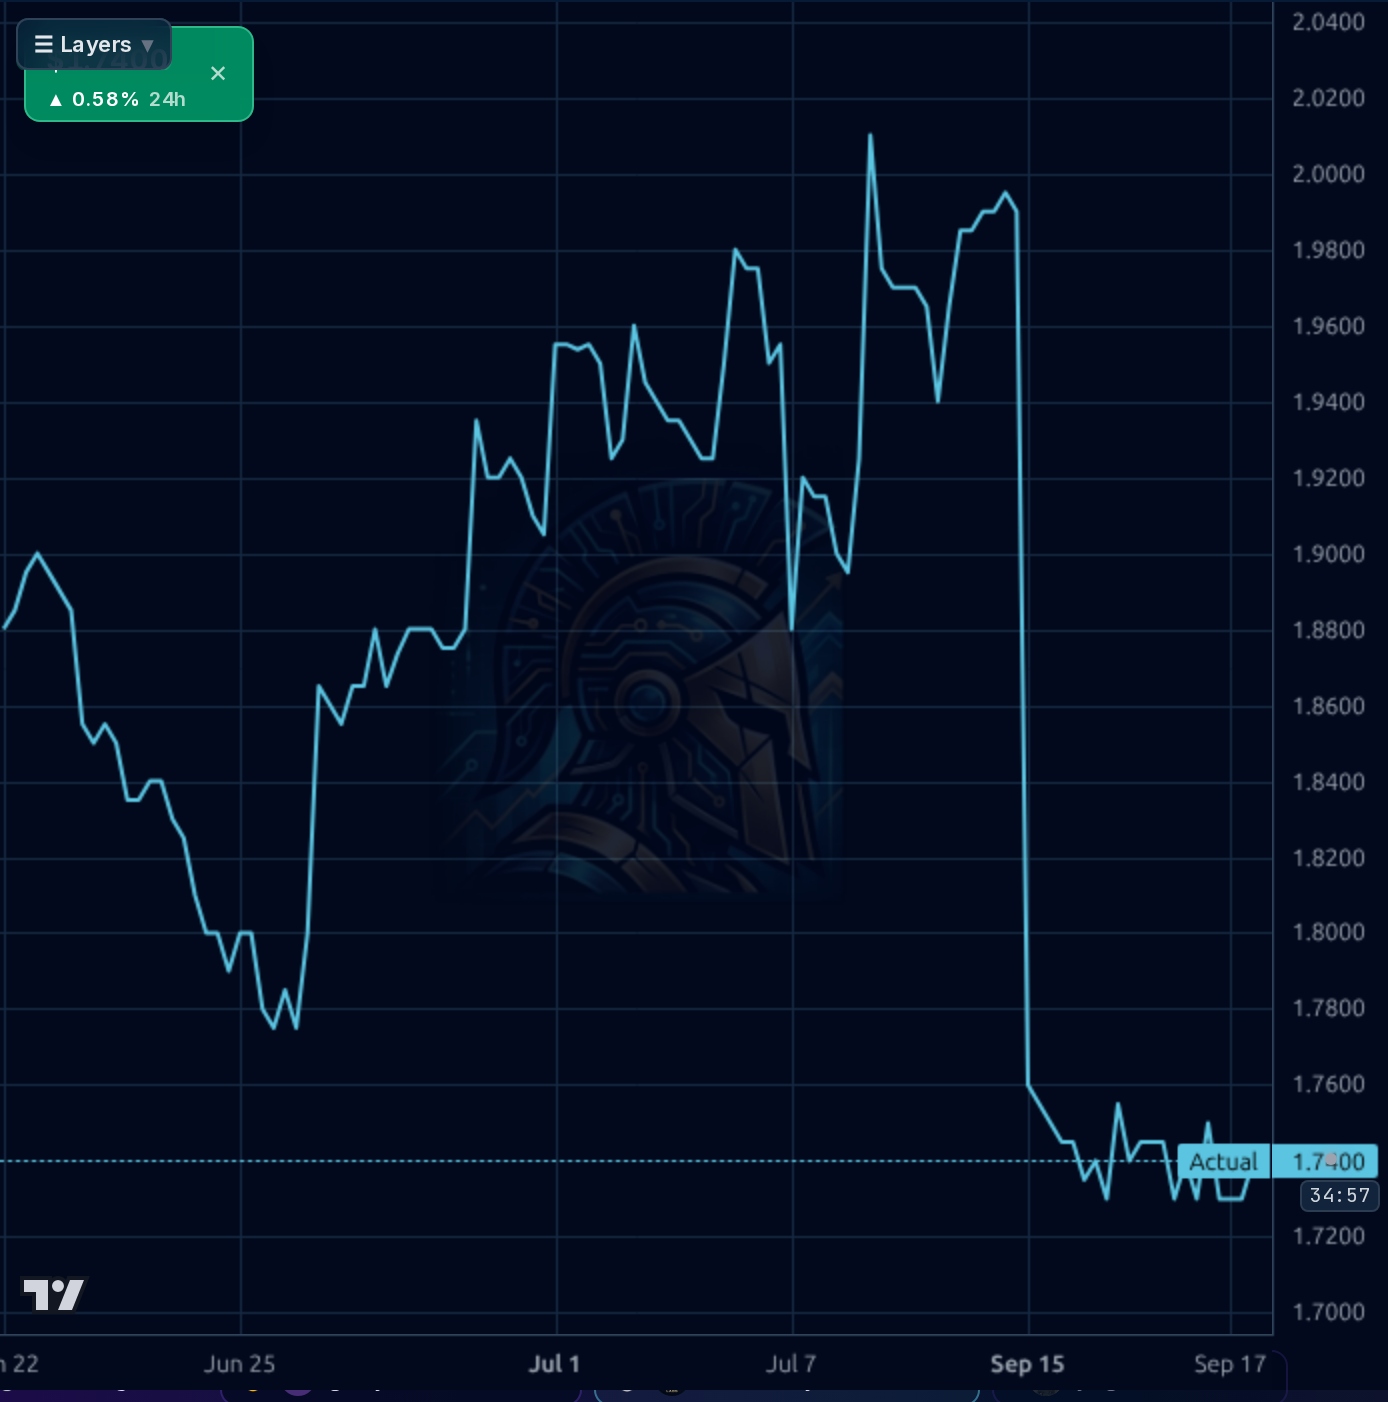
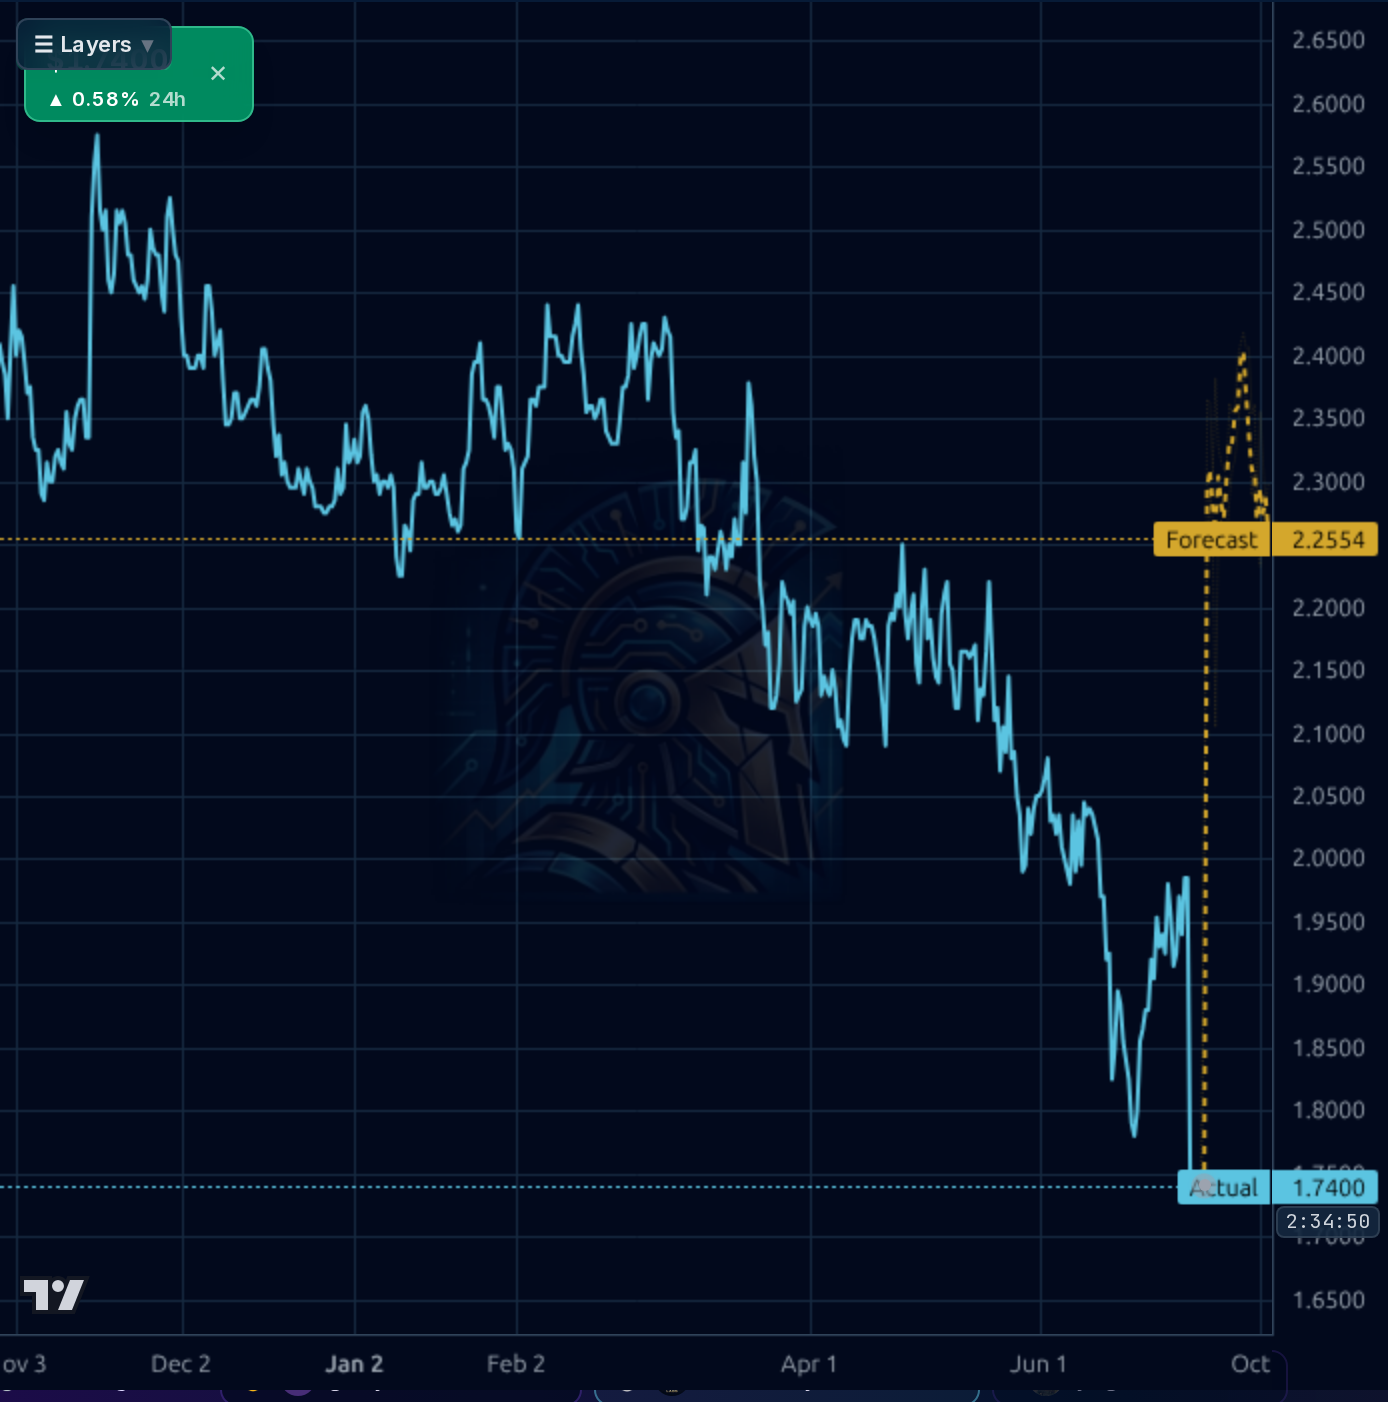
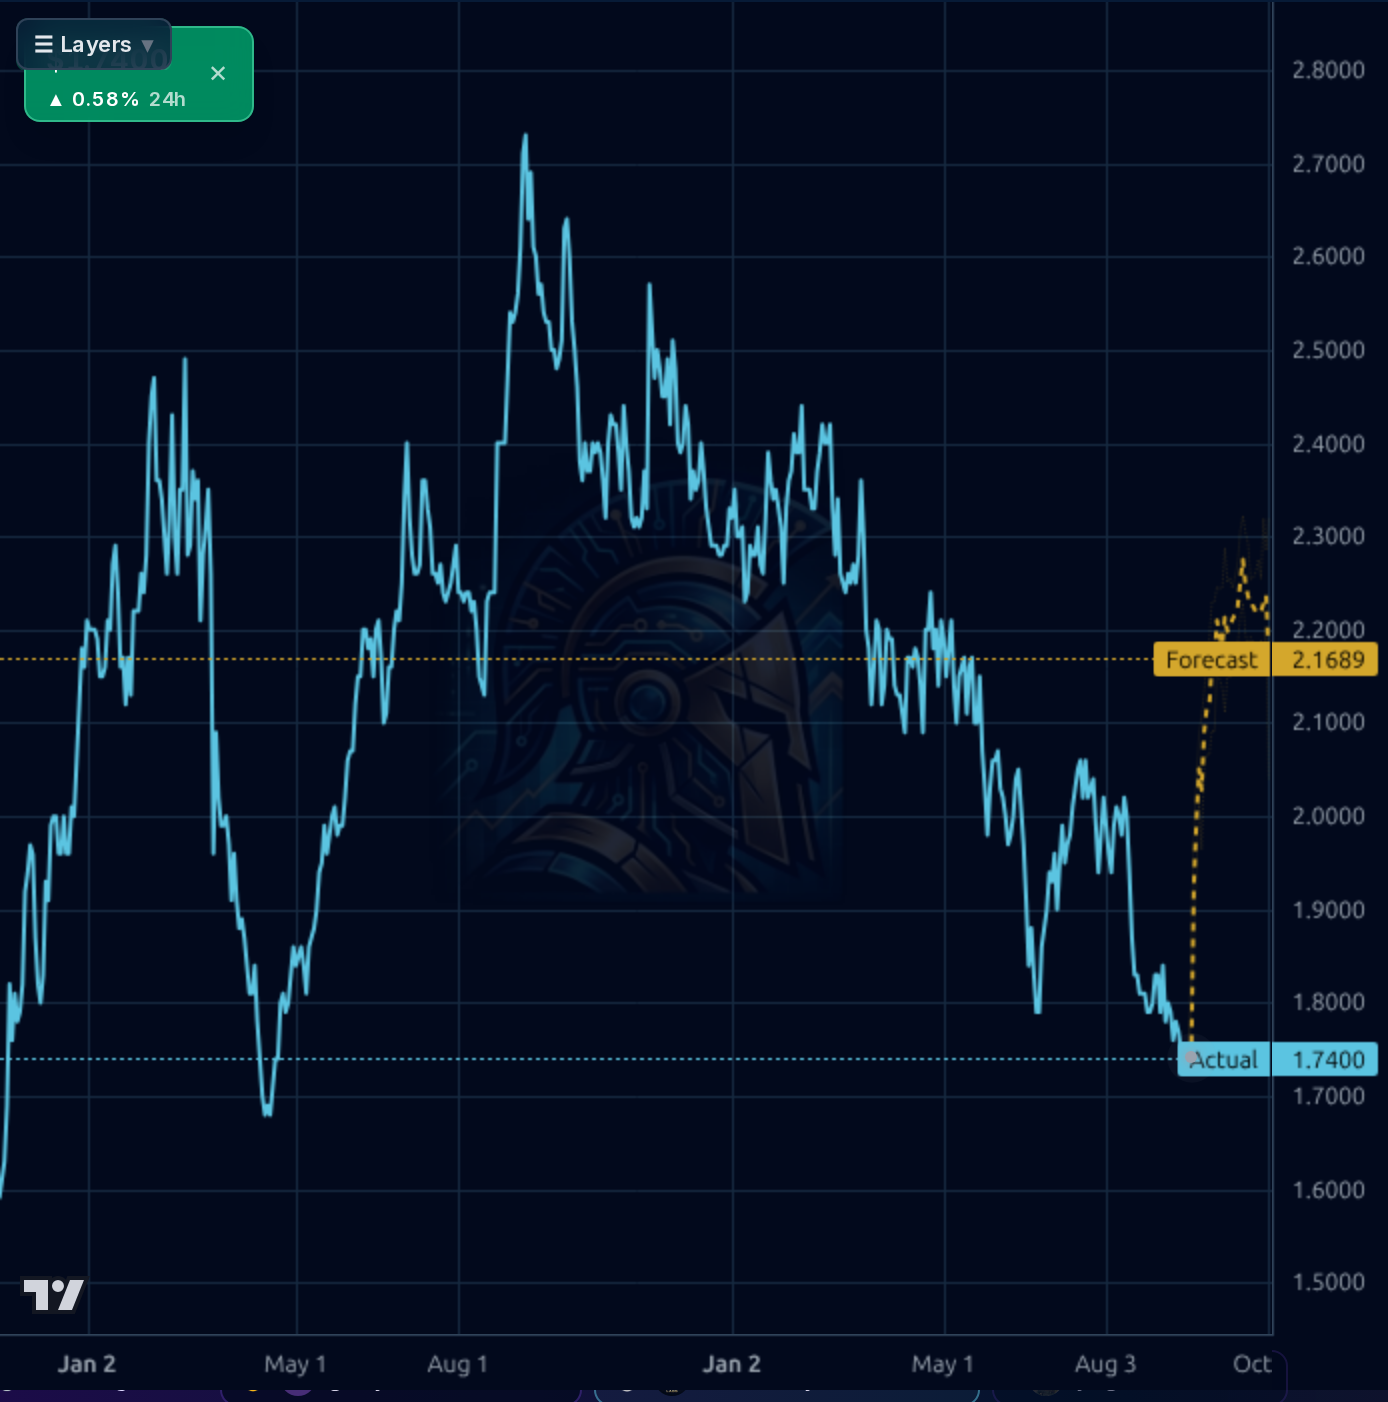
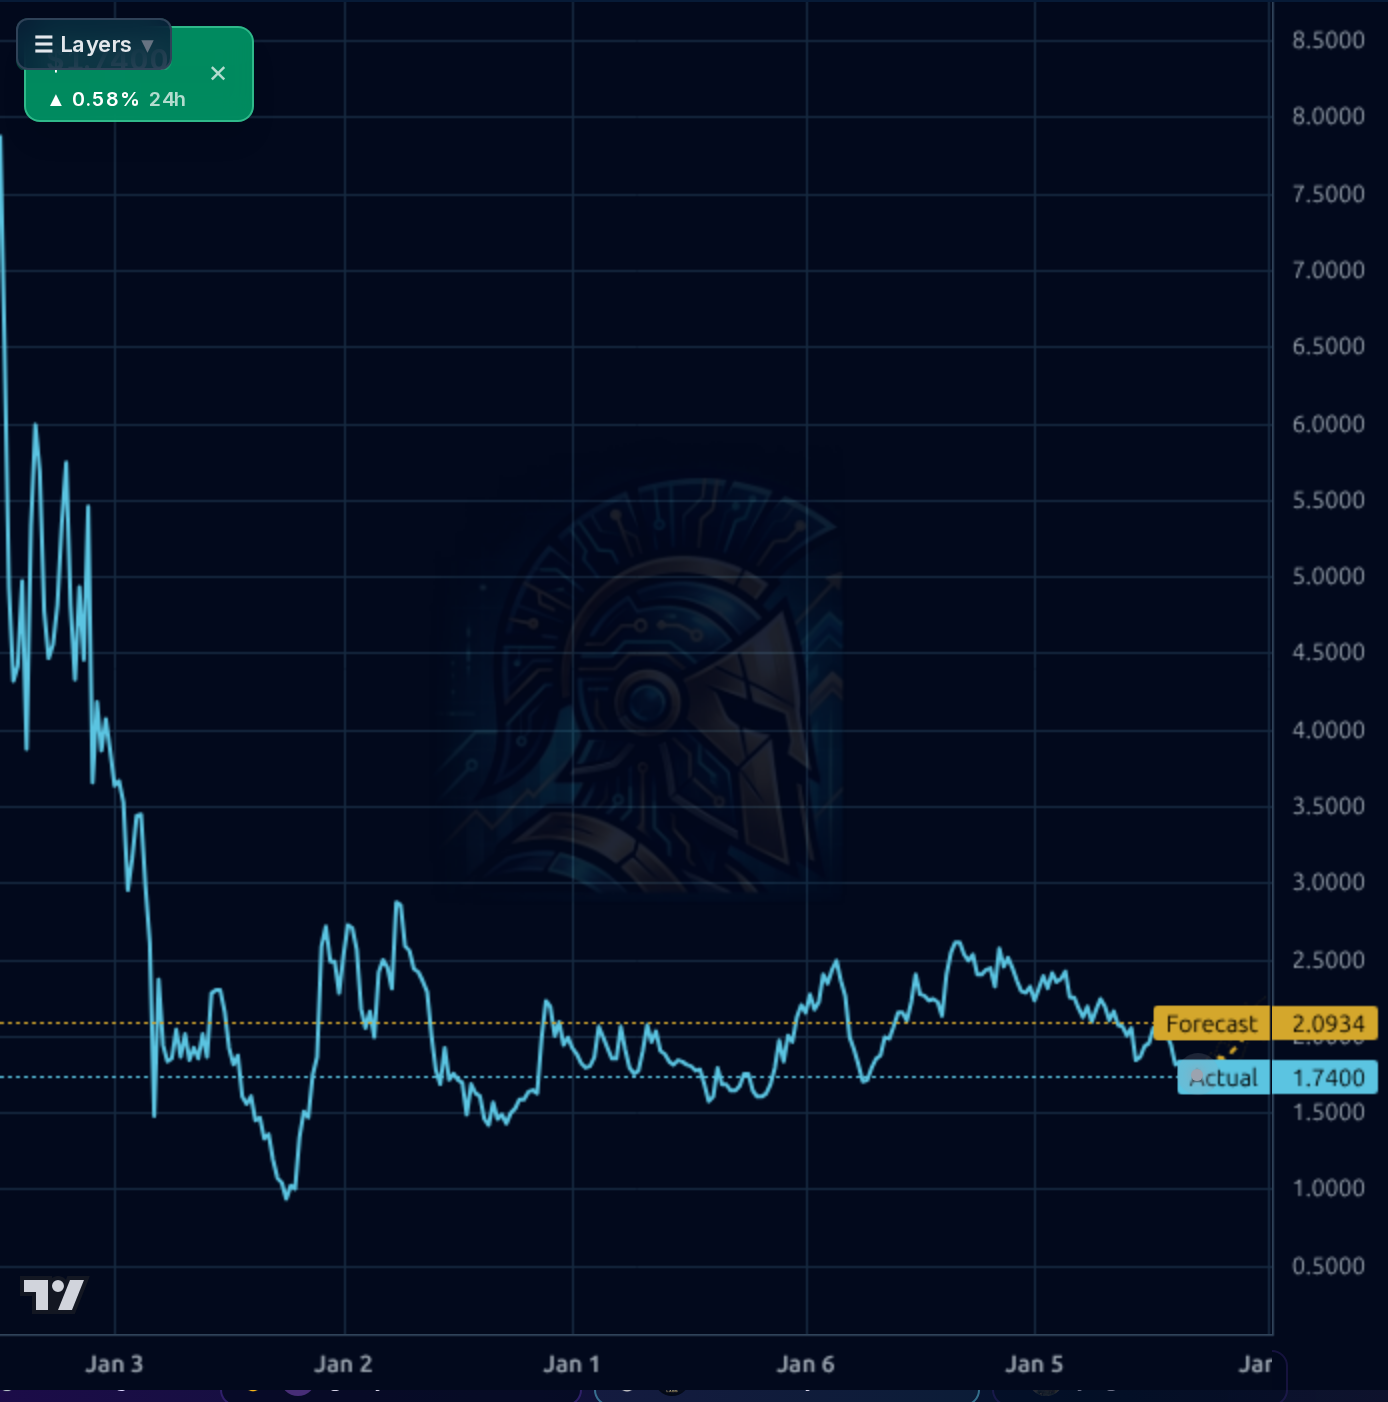
Wait for confirmation of support at $1.76-$1.78 (52-week low area). A break below this level invalidates near-term bullish theses; a bounce suggests buying opportunities on dips, sizing cautiously due to high volatility and poor short-term momentum.
The thesis hinges on the successful integration of the European acquisition driving sustained margin expansion and cash flow recovery. If OCF stabilizes above $100M/quarterly for two consecutive quarters, a re-rating towards the base target ($2.15) becomes plausible within 6 months. The primary catalyst is positive disclosure regarding international deal economics.
The terminal thesis relies on RLX successfully establishing itself as a global, diversified nicotine product leader, leveraging its cash pile for strategic M&A or buybacks to maintain shareholder value despite regulatory headwinds in China.
The balance sheet is exceptionally strong with a high current ratio of 10.61 and significant cash reserves ($8.76B). The revenue trend shows positive momentum, with international sales comprising roughly 70% of revenue, indicating successful pivot execution. Margins are improving, evidenced by the operating margin recovery to 16.6% in Q2 2026 from previous periods. However, cash flow quality is a major concern; TTM FCF is negative (-$621M), and the dividend payout ratio (implied by the $0.11 dividend on current earnings) is unsustainable at over 100%. Capital allocation remains key—the company has optionality via buybacks funded by cash, but this masks underlying operational weakness.
The charts show a clear multi-month downtrend, with the price trading significantly below major moving averages (SMA20: -3.41%, SMA50: -9.37%). The recent action suggests selling pressure despite positive fundamental news flow. While the model's 1d forecast accuracy is low (17% vs 84% naive), the longer-term technical picture remains bearish, suggesting any upward move will be met with resistance until a clear breakout above key support levels near $1.76-$1.78 is established.
The primary news catalyst is RLX's successful international expansion, where European sales now account for approximately 70% of revenue, bolstered by the August 2026 acquisition. This validates the pivot away from domestic reliance. The broader market news regarding SEC actions and crypto regulation is largely noise for a tobacco/vaping company like RLX, providing only general sector context rather than direct actionable insight.
- International revenue mix: The shift of ~70% of total revenue to international markets (including the European distributor) de-risks the company from purely domestic Chinese regulation.
- Product diversification: Expansion into higher-margin, less regulated segments like nicotine pouches and modern oral products provides a structural growth hedge.
- Capital deployment optionality: The substantial cash pile ($8.76B) allows for buybacks or strategic investments without immediate dilution.
- Unsustainable dividend payout ratio (103%+ based on current earnings), signaling potential future dividend cuts if FCF does not improve.
- Structural regulatory risk in the core Chinese market remains a persistent overhang.
- Technical breakdown: The stock is trading near 52-week lows and below all major moving averages, indicating deep bearish sentiment that could persist regardless of operational improvements.
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord