UBER — AI Stock Forecast & Price Targets
Published 9/19/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live UBER price forecast →
Uber is a high-quality asset-light FCF compounder ($6.5B TTM FCF, 38% ROE, 15.5x P/E) caught in a corrective phase at $70.50, down ~31% from the $102 high, with the model's forecast band pointing to ~$67 (below spot) and directional accuracy beaten by the naive baseline in both timeframes. The Delivery Hero acquisition cleared a key regulatory hurdle and insider buying (Khosrowshahi $10M) is supportive, but the Waymo rift, soft Q3 guidance, and a $40M legal judgment cap near-term upside. Accumulate on weakness with a bias toward the $66-68 support zone.
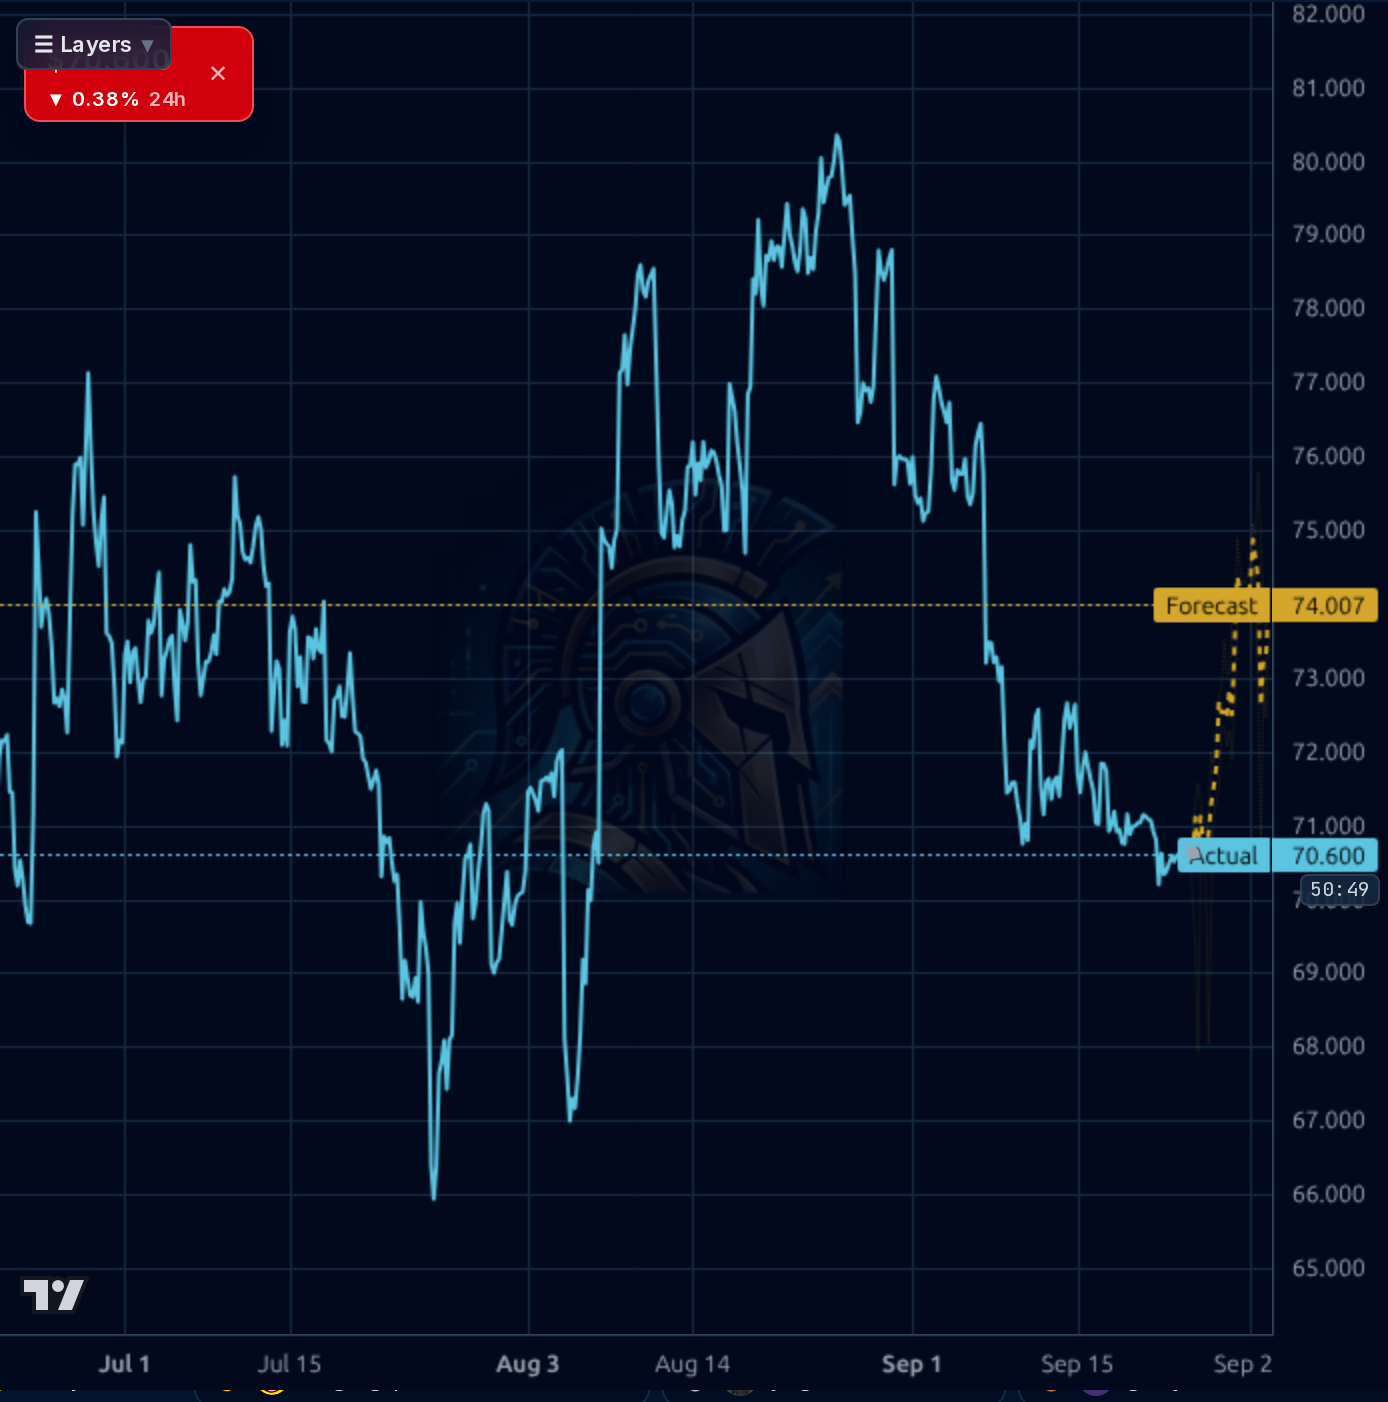
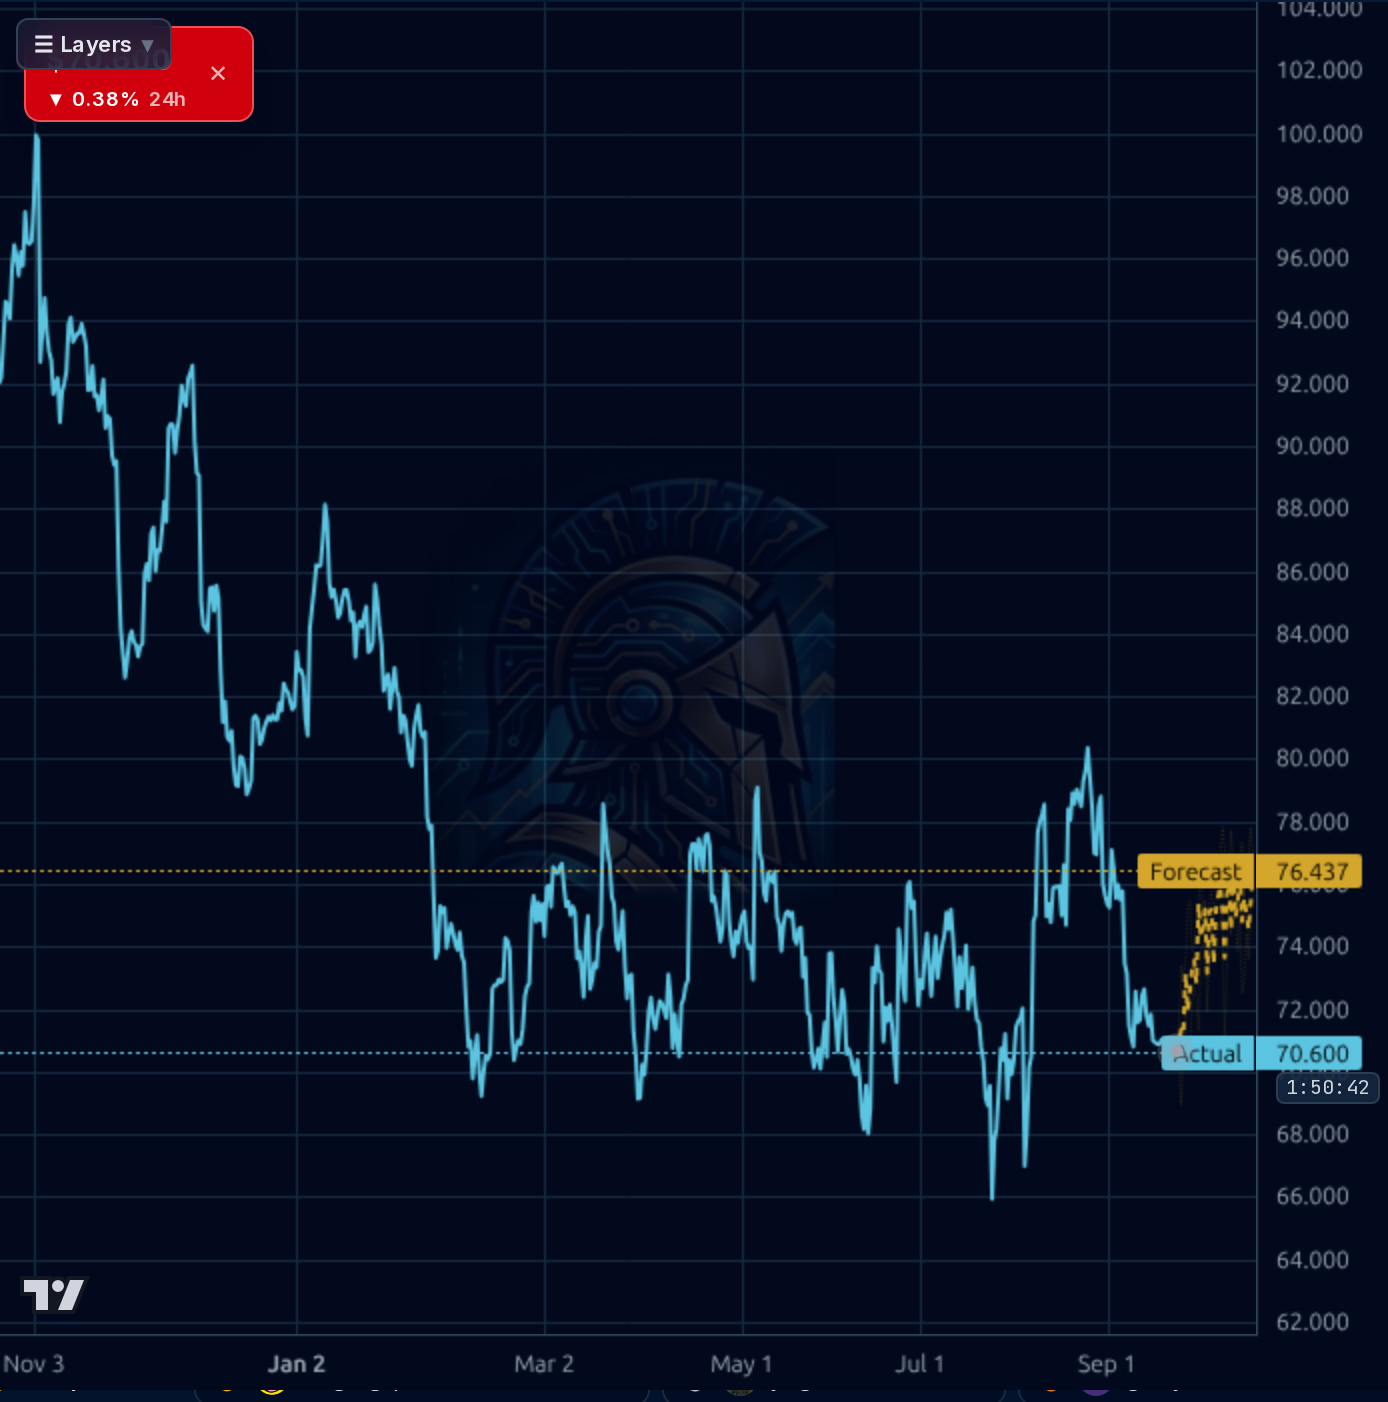
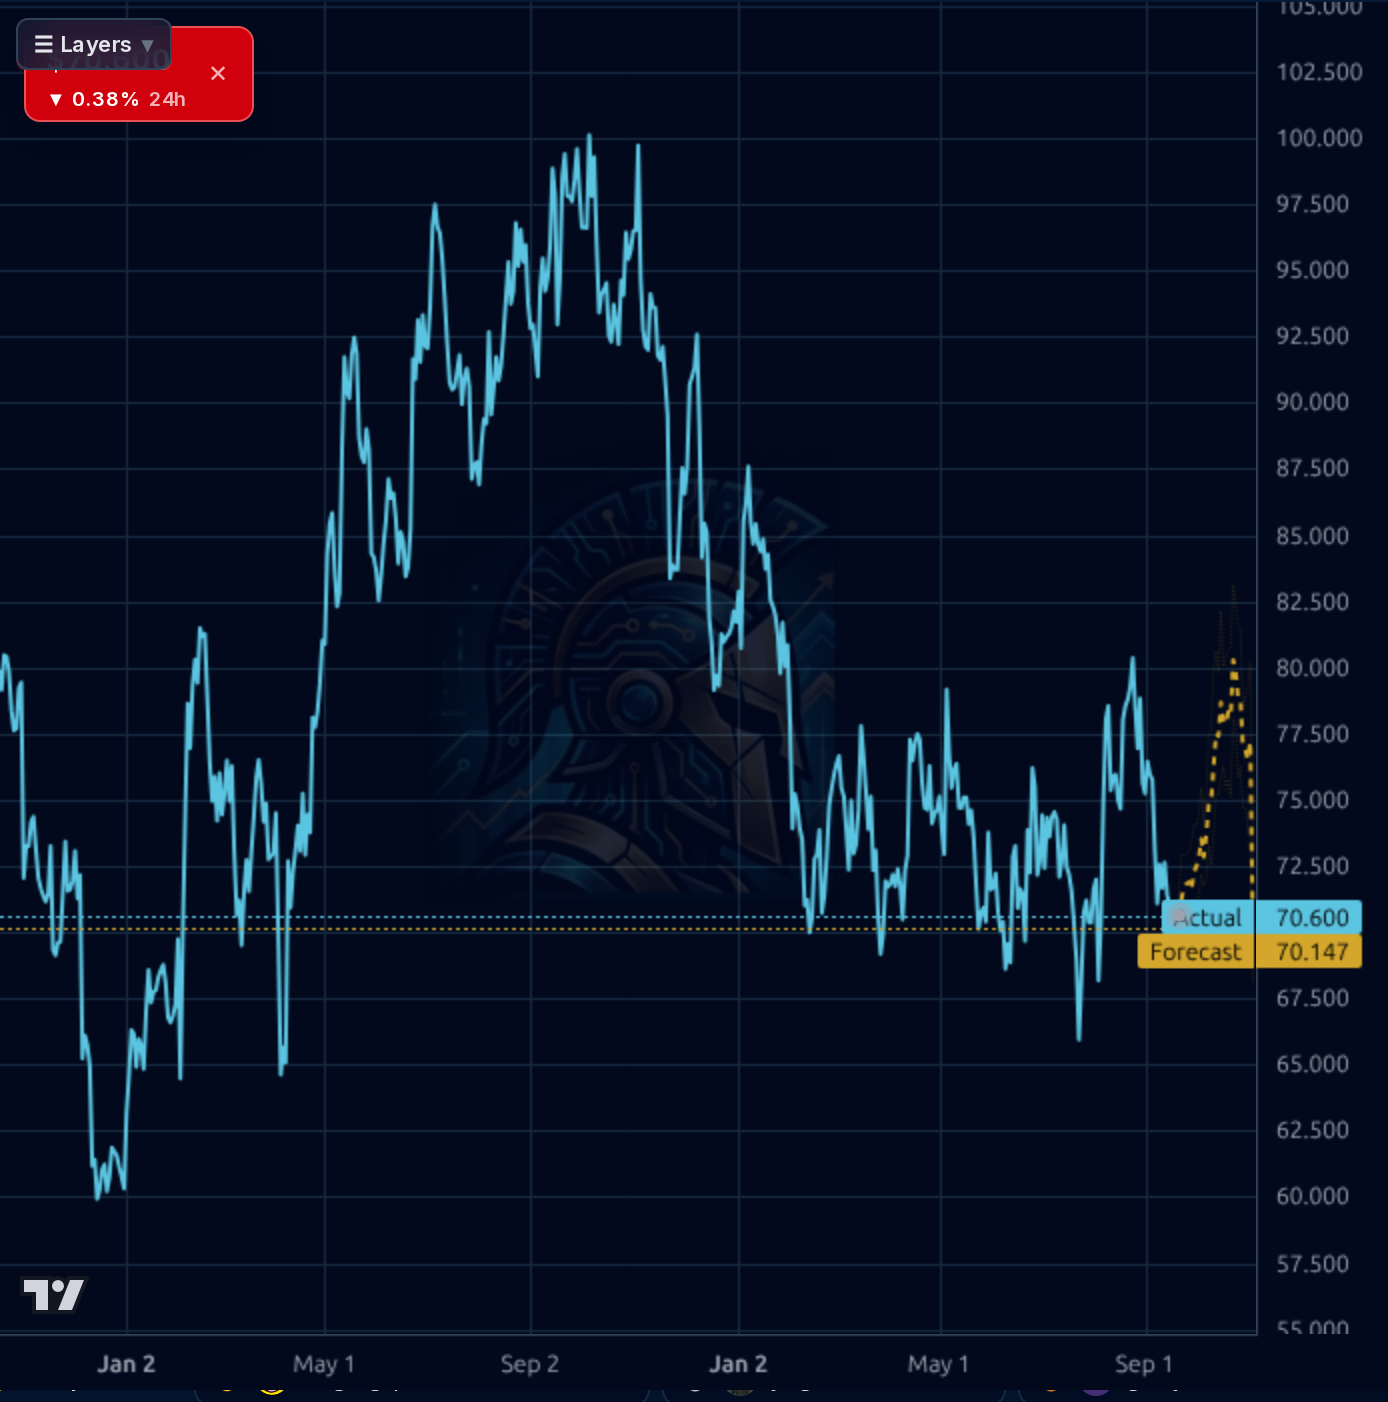
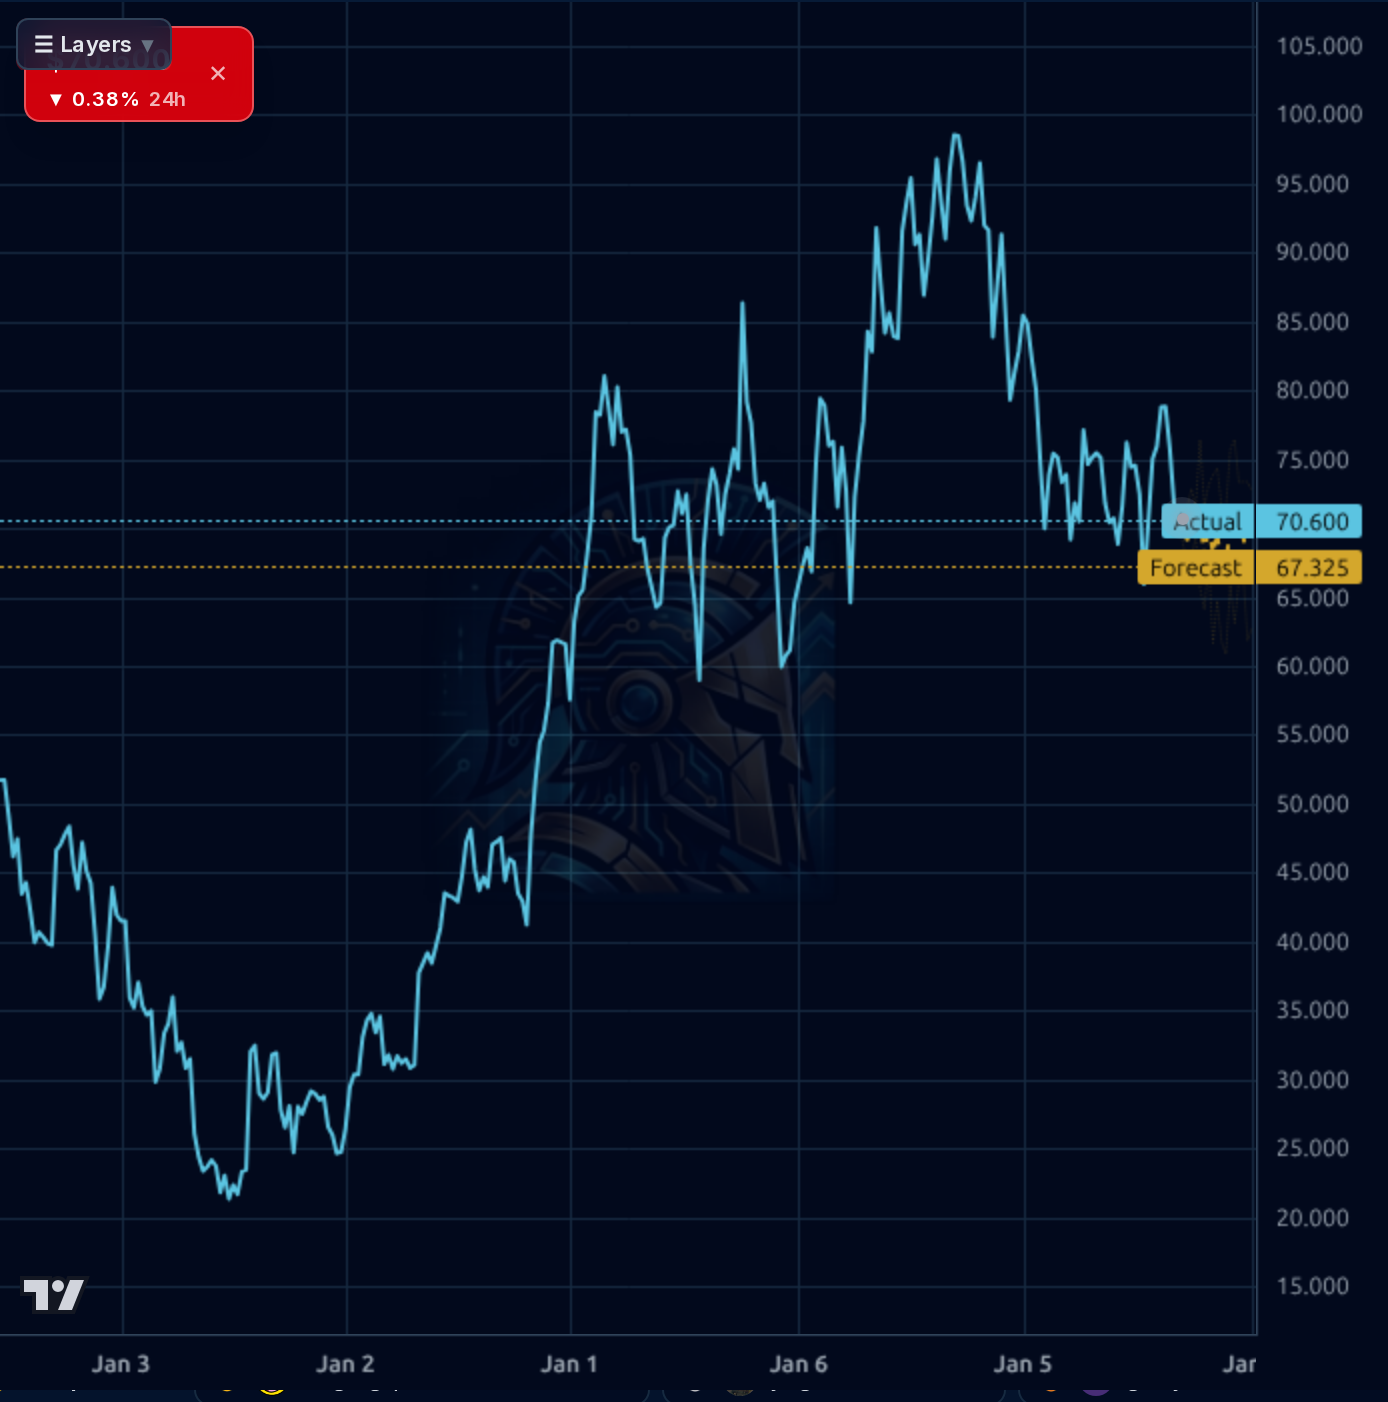
Neutral-to-cautious over 1-4 weeks. The stock is below all moving averages with a forecast band at/below spot and momentum weak (RSI 39). Avoid chasing; prefer accumulating on dips toward $66-$68 support. Invalidation on a daily close below $65.40 (52-week low) opens $60. Pre-earnings (Nov 3) is a binary event — do not size into it; treat any 1-4 week target as pre-earnings only.
1-6 month thesis centers on Delivery Hero integration and AV monetization, with an expected range of $66 (bear) to $82 (base) and upside to $92 on a clean guidance print. Catalysts: Delivery Hero EU antitrust clearance timing, Q3'26 bookings/margins (Nov 3), and AV deployment numbers. What would change my mind: a return above $78-$82 on volume would signal trend recovery; continued guidance misses or a Waymo breakup confirmation would target $60.
1-3 year terminal thesis: Uber remains the essential multi-modal mobility and delivery platform with durable FCF and operating leverage, but its growth reacceleration depends on successfully integrating Delivery Hero and deploying $10B+ into AV infrastructure without impairing cash conversion. Multi-year drivers: robotaxi platform buildout (28 cities by 2028), advertising, and delivery scale. Biggest structural risk: AV execution and capital allocation — if the $10B+ bet underdelivers or Waymo-style partners defect, the re-rating catalyst is lost.
Revenue is compounding at ~12-17% YoY with Q2'26 record revenue of $14.19B and gross bookings +22%, while operating margins hold at ~13.3% and net margins expanded sharply (Q2 net margin 16.9%, though prior quarters were depressed by one-offs). Balance sheet is solid: $4.87B cash, $27.3B equity, debt/equity at just 0.54, and TTM free cash flow of $7.2B funding the $14.8B Delivery Hero acquisition plus $10B+ AV capex. ROE of 38% and ROIC of 24% reflect genuine operating leverage. What's working: FCF machine, advertising ancillary revenue, and margin expansion. What's strained: working capital turned negative (-$2.34B) and quick ratio at 0.84 signal tighter liquidity, and the AV buildout is the capital-allocation overhang. Valuation at 15.5x trailing / 16x forward P/E is cheap relative to the 5-year TSR of 55.8%, but PEG of 2.90 implies the market still prices in deceleration.
On the 1d chart, price is at $70.60 with the Kronos forecast band showing ~$67.25 (below spot, mildly bearish) and a lower-band read near $70.15. On the 1wk chart, price sits at $70.60 with the forecast band near $70.15, roughly inline. The stock is below SMA20 (-5.79%), SMA50 (-4.31%), and SMA200 (-6.83%), confirming a broad downtrend with no trend recovery. RSI(14) at 39.33 is weak but not oversold. Key support is the $66-$68 weekly zone (52-week low $65.42 just below); resistance at $74-$75, then $78-$82, with the $85-$90 gap zone above. The model's forecast band being below spot on the 1d chart, combined with directional accuracy beaten by the naive baseline (63% vs 91%), means the forecast should be discounted — treat the ~$67 read as a weak-bias reference, not a conviction signal.
Signal: Uber's $15B Delivery Hero takeover cleared a key regulatory hurdle (boards recommended acceptance at €41.50/share), advancing European delivery consolidation. Insider buying is a genuine conviction signal — CEO Dara Khosrowshahi bought $10M and another insider bought $4.1M in early September, offsetting routine sales. The Waymo partnership remains fractured over robotaxi operations and conflicting regulatory positions, a structural overhang on the AV thesis. Noise: a routine $40M wrongful-death judgment (immaterial to a $144B cap company), and the CEO's family business being seized in Iran is a personal story, not a company catalyst. Broader market context shows late-markups and distribution with deteriorating breadth (42.2% above 200dMA), favoring a defensive, valuation-aware stance.
- Delivery Hero acquisition ($14.8B) cleared a key regulatory hurdle at €41.50/share, advancing European delivery consolidation and cross-sell opportunity.
- AV robotaxi platform: $10B+ capital deployed across 30+ AV partners (Lucid, Rivian, Baidu) targeting 28 cities by 2028, positioning Uber as the distribution layer for autonomous mobility.
- Advertising revenue stream providing high-margin ancillary income across Mobility, Delivery, and Freight verticals.
- Operating leverage compounding toward sustained mid-teens margins via scale improvements and the $6.5B TTM FCF machine.
- Q2'26 gross bookings +22% and record consumers demonstrate continued network-effect engagement despite revenue slightly missing consensus.
- Growth deceleration: Q3 guidance trailed expectations and bookings momentum is softening, a primary overhang on the re-rating thesis.
- Waymo rift: deterioration of the robotaxi partnership and conflicting regulatory battles threaten the 'platform for AVs' narrative in key markets.
- Capital allocation strain: $10B+ AV capex combined with the Delivery Hero M&A thins the FCF cushion and raises execution risk.
- Valuation: PEG of 2.90 and 16x forward P/E leave little cushion if growth disappoints, despite cheap trailing multiples.
- Liquidity: negative working capital (-$2.34B) and quick ratio of 0.84 signal tighter short-term liquidity to monitor.
- Regulatory overhang: multi-jurisdictional gig-worker legislation and AV regulation (DC, EU) create operational uncertainty.
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord