USAR — AI Stock Forecast & Price Targets
Published 9/16/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live USAR price forecast →
USA Rare Earth remains a policy-driven story stock with a fortress $1.53B cash balance and a vertically integrated mine-to-magnet vision, but the fundamentals ($13M TTM revenue, -$284M FCF, P/S ~430x) leave zero margin for execution error. Technicals are broken across all timeframes with price sitting -22% below the 200-day SMA at $15.10, and the recent L3-bearish institutional ownership collapse (55.9%→37.0%) plus doubling of short float (8.9%→17.0%) signal that smart money is de-risking into the 2027 policy catalyst. Accumulate carefully on weakness with tight sizing — the setup is asymmetric long-term but the near-term tape and crowd positioning argue against chasing.
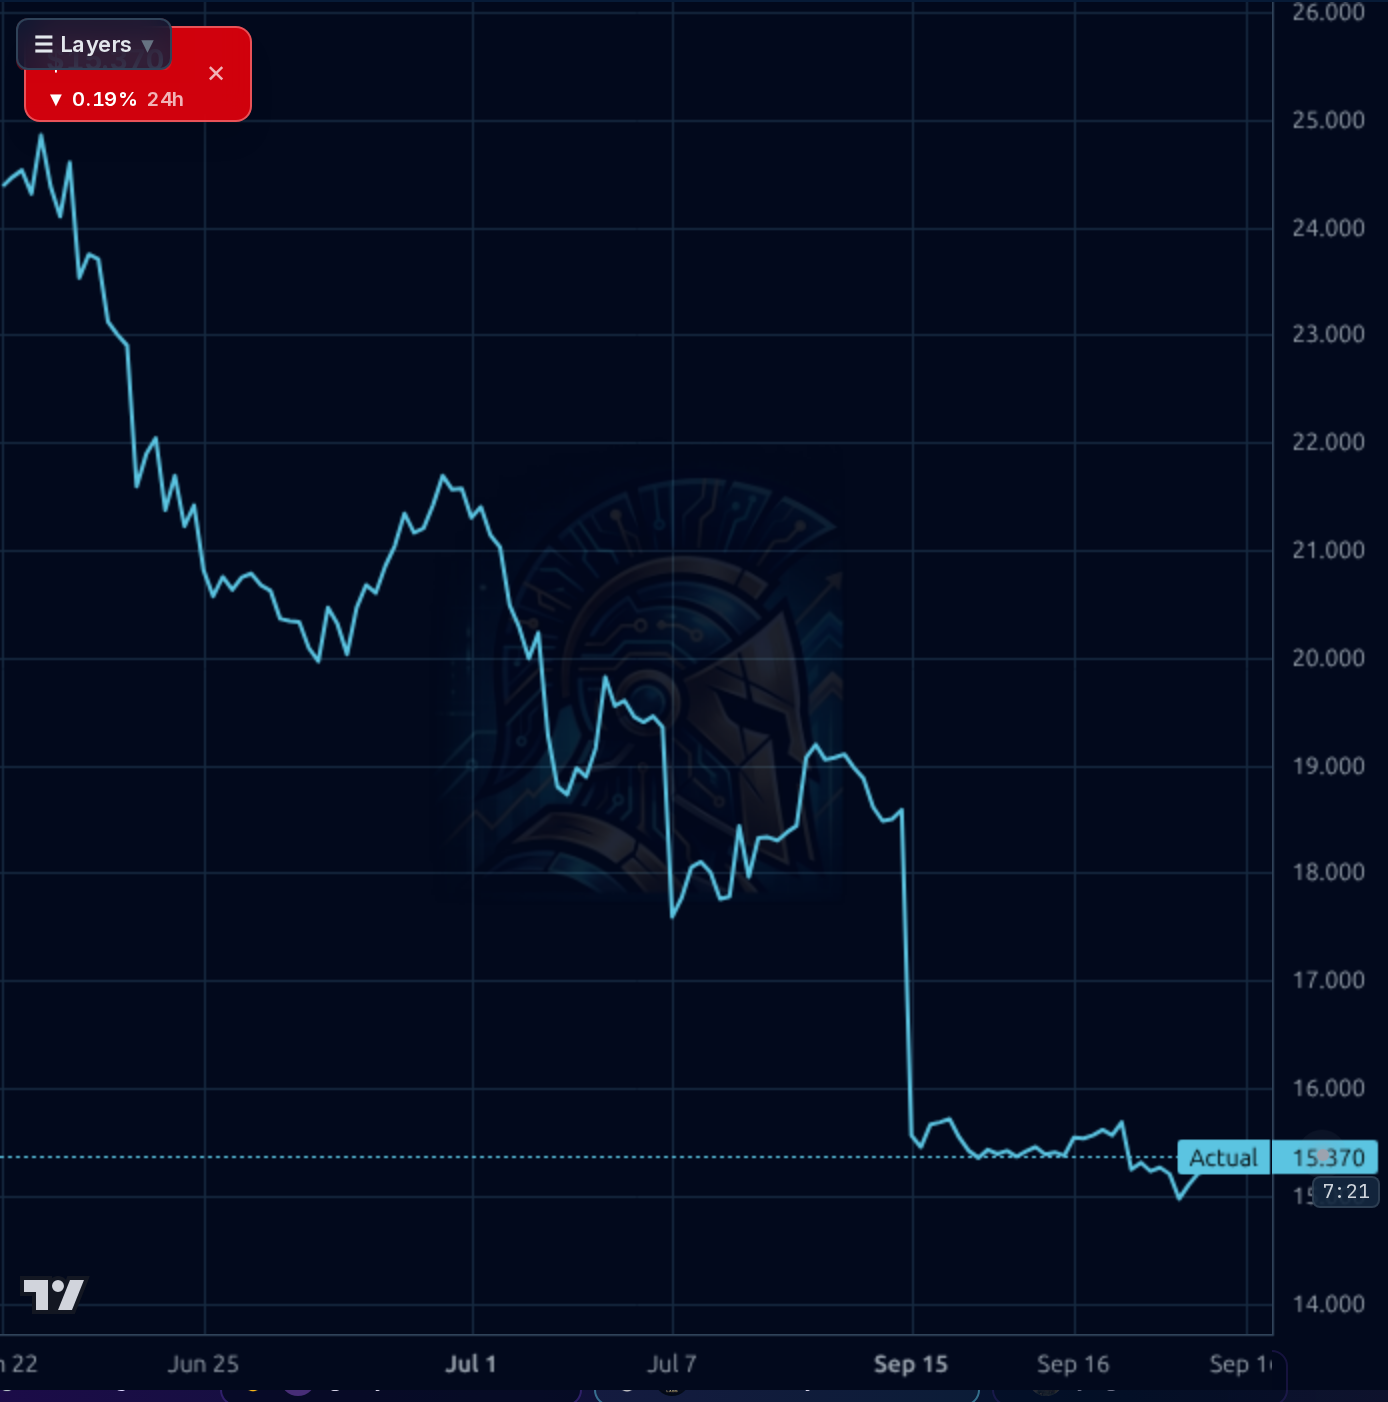
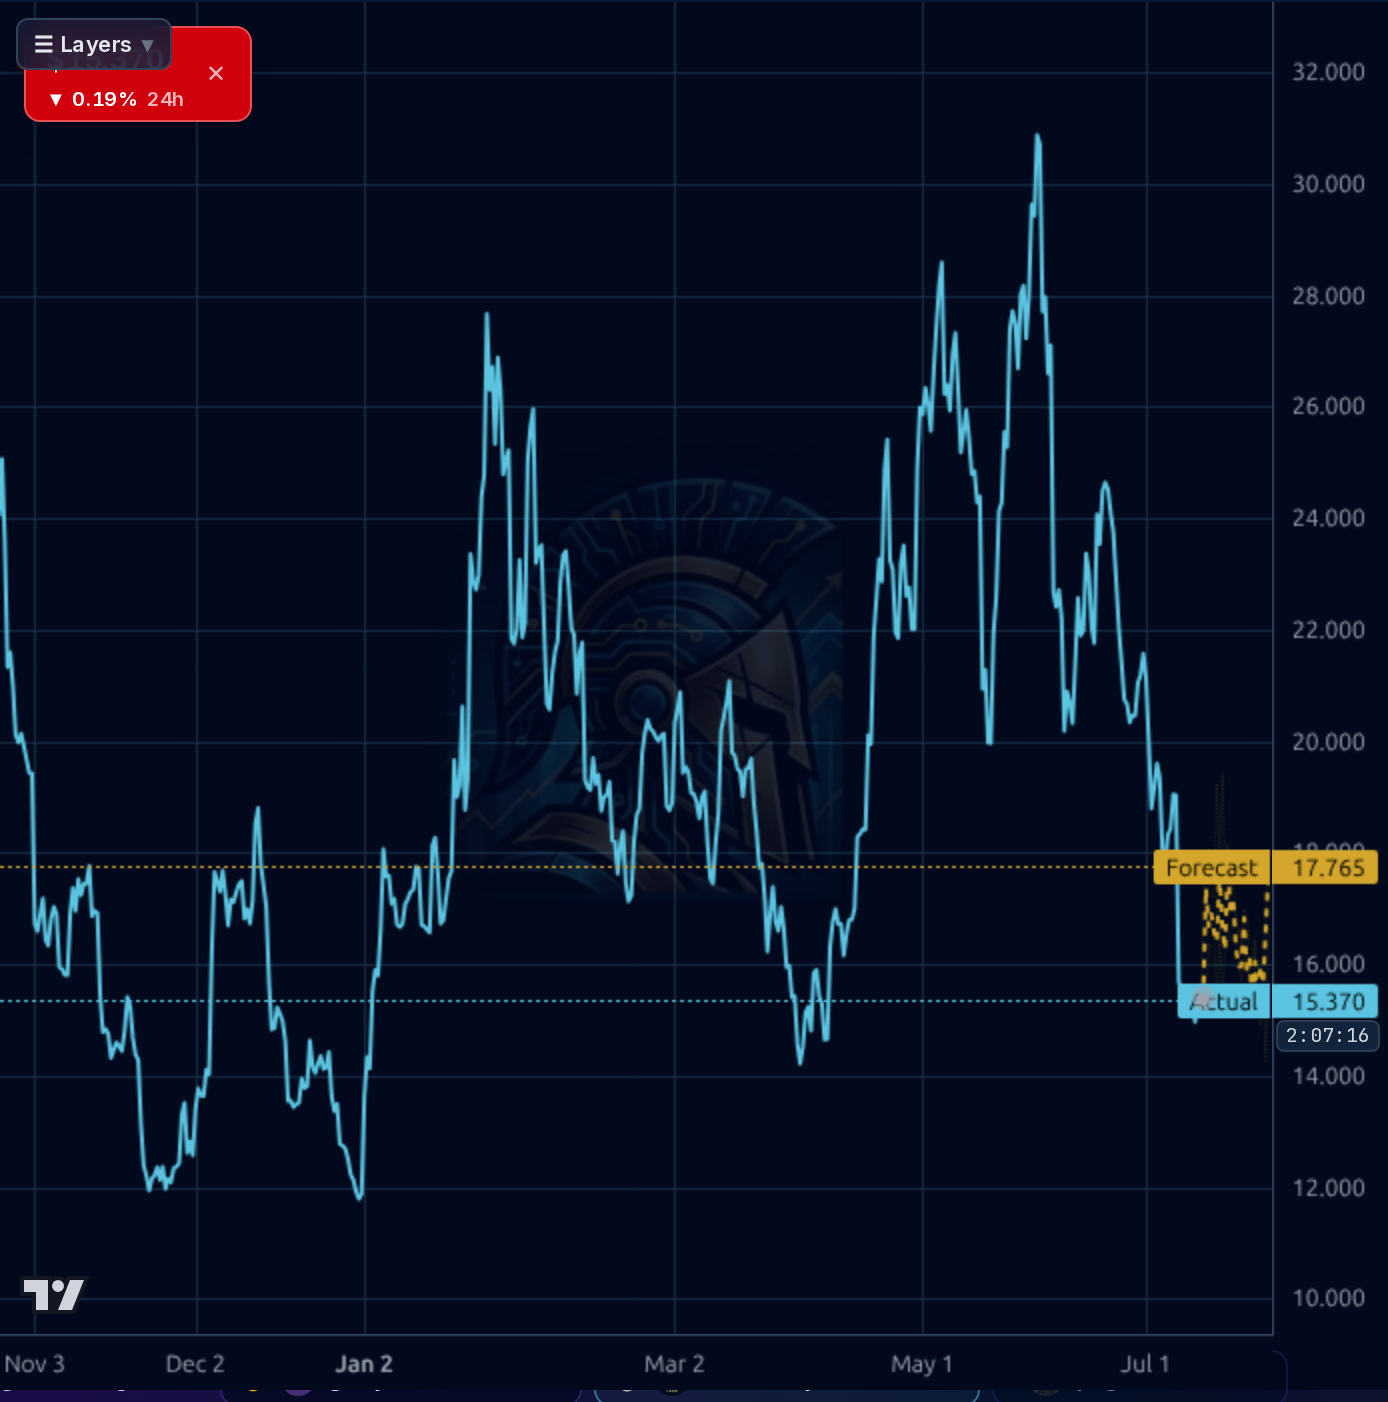
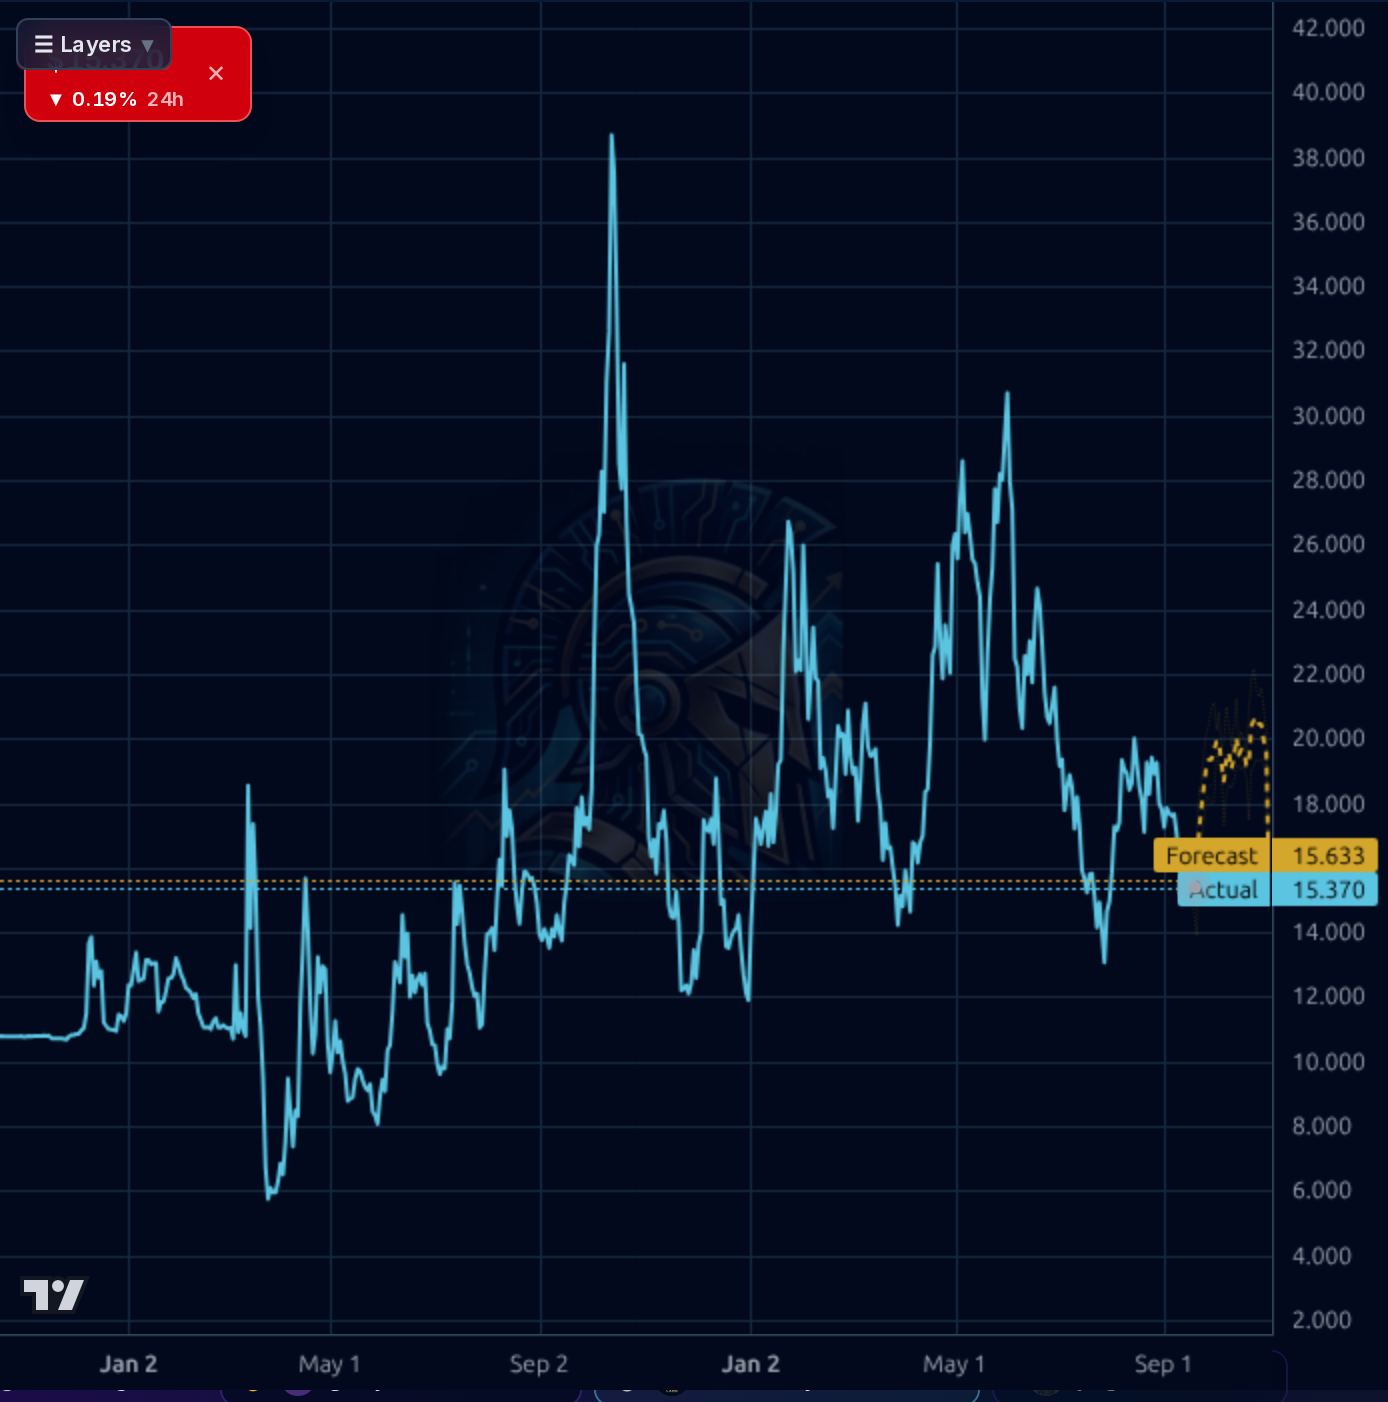
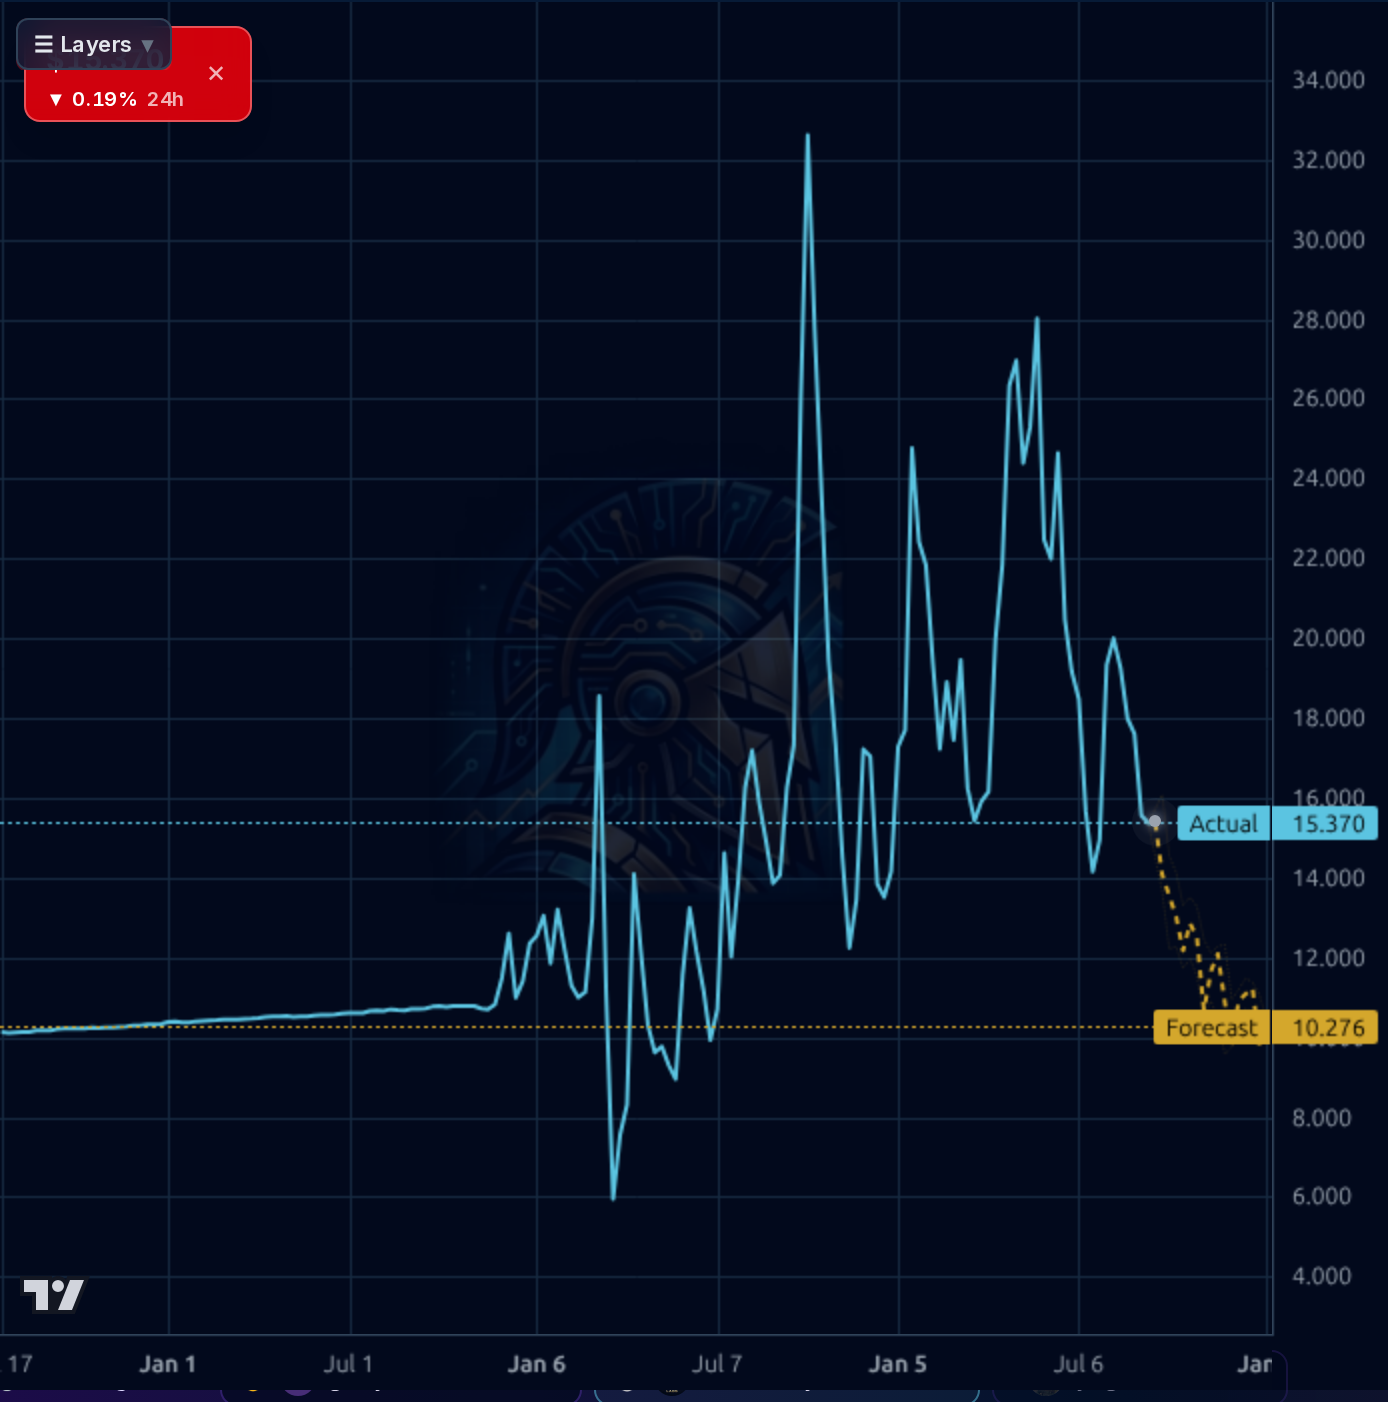
1-4 week view: Do not chase. Price is in a fresh breakdown from $18.50 with the tape distributing at the lows. If already long, hold small; if flat, wait for either (a) a reclaim of $17.00 on volume to confirm the breakdown was a shakeout, or (b) a tag of $13.50-$14.00 for a defined-risk accumulation entry with stop below $12.50. Sizing should be 1/3 of any intended full position given ~7% daily ATR. Invalidation: close below $12.50 confirms trend continuation toward the $11.45 52-week low.
1-6 month view: The setup improves materially if (a) Q3'26 revenue prints >$10M showing scale, (b) cash burn stabilizes rather than accelerating, and (c) institutional ownership stops bleeding. Base case is a re-rating back toward the $18-$22 breakdown zone as the 2027 policy catalyst comes into focus and Serra Verde integration milestones publish. Expected return range: -20% to +45% from current $15.10. Change my mind: an acceleration in FCF burn above -$150M/quarter without matching revenue scale, or another material dilutive raise, would flip the thesis to sell.
1-3 year view: If USAR successfully commissions the Stillwater magnet facility at commercial scale and captures a meaningful slice of the ~2027 US defense/EV magnet demand pool freed by the Chinese import prohibition, this is a multi-bagger from current levels — the vertical integration is genuinely rare among Western peers. Terminal thesis requires revenue scaling from $13M TTM to at least $200-300M by 2028-2029 to justify current market cap, and execution risk on that trajectory is enormous. Biggest structural risk: Chinese rare-earth pricing counter-attack post-2027 (dumping to impair Western project economics), which would compress unit margins even if volumes ramp.
The balance sheet is the only unambiguous strength: $1.53B cash, $3.2M debt, $2.54B equity, current ratio 32.8, giving multi-year runway even at the current ~$57M/quarter operating burn. Revenue trajectory is finally scaling (Q3'25 $0 → Q4'25 $1.6M → Q1'26 $5.7M → Q2'26 $5.8M) but is a rounding error against a $5.67B market cap (P/S ~430x, EV/Sales ~310x per snapshot). Margins remain broken — Q2'26 gross margin -27%, operating margin -792%, net loss $10.3M (though improved from Q1'26's $67M loss). Free cash flow deteriorated sharply to -$126.6M in Q2'26 (vs -$57M Q1'26) as capex scaled to $69.7M — the buildout is now real and expensive. Balance sheet transformation from -$60M equity (Q3'25) to $2.54B (Q2'26) came entirely through massive dilution; shares outstanding growth is a real per-share drag that must be netted against any headline progress. Forward P/E of 503x and forward EPS of $0.03 tell you consensus barely models profitability within the forecast window.
The chart structure is uniformly bearish across timeframes. On the 1h/4h view, price collapsed through $18.50 support in a single gap-down candle around Sep 15 and has stabilized in a tight $15.00-$15.60 range at the lows — a classic distribution-into-support pattern. Daily chart shows a lower-high sequence from the ~$31 May peak with price now testing the lower band of the multi-month range; RSI 35.8 is oversold but not extreme, and price sits -13.5% below SMA20, -11.9% below SMA50, and -21.9% below SMA200 — all three moving averages sloping down. The forecast band is contradictory: 1h shows near-term stabilization near $15.6, 4h forecasts a bounce to $17.8, but the weekly forecast projects $10.28 — and importantly the model's realized 1d directional accuracy (29%) is meaningfully worse than the naive 85% baseline, so short-term forecast signals should be heavily discounted. Key levels: support $14.00 (recent low), then $11.45 (52-week low); resistance $17.00-$18.50 (breakdown zone), then $22.00 (declining trendline). ATR $1.10 (~7% daily range) means whipsaws are guaranteed.
The dominant hard-catalyst news is the Sep 4 completion of the Serra Verde acquisition — $300M cash plus ~126.8M shares issued, adding Brazil's Pela Ema mine to the Less Common Metals UK and Stillwater OK magnet facilities. This is the mine-to-magnet vertical integration thesis moving from PowerPoint to balance sheet, but the share issuance is a material dilution event that helps explain the institutional ownership drop and price weakness. The Sep 15 8-K explicitly updated risk-factor disclosures — companies rarely refresh risk language without reason, and the accompanying analyst coverage (Zacks, Motley Fool, Yahoo) has pivoted from bullish framing to skeptical comparisons highlighting cash burn and the $77.3M loss. The signal-to-noise question: policy tailwinds (2027 defense prohibition on Chinese magnets, government-backed offtake SPVs) remain intact and are the entire long-term thesis. The noise is retail sentiment (100% bullish on 15 messages — a contrarian caution flag given the tape) and the daily oscillation of pundit takes. What matters most is the L3 bearish institutional ownership drop (55.9%→37.0%) — that is smart money reducing exposure while retail cheerleads, and it aligns with the doubling of short float to 17%.
- Serra Verde acquisition closed Sep 3, 2026 — adds Pela Ema mine feedstock to complete the mine-to-magnet chain with Stillwater OK and Less Common Metals UK facilities
- First commercial magnet production milestone achieved (per Sep 14 Yahoo/Zacks coverage) — first tangible revenue-generating output from the Stillwater facility
- 2027 US defense prohibition on Chinese-sourced magnets creates a captive domestic addressable market that USAR is positioned to serve
- Revenue trajectory: $0 (Q3'25) → $1.6M (Q4'25) → $5.7M (Q1'26) → $5.8M (Q2'26) shows commercial traction, though scaling to double-digit quarterly revenue is the next proof point
- $1.55B government-backed offtake SPV structure provides non-dilutive funding channel for midstream processing scale-up
- Forward EPS estimates have been revised higher (next-Y EPS growth 76.6%→83.4%→91.0% over recent windows), indicating sell-side is modeling execution improvement
- L3-bearish institutional ownership collapse (55.9%→37.0%, -18.9pp) signals smart money exiting into the story — retail-led float is more prone to volatility
- Short float doubled 8.9%→17.0% (30.8M shares, 2.5 days to cover) — reflexive downside risk if support breaks
- Cash burn accelerating: FCF -$126.6M in Q2'26 vs -$57M in Q1'26, driven by $69.7M quarterly capex — runway is long but not infinite if this pace continues
- Extreme valuation: P/S 430x, EV/Sales 310x, forward P/E 503x — any execution slip on Serra Verde integration or revenue ramp gets punished severely
- Massive share dilution risk continues: Serra Verde deal alone issued ~126.8M shares; every future capital need likely tapped via equity given the runway/growth optics
- Sep 15 8-K explicitly updated risk-factor disclosures — companies rarely refresh risk language without reason, worth watching next filing for specifics
- Chinese rare-earth pricing pressure could impair project economics even as volumes ramp post-2027 policy catalyst
- Technical breakdown below $18.50 has no completed reversal pattern; MACD/moving averages all trending down; forecast model's near-term directional accuracy (29%) is below naive baseline (85%) — do not lean on it
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord