WW — AI Stock Forecast & Price Targets
Published 9/13/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live WW price forecast →
WW has sold off ~16% in a week to $14.78 following the appointment of subscription-background CEO Stephen Bye (viewed skeptically by a market expecting a healthcare hire), pushing the stock closer to its 52w low ($8.37) and deepening the disconnect between improving fundamentals (Q2 positive OI/FCF, restored equity of +$279M) and a broken tape. The setup is now a higher-conviction deep-value/short-squeeze candidate (20.4% short float, 0.22x P/S, 0.53x P/B, analyst target $32.50) but with confirmation risk into the Nov 5 print and an untested new operator. Constructive stance maintained, but sized as an accumulate-on-weakness with a hard stop below the summer lows.
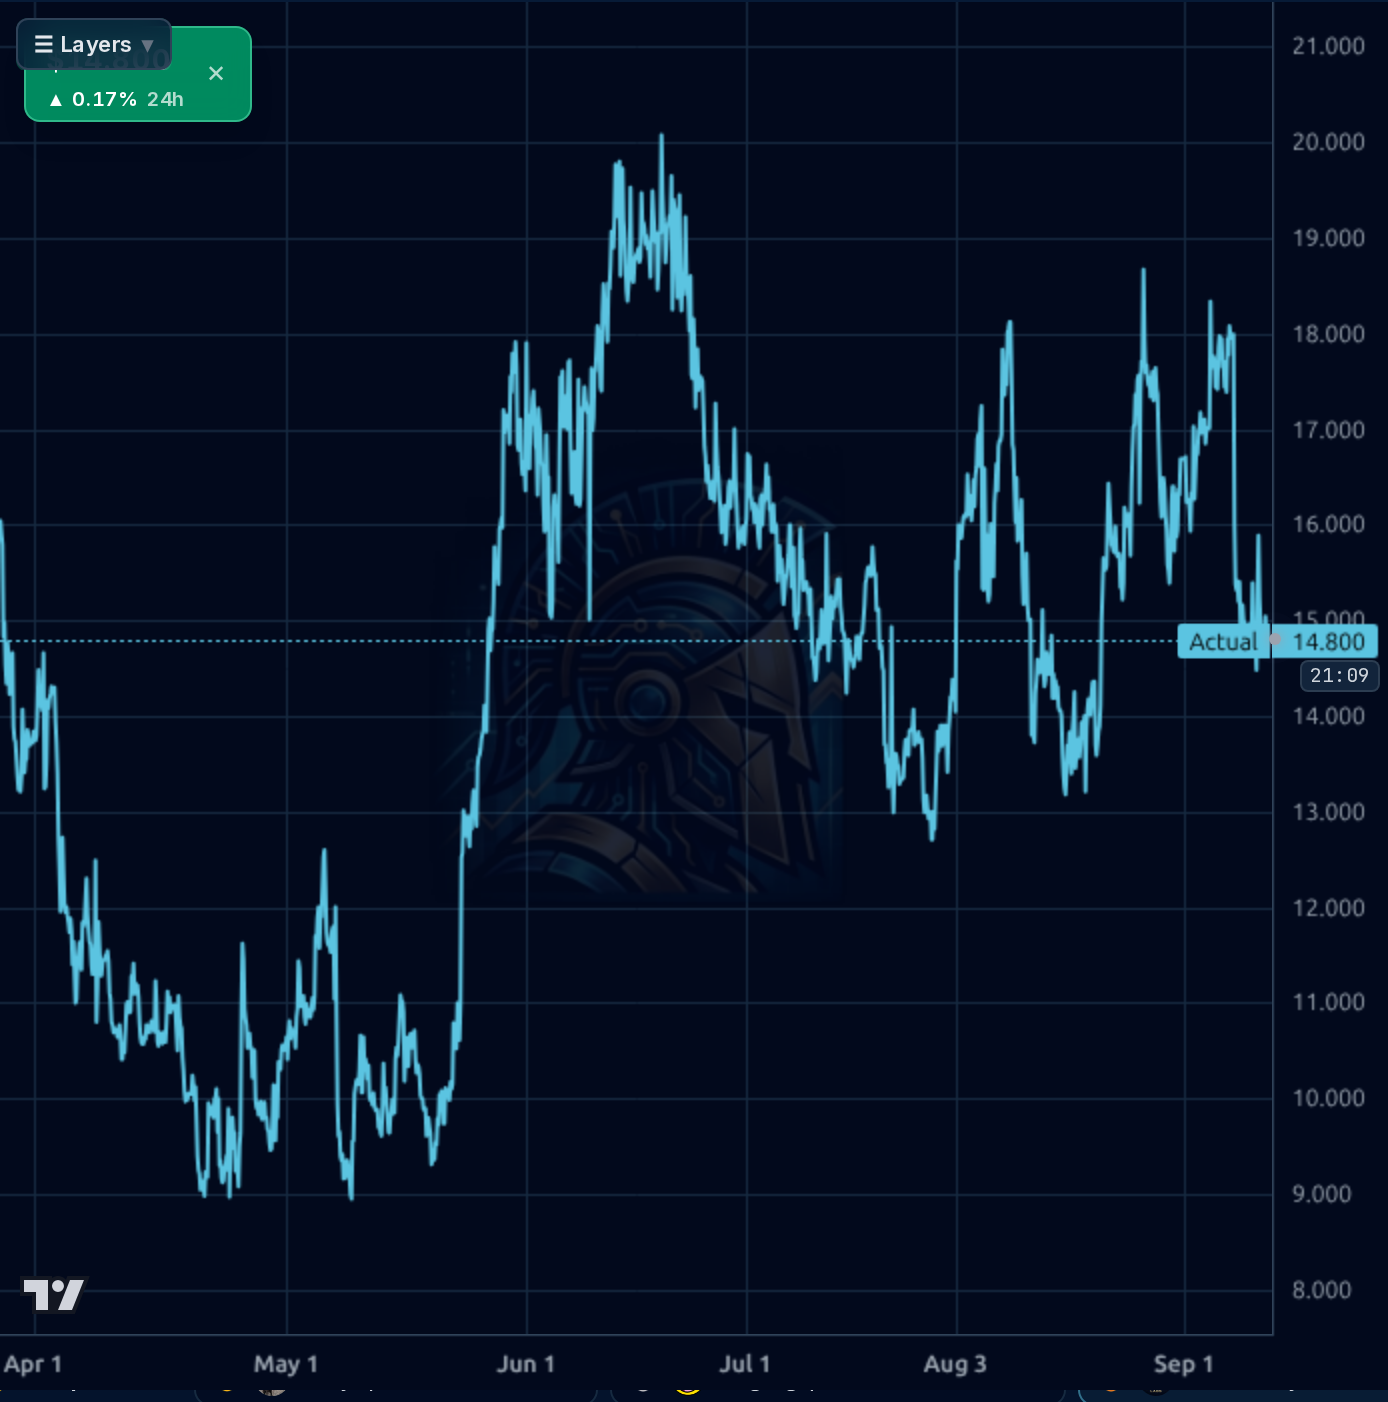
1-4 weeks: The tape is broken and momentum is against you into Bye's introduction at the Morgan Stanley conference (Sept 15). Do not chase; accumulate in the $13.50-15.00 band with tight risk management. Hard invalidation on a daily close below $12.50 (would break the April-May base and re-open the $9-10 zone). Upside trigger is a reclaim of $16 on volume, which would put $18 back in play. Size at 1/3 of intended position here; keep dry powder for either the confirming rally or the flush.
1-6 months: Two binary events dominate — (1) the Nov 5 Q3 print, where a confirming quarter of positive OI/FCF and moderating revenue decline unlocks re-rating toward 0.4-0.5x sales (~$22-28); a miss or renewed loss re-opens the $9-11 zone. (2) Bye's initial strategic communication. Base case is a grind to $19-22 as short covering (20.4% float, 9.4 days-to-cover) meets a confirming Q3. Expected return range from $14.80: -25% to +55%. What changes my mind: any sequential deterioration in clinical subscribers, or GLP-1 pricing pressure from Hims/Ro visible in Q3 ARPU commentary.
1-3 years: Terminal thesis is that WW becomes a viable Med+/HRT/weight-management subscription platform in a GLP-1 world, monetizing 55%+ growing clinical cohorts at 70%+ gross margins with a de-risked $426M debt stack. If the pivot works, book value ($27.87/sh) and even a modest 1x sales multiple imply materially higher prices. Biggest structural risk is that Med+ is a commodity funnel to compounded semaglutide/tirzepatide, and pricing power collapses as pharma DTC (Lilly Direct, Novo) and telehealth (Hims, Ro) undercut on price and brand. Bye's subscription DNA helps monetization but doesn't solve clinical differentiation.
The story remains a post-restructuring turnaround with real proof points and real caveats. Q2 2026 was the first clean quarter post-reorganization: revenue $162.3M, gross margin 70.3%, operating income $13.1M (8.1% margin), net income $14.1M, EBITDA $40.4M, operating cash flow $24.3M, and free cash flow $18.1M — a genuine inflection versus Q1's -$29.9M operating loss and -$39.3M FCF burn. The June 2025 debt exchange restored stockholders' equity from -$1.11B to +$279M and cut total debt from $1.48B to $426M, with $101M cash and current ratio 1.39, so near-term liquidity is not the risk it once was. What's still broken: revenue is contracting mid-teens (sales Q/Q -14.2%, Y/Y TTM -11.6%), TTM profit margin is -15.2%, ROE -30.7%, and D/E remains elevated at 1.53. The clinical/Med+ subscriber base is up 55.7% Y/Y per the dossier, but overall top-line trajectory still relies on Med+ ARPU offsetting core weight-management churn. Q2's positive print needs at least one confirming quarter (Nov 5) before the model can be underwritten with confidence.
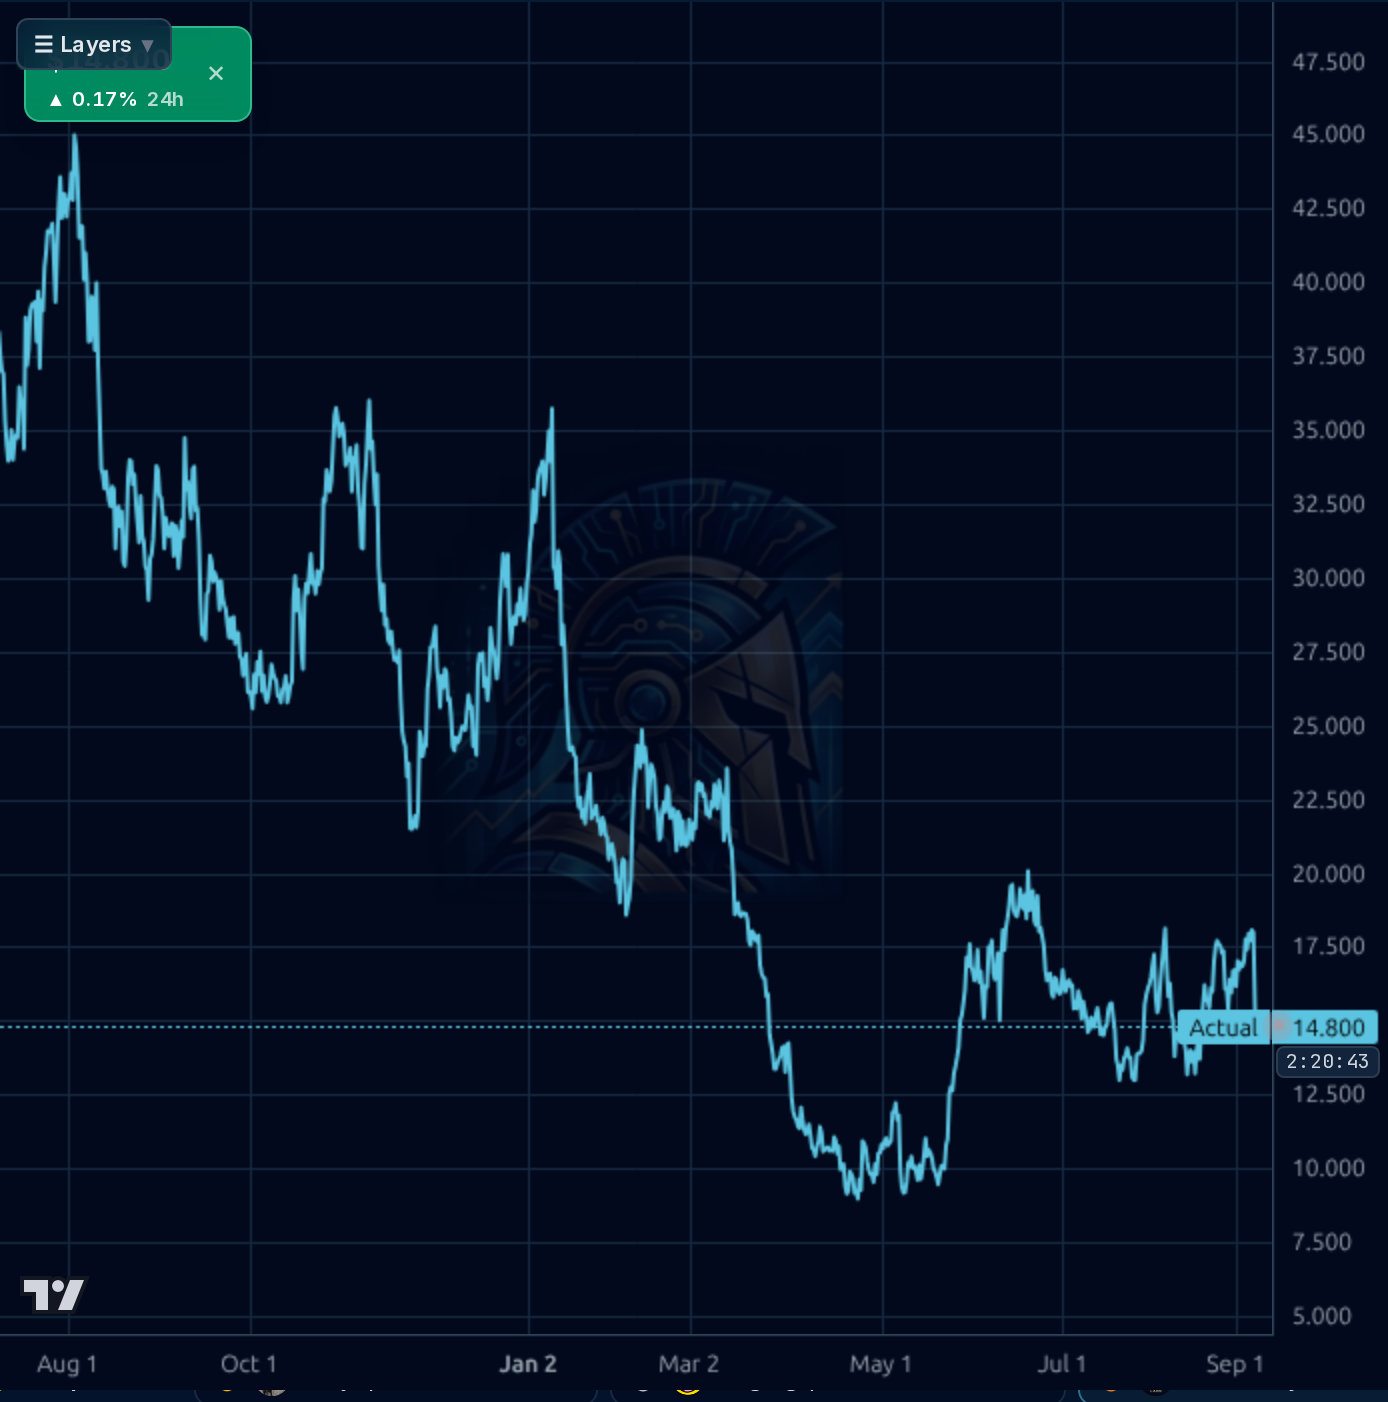
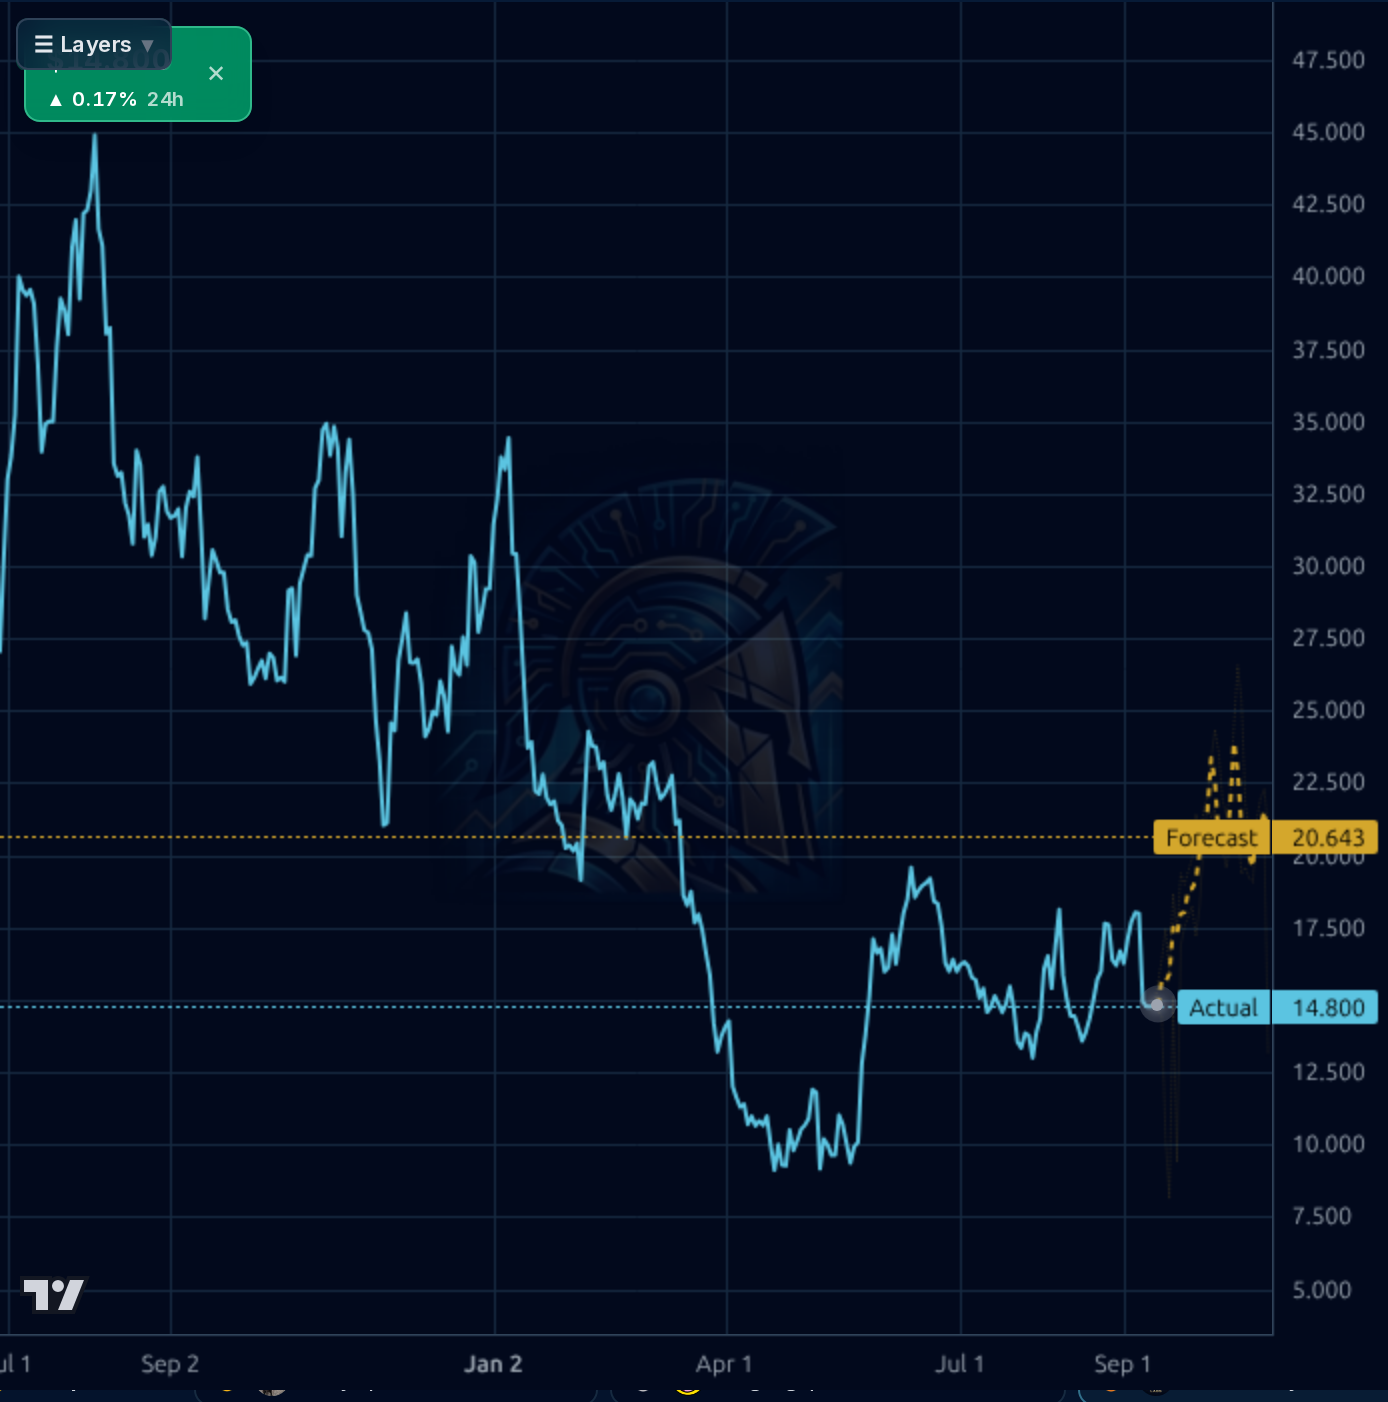
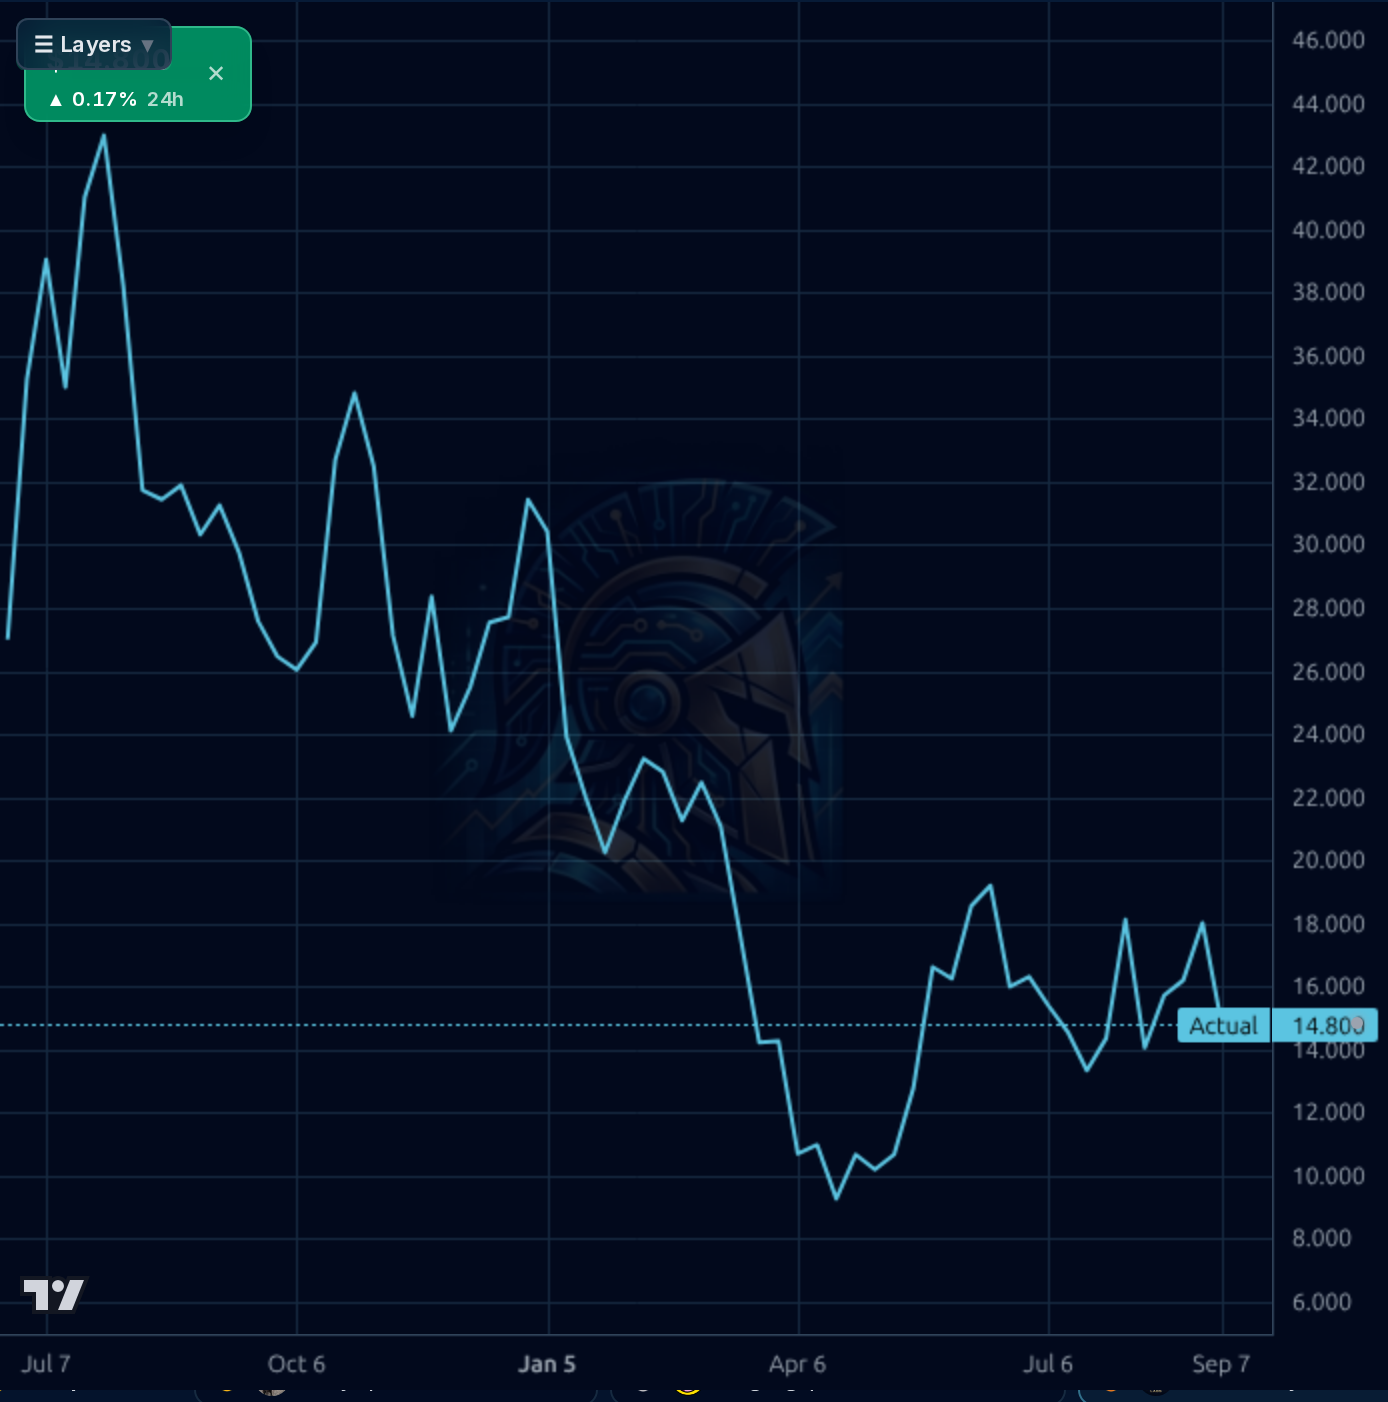
Across timeframes the picture is decidedly weak in the short run despite a constructive medium-term base. The 1H chart shows a sharp June rally to ~$20 followed by two failed retests of $18 in July and September, with a clean breakdown from $18 to $14.80 in the last few sessions. The 4H and 1D charts show price now sitting on the shelf that held in April-May ($13-15); a loss of $13.50 would open the door back to the $9-10 basing zone. RSI 43, price -7.2% vs SMA20, -4.1% vs SMA50, and -19.6% vs SMA200 — the trend structure is broken to the downside on the near-term. On the positive side, the 1D forecast band points to $20.64 (+40%) as a mean-reversion target, and 1D model directional accuracy runs 70% vs 67% baseline (marginally useful). Key levels: support $13.50 then $12/$10; resistance $16 (former shelf), then $18 (July/Sept pivot), then $20 (June high and forecast target). Beta 4.13 means any market wobble will amplify moves both ways.
The dominant catalyst is the Sept 9 8-K appointing Stephen Bye as President and CEO effective this fall. Bye comes from Ookla (connectivity intelligence) with a subscription-growth and profitability track record, which fits the board's stated 'GLP-1-era transformation and subscription growth' mandate — but retail and some sell-side observers wanted a healthcare operator, and the stock sold off 14.8% intraday on the news. The company will also present at the Morgan Stanley Healthcare Conference on Sept 15, which is the near-term chance for Bye and management to reset the narrative. Separately, the broader flow (small-cap breadth deteriorating, risk dial neutral) is not a supportive backdrop for a high-beta turnaround. Signal: the CEO hire is a real strategic pivot to consumer-subscription discipline over medical credibility, and the market is treating it as a downgrade to the Med+ pivot thesis; noise: the retail/social froth and the animal-sanctuary spam tags are irrelevant.
- Med+ clinical subscribers +55.7% Y/Y (per prior disclosure) — the primary revenue engine and the metric investors will focus on Nov 5
- Perimenopause/HRT expansion opens an adjacent women's-health TAM described in the company profile, layered onto the same clinical platform
- New CEO Stephen Bye brings subscription monetization playbook from Ookla; mandate explicitly cited by the board is 'GLP-1-era transformation' and subscription growth
- Post-restructuring balance sheet ($279M equity, $101M cash, debt cut 71%) creates optionality for tuck-in M&A or product investment without dilution
- Q2 2026 conversion of $40M EBITDA to $18M FCF at 8% operating margin — if repeatable, the model produces meaningful cash yield on a $148M market cap
- Revenue still declining -14% Q/Q and -11.6% Y/Y TTM — turnaround is cost/mix driven, not yet demand-driven
- Q1 2026 operating loss of -$29.9M means Q2's profit needs Q3 confirmation; a relapse would be devastating for a $148M-cap high-beta name
- $426M debt with D/E 1.53 leaves limited cushion for any operating stumble, and 4.13 beta amplifies macro risk-off moves
- New CEO with subscription/telecom (not healthcare) background introduces execution and credibility risk with an investor base that wanted a clinical operator
- GLP-1 commoditization from Hims, Ro, Lilly Direct and Novo DTC channels threatens Med+ pricing power and ARPU
- Short interest of 20.4% cuts both ways — squeeze fuel on good news, but reflects skeptical institutional consensus
- Tape is broken across timeframes; -49% YTD, -56% 1Y, -88% 3Y — this is a falling-knife pattern that requires a genuine catalyst to reverse
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord