ZTO — AI Stock Forecast & Price Targets
Published 9/15/2026 · A free sample of K3vl4r’s AI-powered analysis.
Kronos price forecasts, scored fundamentals & technicals, and a multi-horizon plan.
View the live ZTO price forecast →
ZTO is a fundamentally sound Chinese logistics leader trading at a reasonable 11.4x P/E with a 3.3% yield, strong FCF, and accelerating sales growth (Q2 revenue +22.97% YoY, adj. net income +50%). However, technicals are broken — price has fallen from ~$25.80 to $20.42, sitting near 52-week lows with a JPM downgrade to Neutral and PT cut to $22, so the setup is 'cheap but no catalyst' until the November print.
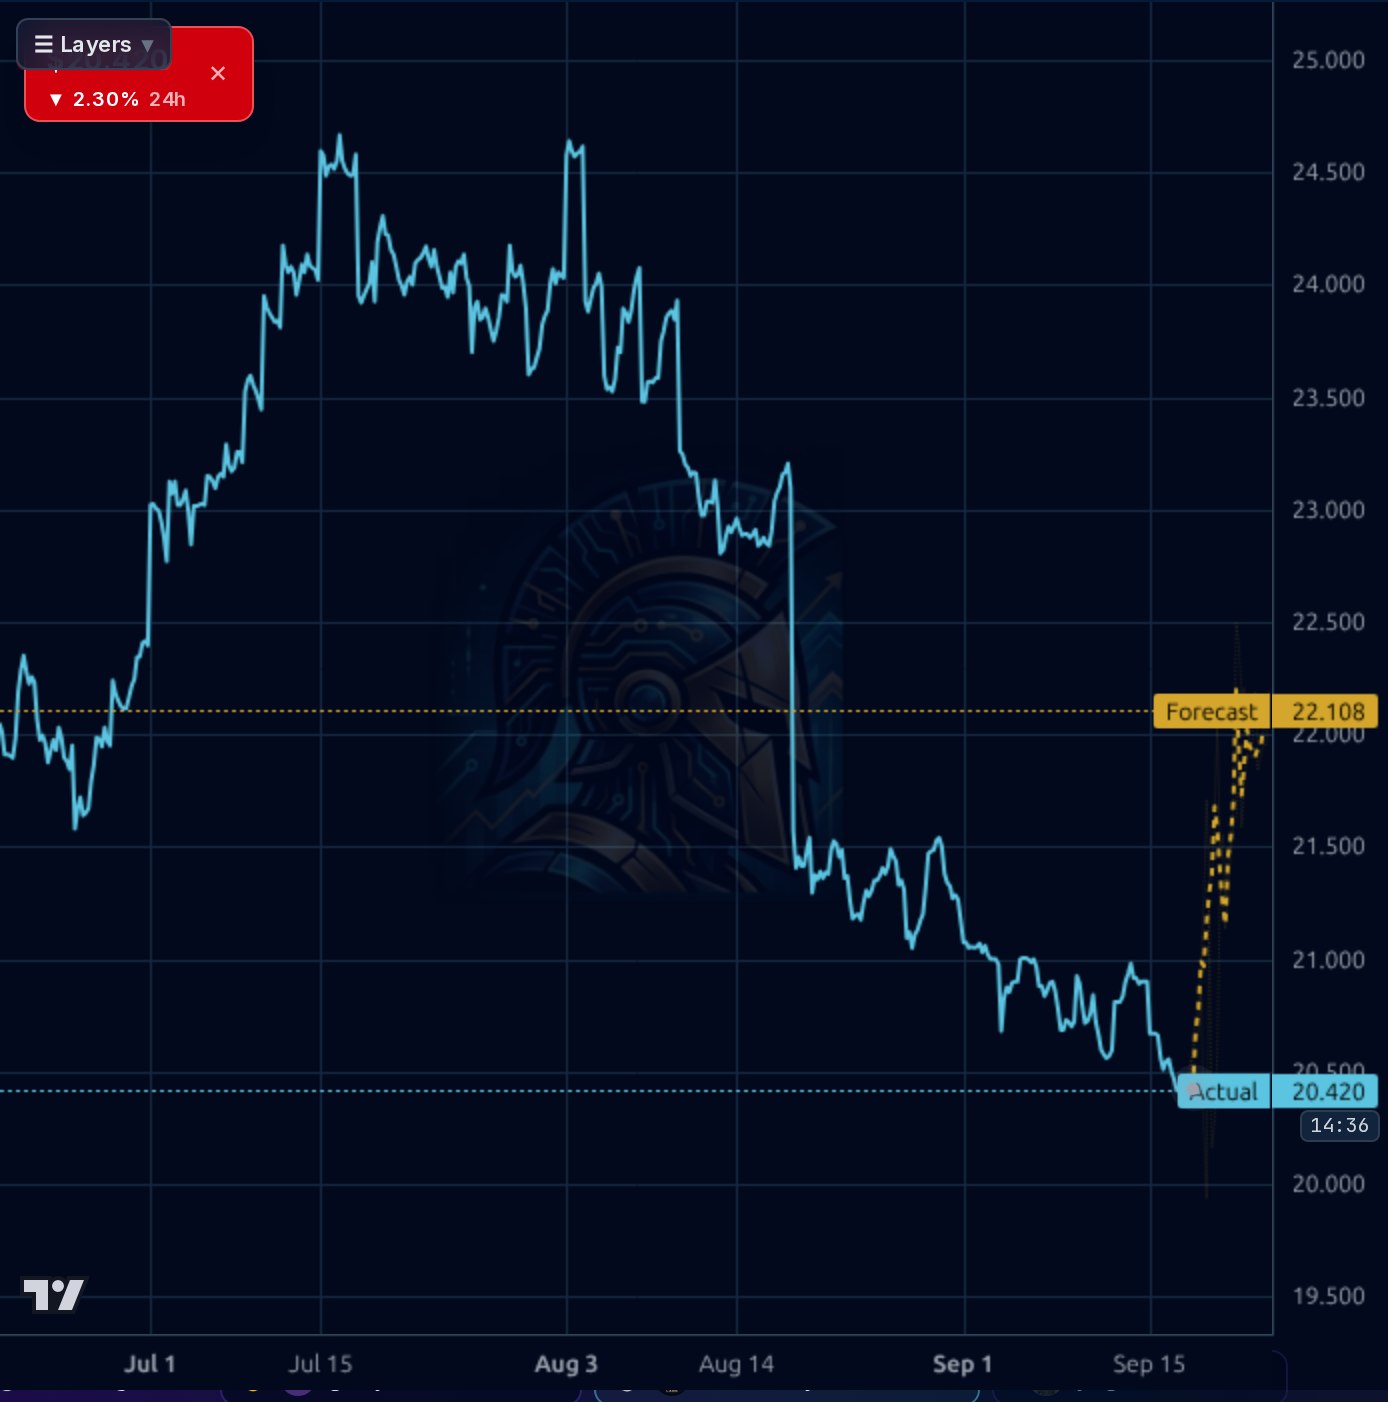
Neutral-to-cautious. Price is in a confirmed downtrend and just broke $21 support. Avoid chasing the model's bullish forecast given its poor recent accuracy. Levels: bounce resistance $21.00–$21.50 (former support flip), then $22.00 (JPM target); downside support $20.00 psychological, then $18.11 (52W low). Small starter positions can be justified below $20.50 with a stop below $19.60. Invalidation for any long: close below $19.50 on volume. Don't size up here — no reversal confirmation yet.
1–6 month view is ACCUMULATE on weakness. Fundamentals (20%+ revenue growth, 20%+ net margin, 3.3% yield, 9.1x fwd P/E, PEG 0.64) support a re-rating once selling pressure exhausts and the Nov 18 earnings print re-anchors sentiment. Expected return range from current $20.42: -10% to +15% (roughly $18.50–$23.50). Base case is range-bound $19.50–$23.00 with dividend collection while the market digests the JPM downgrade. What changes my mind bullishly: Q3 print re-accelerating margins with capital return commentary; bearishly: any evidence that 'no price wars' rhetoric breaks and ASP resumes declining.
1–3 year terminal thesis remains constructive. ZTO is a scaled leader in Chinese express with structural cost advantages, and at ~1.3x EV/Sales and 4.9x EV/EBITDA it is priced for stagnation, not for a company growing sales 20% and earnings 25%+ YoY TTM. Long-run drivers: continued Chinese e-commerce parcel volume growth, AI/automation-led unit cost declines management called out, and potential mean reversion of the discount vs. global logistics peers. The biggest structural risk is not the balance sheet — it's China ADR sentiment/geopolitical overhang and the persistent risk of a domestic price war resuming, which would collapse the margin story that just re-emerged.
The fundamental picture is genuinely strong and improving. Q2 2026 revenue of ¥14.55B grew 22.97% YoY with net income of ¥3.05B (net margin 20.97%, up from 15.95% in Q1), and operating margin expanded to 22.54%. TTM revenue is ¥54.2B with 20.9% Y/Y growth and management cited AI/digitalization driving cost reductions. Balance sheet is solid with current ratio 1.67, cash of ¥31.3B against ¥22.0B total debt (net cash positive), and LT Debt/Eq of just 0.16 — the headline D/E of 34.6 is misleading as it likely reflects lease accounting rather than dangerous leverage. FCF of ¥6.4B TTM funds a 3.3% dividend with a manageable 43% payout ratio. ROE 16.1%, ROIC 13.5%, and EV/EBITDA of 4.86 are attractive. The only real fundamental knock is that JPM's downgrade suggests price competition or volume normalization may pressure the 2H trajectory despite the strong 1H.
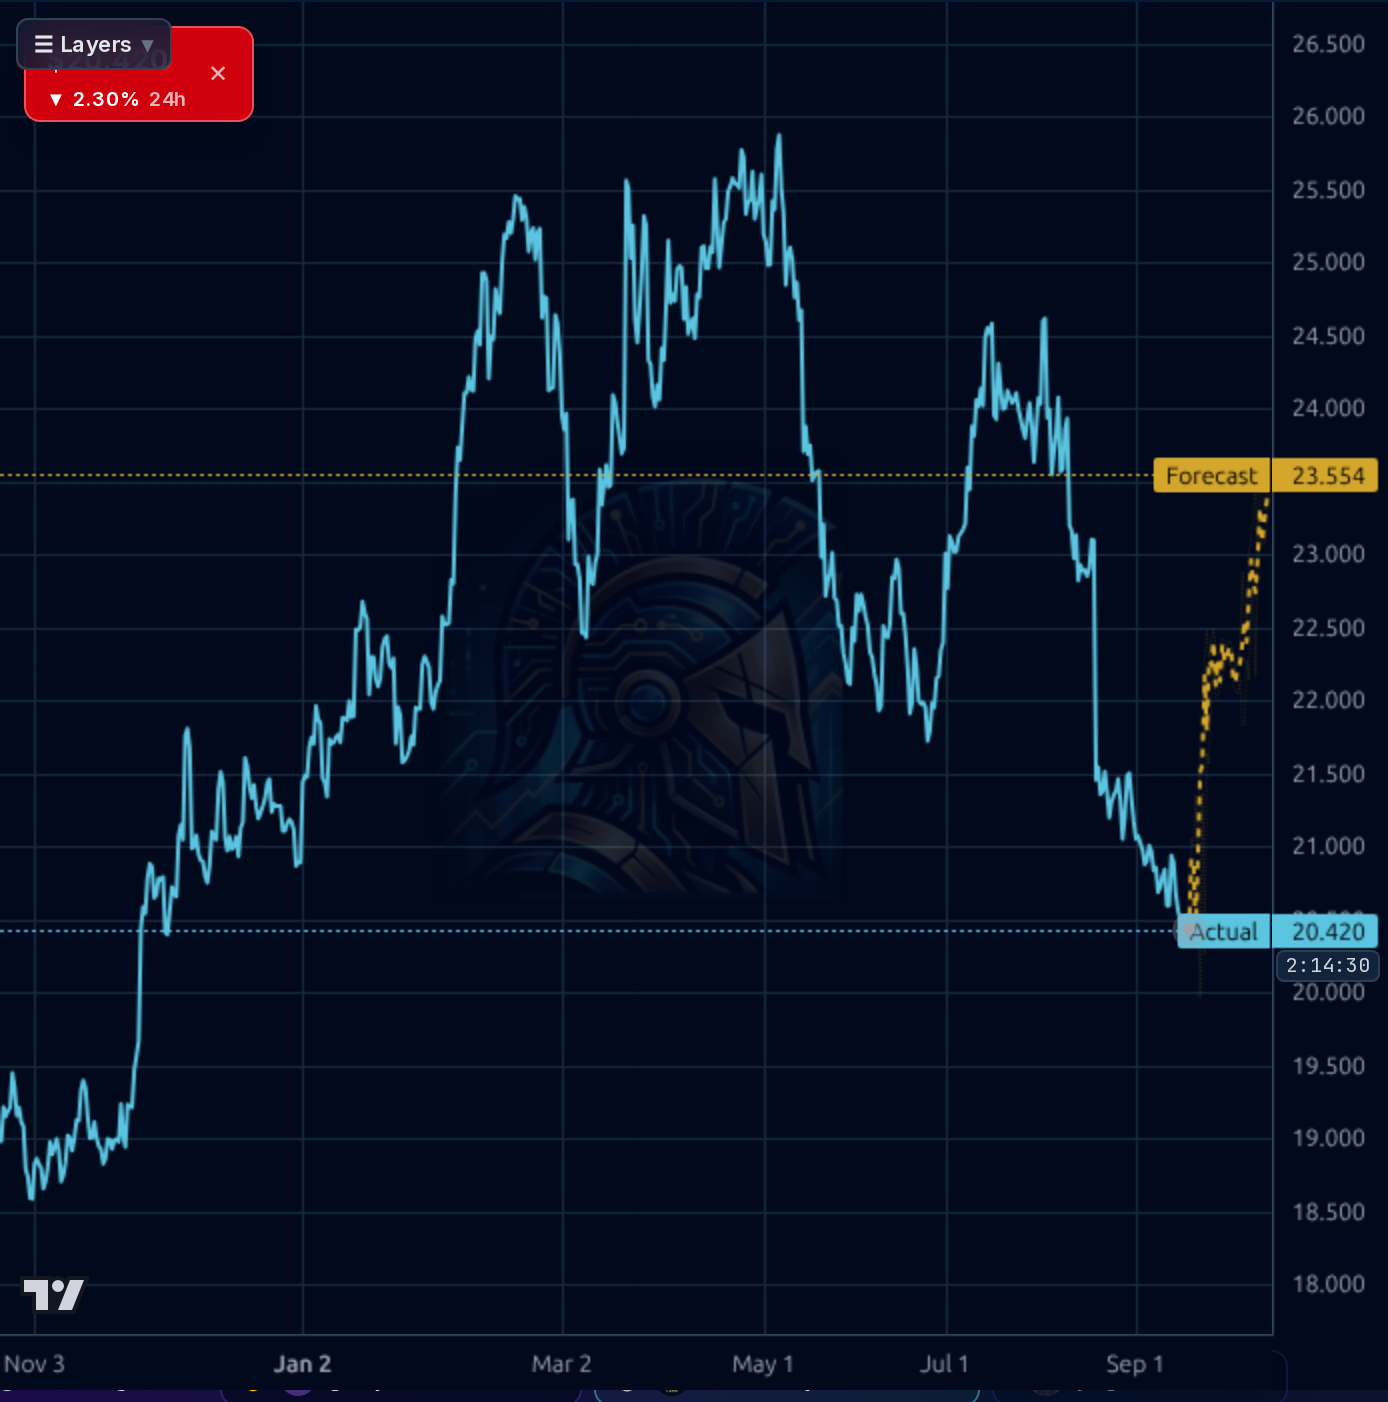
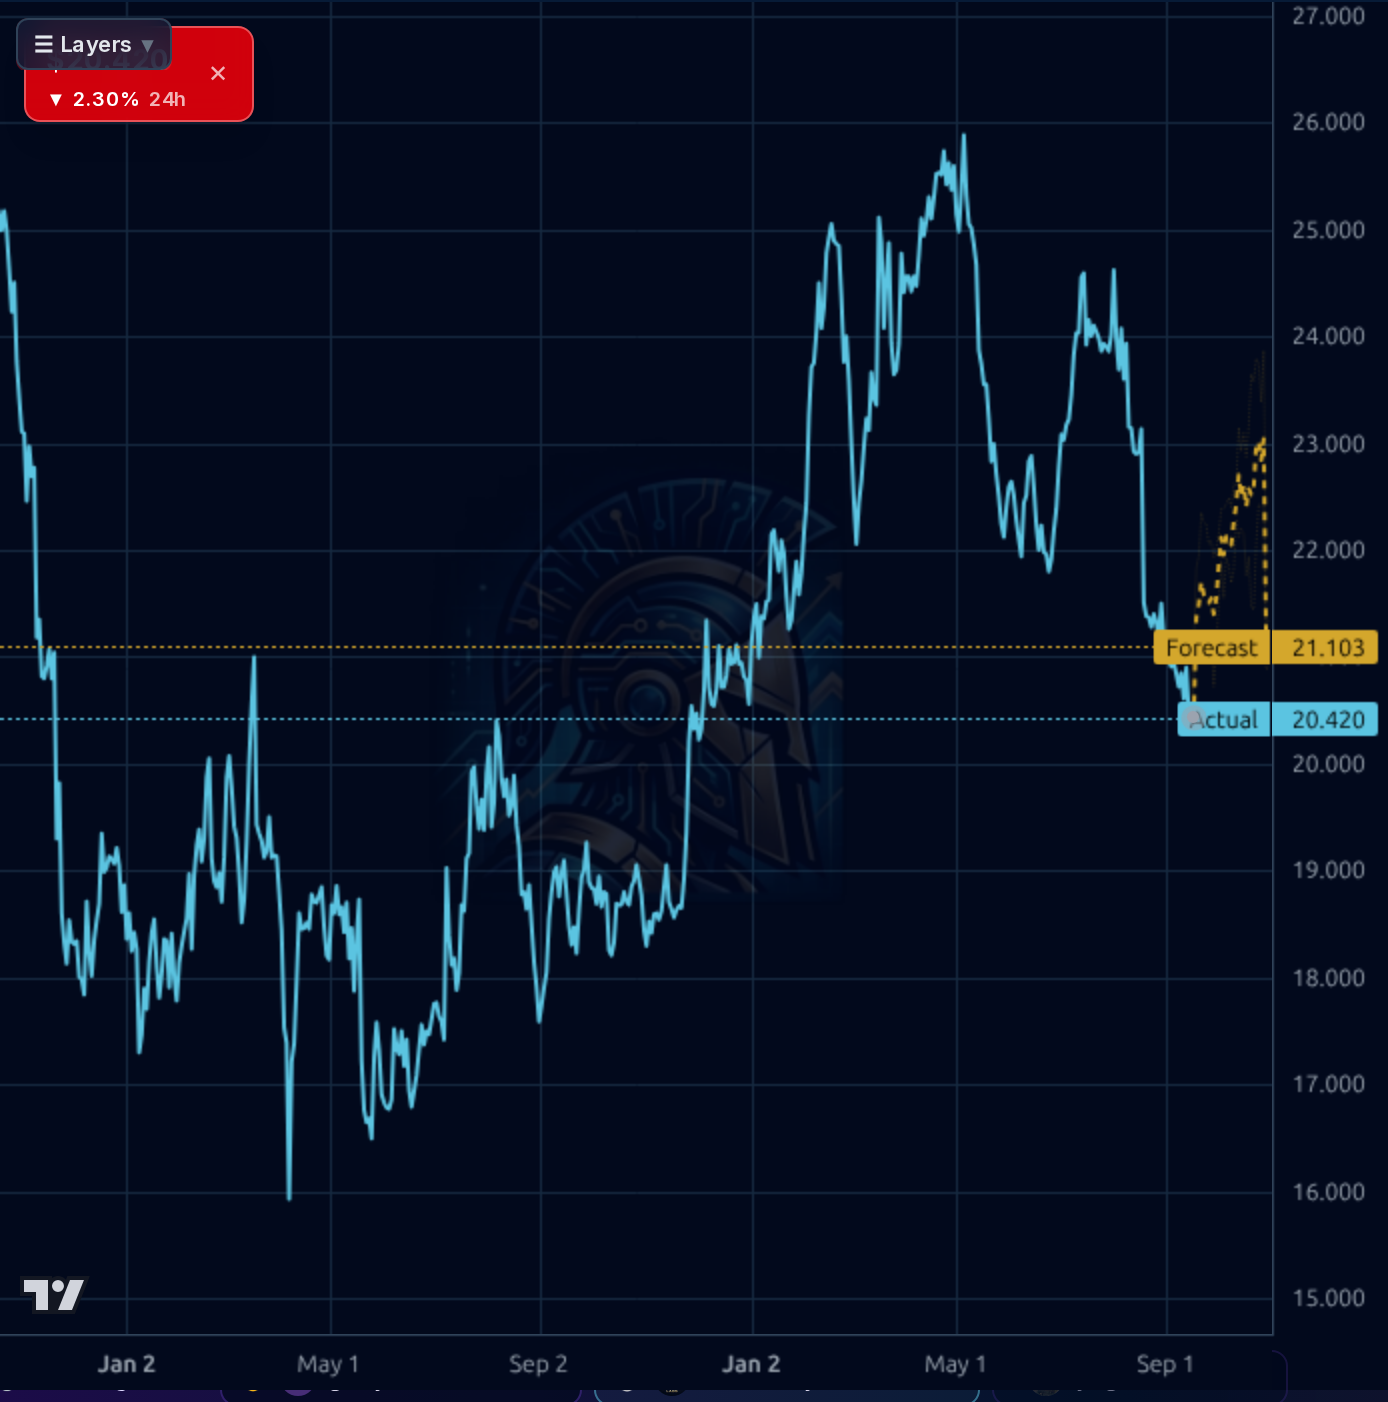
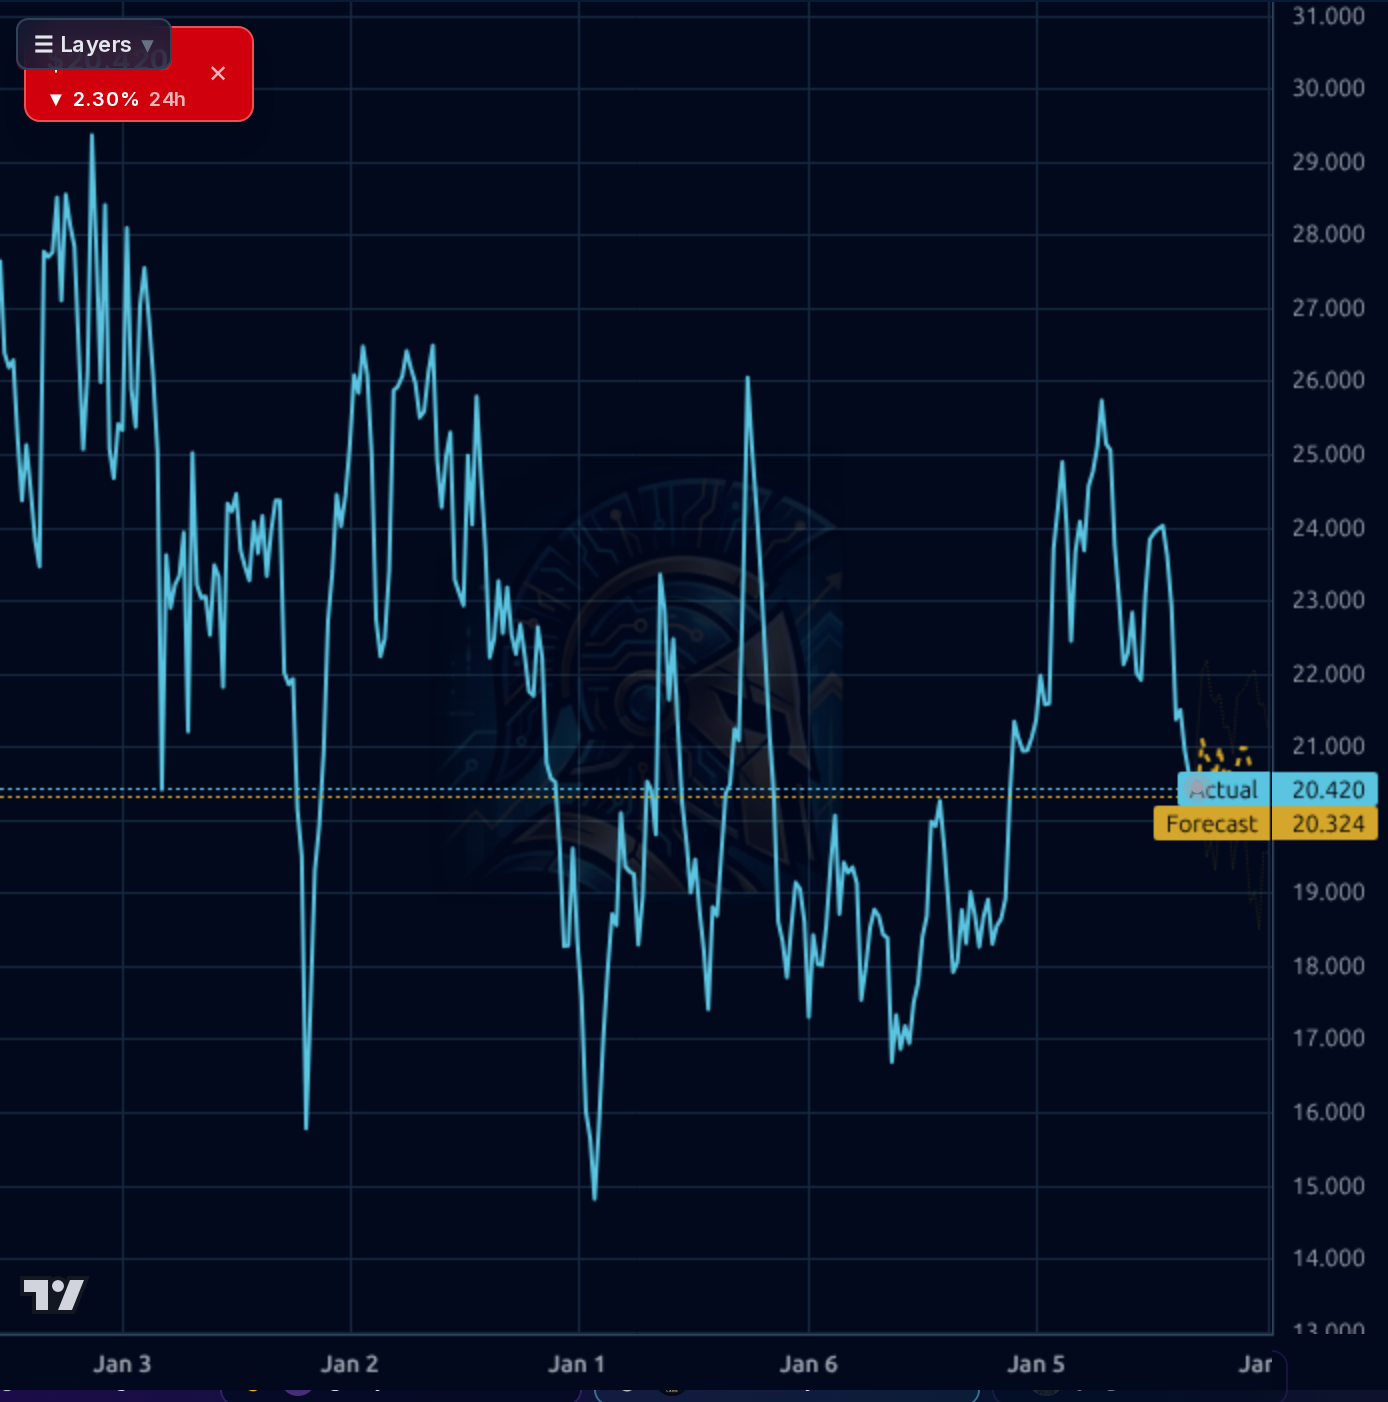
Technicals are ugly and remain the dominant near-term signal. The 1D chart shows a clean downtrend from ~$24.60 in early July to $20.42, breaking through prior support at $21.00 with no meaningful bounce. Price sits -20.2% from the 52-week high of $26.20, -9.5% below the 200SMA, -8.3% below the 50SMA, and RSI at 35.5 is weak but not yet washed out. The weekly chart shows price back to the lower end of a multi-year $18–$26 range, testing the breakout shelf from early 2026. The forecast model is bullish (1d prob 1.00, targeting $21.10–$23.55 across timeframes), but its recent directional accuracy of 27% (1d) and 33% (1wk) is materially WORSE than the naive baseline of 91–100%, meaning the model is unreliable in this regime — I'm heavily discounting the yellow band. No confirmed reversal signal yet; $20.00 is the next visible support, then the $18.11 52-week low.
The signal-dominant news is mixed. Q2 earnings (Aug 18) were objectively strong — adjusted net income +50.3% YoY, parcel volume 10.49B, and management highlighted 'no price wars' and AI-driven cost cuts. SeekingAlpha reiterated Buy on the thesis of 'price over volume.' However, JPM's Sept 3 downgrade from Overweight to Neutral with PT cut from $29 to $22 is the more market-moving item and explains much of the subsequent slide — a bulge-bracket bank flagging that the risk/reward has narrowed materially. ChartMill's GARP framing is supportive but doesn't provide a catalyst. Noise: retail sentiment is 80% bullish on Stocktwits, which in a downtrending name is a mild contrarian negative. Broader market news items in the feed (Nyxoah, Glass House, etc.) are unrelated. Net: the fundamentals justify the name but the sell-side cut has capped upside expectations near $22, exactly where the forecast band clusters.
- AI and digitalization initiatives cited on the Q2 call as material cost reduction levers — management explicitly attributed EPS beat to them
- Parcel volume of 10.49B in Q2 with management raising annual parcel-volume guidance per Stocktwits earnings recap
- Margin expansion trajectory: net margin rose from 15.95% (Q1) → 20.97% (Q2), showing operating leverage
- Sales growth estimate revised upward from 15.9% to 20.9% (+5pp) per fundamental-change signal
- 3.3% dividend yield with 43% payout ratio leaves room for capital return acceleration
- JPM downgrade to Neutral with $22 PT (Sept 3) caps sell-side upside expectations and coincides with technical breakdown
- Technical trend is decisively down: price -13% since prior report, breaking $21 support with no reversal signal
- Forecast model directional accuracy (27% 1d, 33% 1wk) is well below naive baseline — bullish forecast should be heavily discounted
- China ADR/geopolitical overhang persistently suppresses multiple regardless of operating results
- 'No price wars' commentary from management is a fragile competitive assumption; any renewed competition would compress the just-recovered margins
- Macro backdrop is risk-off (breadth 44% >200dMA and deteriorating), limiting appetite for beaten-down China names
- Retail sentiment 80% bullish on Stocktwits in a downtrend is a mild contrarian negative
Get AI analysis on any stock
This is one of hundreds of Kronos AI reports — scored fundamentals & technicals, bull/base/bear price targets, a multi-horizon plan, and continuously-updated forecasts across the market. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord