Today’s AI Top Pick: CALX
9/30/2026 · Turnaround Undervalued Accumilate screen · a free sample of K3vl4r’s AI-curated picks.
AI-ranked from a screened shortlist, with entry strategy, targets, and risks.
View the live CALX price forecast →
Calix is the best risk/reward entry in this pool because it combines a clean fundamental turnaround with genuine multi-timeframe technical agreement, and it is NOT chasing a top. The stock sits at a -11.06% drawdown off its 21-bar high on the daily, but crucially it is positioned in the lower-middle of its range (pos_in_21bar_range_pct of 8.55 on 1d, 8.14 on 4h), meaning there is still room to run rather than chasing an exhausted move. The forecast tape is the deciding factor: the 4h shows fc_long_pct of 73.79% bullish, the 1d shows fc_long_pct of 38.70% bullish, and the 1wk shows fc_long_pct of 28.80% bullish — a rare alignment where all three horizons lean up while price is still depressed. Bullish probability is 1.0 and near-term bullish is 1.0, both at the top of the distribution. Fundamentally, CALX is a legitimate turnaround story, not a value trap. Forward P/E of 14.56 and PEG of 0.41 are attractive for a company with epsNextY growth of 33.84% and salesYoY growth of 27.84%. The analyst recommendation of 1.22 (strong buy) and target upside of 85.9% signal deep conviction. While trailing P/E of 44.62 looks elevated, that is a lagging artifact of a depressed-earnings base year, not a current overvaluation — the forward metrics tell the real story. Institutional ownership of 95.94% confirms smart money is aboard. The news flow is a strong positive catalyst, not a landmine: Calix just completed a successful 50G-PON trial demonstrating a path to rapid growth without network overhauls, and announced Q3 results for November 2, 2026 — a near-term catalyst that could re-rate the stock. Additional tailwinds include the Chariton Valley AI workforce deal and live access to Calix ConneXions 2026. Unlike ETOR (migration execution risk) or BILI (dilutive convertible raise), CALX has no dilution or regulatory overhang. Unlike KVYO and MNDY, which are getting 'obliterated' on weak guidance, CALX's fundamentals support the tape. This is the only name where fundamentals, multi-timeframe forecast, and catalysts all converge at a non-stretched entry.
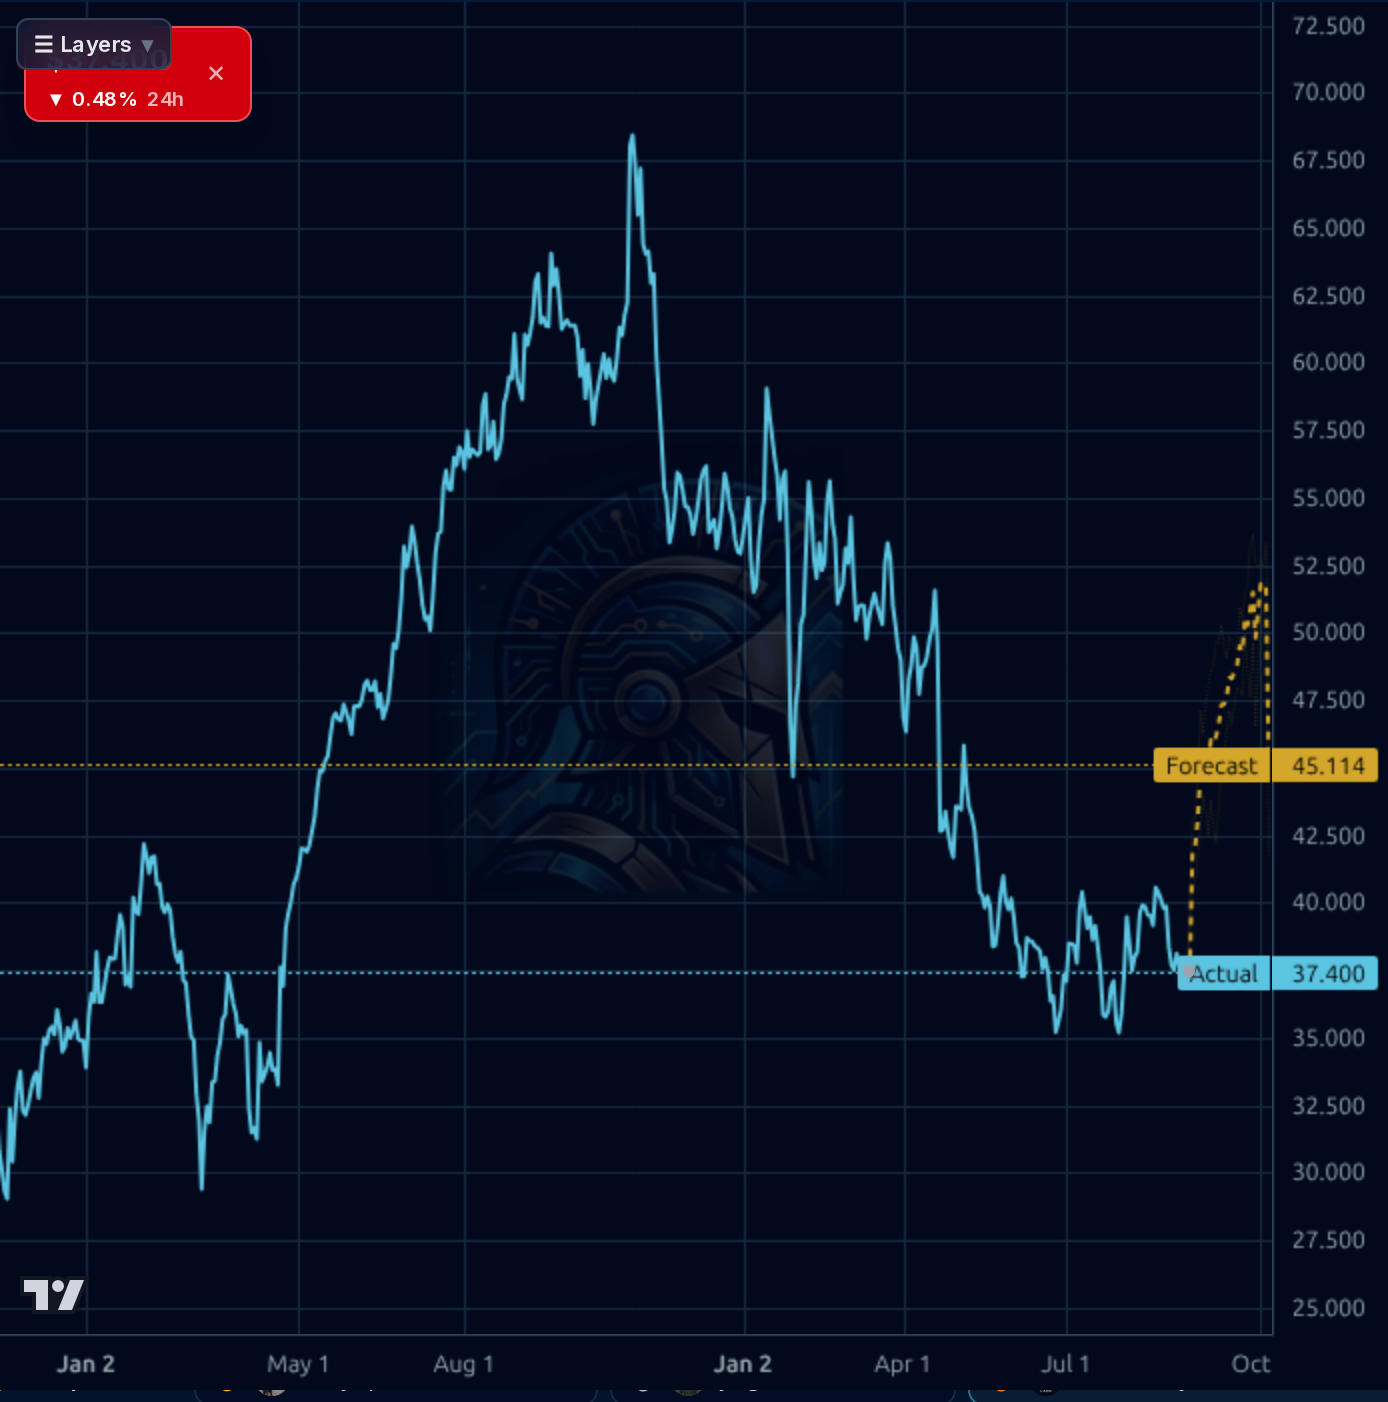
- Q3 earnings on Nov 2, 2026 is a binary event — a miss on a high-growth name could trigger a sharp de-rating given the elevated trailing P/E of 44.62
- Small-cap concentration risk with market cap of $2.1B and shortFloat of 9.80% creates volatility and squeeze risk in either direction
- Operating margin of only 5.51% and profit margin of 4.61% leave little room for error if growth decelerates below the 27.84% sales growth run-rate
- The 1wk forecast (fc_long_pct 28.80%) is the weakest of the three timeframes, suggesting the weekly trend has not fully confirmed the reversal
- High institutional ownership (95.94%) means potential liquidity pressure if sentiment shifts simultaneously
| # | Symbol | Verdict | Score | Read |
|---|---|---|---|---|
| 1 | CALX | BUY NOW | 9.2 | Clean multi-timeframe bullish alignment at a non-stretched entry with a Nov 2 earnings catalyst and no dilution overhang. |
| 2 | ORCL | BUY PULLBACK | 8.8 | Superior fundamentals and 76% upside, but the 1wk forecast is bearish (-2.56% fc_long) so wait for weekly confirmation. |
| 3 | BABA | BUY PULLBACK | 8.5 | Strong 4h/1d alignment and cheap valuation, but China ADR risk caps conviction. |
| 4 | TMUS | BUY NOW | 8.0 | All-timeframe bullish with 48.3% upside and a 15% dividend raise, though fee-raise headline is a minor overhang. |
| 5 | ETOR | BUY PULLBACK | 7.8 | Cheap (fwd P/E 8.45) and strong 4h forecast, but Oct 4 migration execution risk warrants a pullback entry. |
| 6 | OPFI | BUY NOW | 7.5 | Extremely cheap (fwd P/E 3.15, PEG 0.17) with 118.9% upside and insider buying, but tiny $519M cap and merger integration risk. |
| 7 | FSLR | BUY PULLBACK | 7.2 | KeyBanc upgrade is positive, but pricing pressure from high inventory is a credible headwind to the thesis. |
| 8 | PGY | BUY PULLBACK | 7.0 | StoneX Buy with $33 target, but insider selling and high shortFloat (15.63%) signal skepticism. |
| 9 | BIRK | BUY NOW | 6.8 | Sector-leading growth at attractive fwd P/E 11.86, but price near 4h range high (85.26%) argues for a pullback. |
| 10 | RKT | BUY PULLBACK | 6.5 | VantageScore leadership is a real catalyst, but 77.78 trailing P/E and mortgage sector weakness cap appeal. |
| 11 | FUTU | BUY PULLBACK | 6.2 | Strong margins (69% oper) and cheap fwd P/E 8.88, but 4h at 100% of range means chase risk. |
| 12 | ACM | BUY PULLBACK | 6.0 | Design franchise intact with 60.41% eps growth, but 52-week low and legacy contract charge need to clear. |
| 13 | JD | BUY NOW | 5.8 | Cheap (fwd P/E 6.28) with all-timeframe bullish tape, but China consumer weakness is a persistent overhang. |
| 14 | KVYO | BUY PULLBACK | 5.5 | AI platform catalysts are compelling, but 719x trailing P/E and director selling demand a deeper pullback. |
| 15 | MNDY | WAIT | 5.2 | Elevate AI catalyst is real, but shares getting 'obliterated' on weak guidance — wait for stabilization. |
| 16 | NRG | BUY PULLBACK | 5.0 | Cheap on forward earnings with 96.5% upside, but high debtEq of 4.83 and negative operating trend are caution flags. |
| 17 | PFSI | WAIT | 4.8 | Very cheap (fwd P/E 5.85) but Q2 miss and analyst target cuts mean the knife may still be falling. |
| 18 | MLCO | BUY PULLBACK | 4.5 | Strong seasonality and casino recovery narrative, but null ROE and 53.66% YTD decline signal a fragile turnaround. |
| 19 | INTR | WAIT | 4.2 | Cheap Brazilian fintech with 51% sales growth, but high debtEq of 3.10 and weak 1wk forecast argue for patience. |
| 20 | ADNT | BUY PULLBACK | 4.0 | JPM upgrade to Overweight is positive, but null ROE and low 2.73% returns cap the setup. |
| 21 | MAT | WAIT | 3.8 | Turnover to new CEO Lynch is a catalyst, but 2.9% sales growth and tariff exposure need clarity. |
| 22 | UIS | WAIT | 3.5 | Innovative brand and fwd P/E 2.16 look cheap, but negative profit margin of -21.65% and pension charges are red flags. |
| 23 | BN | WAIT | 3.2 | Quality franchise at fwd P/E 10.79, but workforce cuts and 67.98x trailing P/E create uncertainty. |
| 24 | ADTN | AVOID | 2.8 | Huge epsNextY of 101.73% looks attractive, but -50% drawdown, negative margins, and 'Hold' consensus signal a broken setup. |
| 25 | STEP | AVOID | 2.5 | Real estate secondaries tailwind is real, but null P/E, -750% ROE, and -53% operating margin are too fragile. |
| 26 | COUR | WAIT | 2.2 | AI skills narrative is compelling, but negative margins and -61% YTD decline need a clearer inflection. |
| 27 | AMRC | WAIT | 2.0 | Army nuclear lease talks are a catalyst, but 40x trailing P/E and -37% weekly drawdown demand confirmation. |
| 28 | NU | BUY PULLBACK | 1.8 | Monzo acquisition optionality is exciting, but 16.81x P/E for a fast-growing name and Brazil concentration warrant a pullback entry. |
Get AI top picks & forecasts on any stock
K3vl4r screens the market daily and ranks the best setups with AI — forecasts, scored fundamentals & technicals, and multi-horizon price targets. Create a free account to explore them all.
Create your free account →Already a member? Sign in · Join our Discord